1991issue C031-12
Regime-gated MACD and stochastic rules inside a checklist
A checklist-process can first apply an adx-regime-gate, then use macd or a stochastic-oscillator according to the assigned confidence-factor. The inference-engine stops when an action-level fact is added to the knowledge-base.
- Write the checklist-process as heuristic if-then rules that fire only when their conditions are already in the knowledge-base, then add a new fact rather than claim certainty.
- An 18-period adx-regime-gate marks a trending or non-trending state, after which macd is the stronger signal in a trend and a nine-period slow stochastic-oscillator is the complementary oscillator when the market is not trending.
- When several unused rules are eligible, conflict-resolution prefers the higher confidence-factor and the inference-engine stops at the first action-level fact.
- Obtain each confidence-factor by testing an indicator separately in different market environments and recording its win/loss ratio, rather than assuming one weight fits every regime.
Write the checklist as if-then facts
A trading-systems-decision-process is a repeatable sequence that turns market observations into an explicit entry, exit, or stand-aside decision. This combination uses a checklist-process: a written set of if-then gates that must be satisfied, in order, before a trade is taken or refused.
The checklist can be written as heuristic if-then rules. A rule fires only when its stated conditions are already in the knowledge-base, the inventory of current facts the checklist is allowed to consult. The rule then adds a new fact. It does not claim certainty.
Let the inference-engine pick one unused rule
The inference-engine scans eligible unused rules, prefers the unused rule with the higher attached reliability weight when more than one can fire, and stops once an action-level fact is obtained. That choice among several eligible rules is conflict-resolution. The attached reliability weight is the confidence-factor on the rule.
Forward-chaining starts from observed facts and works toward an action. Backward-chaining starts from a hypothesized action and asks whether the supporting facts can be established.
Classify regime before an indicator adds an action
An 18-period ADX reading is used as an adx-regime-gate. A reading above 15 that is at least as high as two days earlier marks a trending state. A reading below 30 that is no higher than two days earlier marks a non-trending state. The adx-regime-gate is used only to decide whether the market is treated as trending or non-trending.
Treat MACD as the stronger trending signal
MACD is treated as the stronger signal in a trending regime and the weaker signal in a non-trending regime. Complementary reliability weights are assigned to a nine-period slow stochastic-oscillator.
MACD buy and sell hypotheses are defined as the MACD line crossing above or below its signal line. The MACD line is the difference of two exponentially smoothed averages. The signal line is a further smoothing of that difference.
Use the stochastic-oscillator when the market is not trending
In a non-trending regime the nine-period slow stochastic-oscillator is used as an overbought or oversold oscillator. %K is taken from a nine-period window, and both %K and %D are further smoothed over three periods.
The stochastic buy rule requires both SK and SD below 30, with SK below SD, then SK crossing above SD next period. The sell rule requires both SK and SD above 70, with SK above SD, then SK remaining above SD next period.
Change the knowledge-base when market character changes
Rule reliability weights are obtained by testing an indicator separately in different market environments and recording its win/loss ratio. One confidence-factor is not assumed to fit every regime.
A constructed checklist can switch among different knowledge bases when market character changes, including the rate of change of the trend. It can combine technical readings with other indicator classes in one procedure.
MACD line and signal line versus Dow Jones Industrial Average
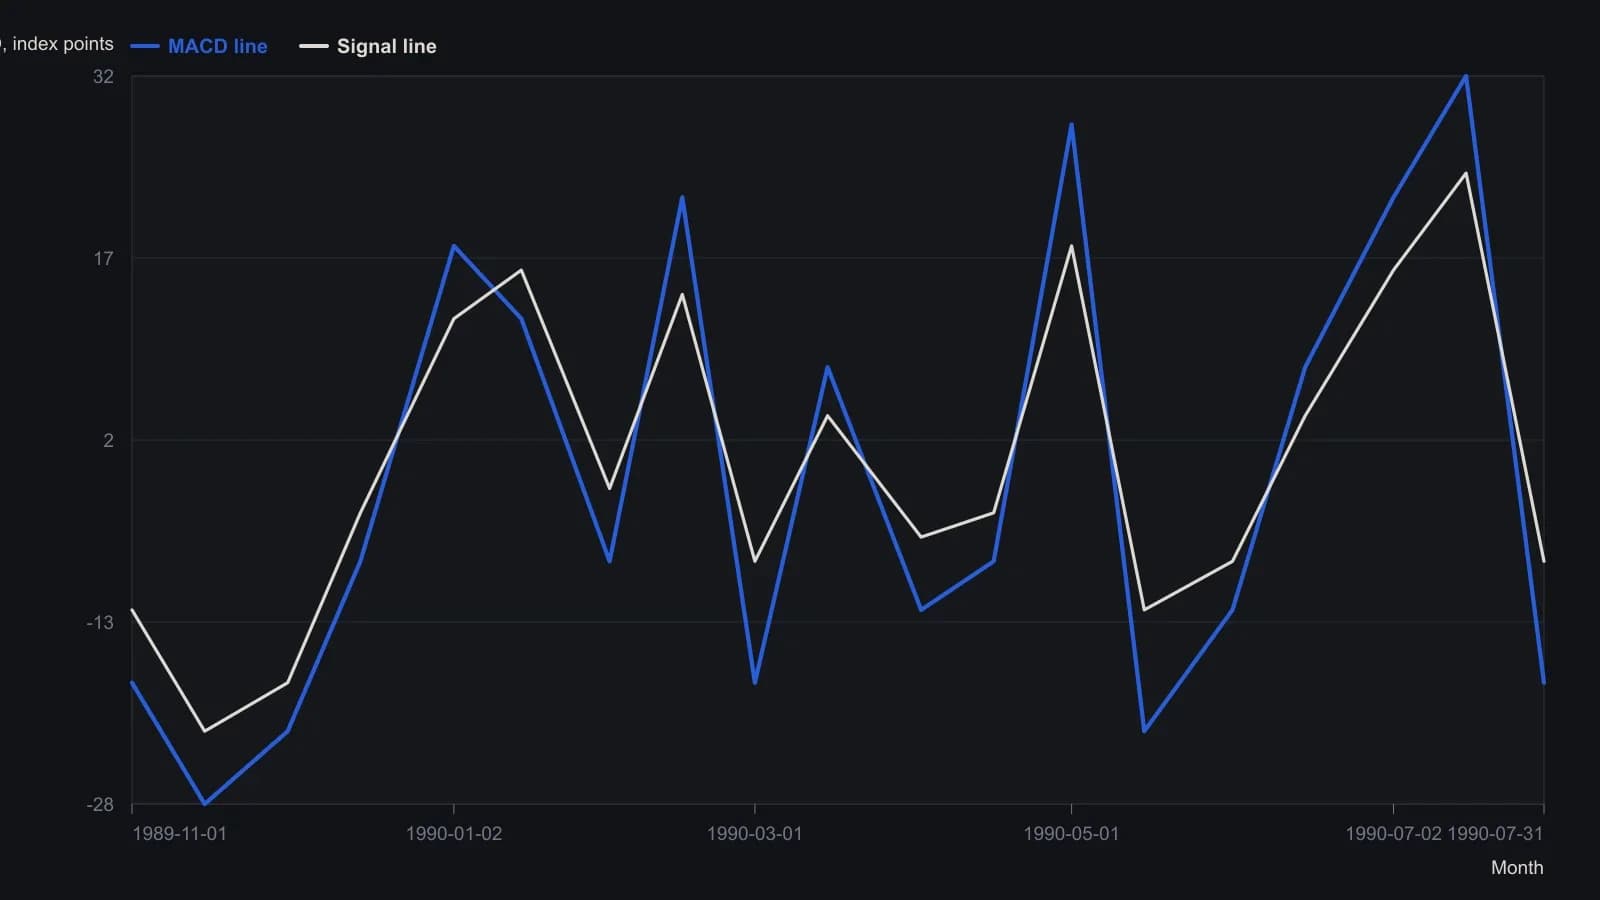
Source uses exponential constants 0.15 and 0.075 for the MACD line and 0.2 for the signal line. Digitized from a low-resolution inverted scan; y-values are approximate and should not be treated as exact prints.
All readings on this track · 80 readings
- 1988Rebuild MACD-Mo and MACD-H before treating them as signals
- 1989Four-span MACD lookbacks as perishable parameters
- 1989Weekly then daily MACD confirmation on individual stocks
- 1991Regime-gated MACD and stochastic rules inside a checklist
- 1991Constructing MACD signal lines and divergence tests
- 1991MACD parameter order and cycle phase lag
- 1992Lengthened bond MACD as an equity regime filter
- 1992Long-horizon MACD construction from paired exponential averages
- 1993Constructing a signed ten-point trend filter
- 1994Constructing lag-reduced double exponential averages for MACD
- 1994Seeding DEMA2 filters to build a MACD signal
- 1994Constructing MACD from lag-reduced exponential averages
- 1994TEMA1 from nested exponential averages, then a two-horizon MACD
- 1994Constructing entry and exit on a relative-strength MACD
- 1994Constructing a relative-strength MACD crossover spreadsheet
- 1995Consensus presignal filters for Relative Strength Index, MACD and the Stochastic oscillator
- 1997Confirm the MACD turn with price, then exit on the histogram
- 1997Reconstructing a stochastic oscillator, MACD, and a triple-smoothed oscillator
- 1997Moving-average windows before crossovers and MACD
- 1999Second-stage MACD on relative-strength inputs
- 1999Constructing MACD from exponential-average spreads for crossover and divergence
- 1999Coding candlesticks into numeric indicators
- 2001Second-low confirmation with a percentage oscillator and money-flow filter
- 2001Constructing MACD from exponential average spreads and a signal line
- 2002Separate bounded and trend-following oscillator rules
- 2002Sort the regime before assigning MACD and stochastic jobs
- 2002Building classic divergence filters from RSI and MACD
- 2002Weekly highs and lows as trend gates
- 2002Constructing channel-normalized Fisher reversal signals
- 2002Affine-price and the Fisher transform as a constructed companion to MACD
- 2003Regularized EMA construction with a MACD line and a thrust oscillator
- 2003Curvature-penalized exponential averages versus MACD
- 2003MACD, moving averages, and a trend filter as one timing system
- 2003Fractional MACD and linear-regression reversal construction
- 2004Weekly MACD-histogram timing of bear-market rallies
- 2004Candlestick triggers filtered by MACD divergence
- 2004Staging energy-complex tops with trendline, breakout, and MACD
- 2005Selling climax holds versus fails
- 2006Treat a sideways Wave as permission before a breakout
- 2007MACD with a Stochastic oscillator for spotting trend reversals
- 2007Rebuilding an S&P 500 fifth-wave count after a broken target
- 2007Constructing MACD, RSI, and stochastic confirmation for futures
- 2007MACD histogram divergence needs a confirming close
- 2007Write the plan as a stack: ratio, boundary, then oscillators
- 2008MACD divergence and Stochastic oscillator confirmation on lumber futures
- 2008Assign confirmation, timing, and a stop before a currency pair is tested
- 2008Confirm the ten-bagger launch path before the MACD exit
- 2008Reading the offloaded evidence file
- 2008A Leader companion for MACD direction warnings
- 2008Relative strength exits with MACD averages and RSI
- 2008Assign one job per indicator in a three-screens rule set
- 2008Sequencing RSI, MACD, and average crossovers
- 2010Constructing the Schaff Trend Cycle from MACD and a dominant-cycle window
- 2010Schaff Trend Cycle as a MACD and Stochastic oscillator combination
- 2010Combining Relative Strength Index, the stochastic oscillator, and MACD as slope filters
- 2010Short-term wave and ratio clues without direction calls
- 2010A precise pullback entry and an unplanned profit-protection exit
- 2010Filtering MACD false signals with trendline breaks
- 2011Vendor feeds as an input variable in a MACD evaluation
- 2012Out-of-the-money versus in-the-money option sensitivity to implied volatility
- 2012MACD window tuning as hold-time control
- 2012Combining a moving-average crossover with MACD and support-resistance
- 2012Testing a published MACD entry with a histogram and signal-line agreement filter
- 2012Treat sample systems as a lab before live rules
- 2013Constructing moving averages and MACD from one price series
- 2013The next-bar price that forces a MACD signal-line cross
- 2013Constructing next-bar MACD reversal prices
- 2013Constructing inverted MACD reversal prices
- 2014Shared-filter combinations of the stochastic oscillator, MACD, and RSI
- 2014Square-root lookbacks for combined MACD and RSI
- 2015Audit open interest and trend before trusting oscillator crossovers
- 2016MACD without a signal line, confirmed by moving-average trend filters
- 2016Use RSI, MACD, and a moving average as a market-health consensus
- 2016MACD line versus histogram is a display problem first
- 2017Weekly and daily MACD on a single daily chart
- 2017Weekly and daily MACD as a stacked momentum filter
- 2017Nested weekly and daily MACD from paired EMA spreads
- 2018Weekly and daily PPO scale versus MACD, with bounded RSI and stochastic readings
- 2018Constructing a weekly and daily percentage price oscillator
- 2020Constructing Wyckoff tape reading with MACD, moving-average, and RSI filters