2001issue C021-7
Second-low confirmation with a percentage oscillator and money-flow filter
Traditional double-bottom completion waits for a push through the intervening reaction high, so entry arrives only after price is already well above the tested support. The archive workflow treats a second support test as confirmed only when a scaled percentage oscillator, complementary money flow, and a short-term reversal all fire before that neckline break.
- Traditional completion of a double bottom is a push through the intervening reaction high after two roughly equal lows, which delays entry until price is already well above the tested support.
- Pair a close-based percentage oscillator with a volume-based money-flow measure so the construction does not stack two close-only momentum tools that describe the same information.
- Treat second-low confirmation as complete only after a positive oscillator divergence is validated by a cross above the 9-period trigger, typically while the oscillator is still negative.
- Use a one- to two-day reversal at the second low as the timing catalyst after the oscillator and money-flow filters are in place.
The delay inside a traditional double bottom
Traditional double-bottom completion is defined as a push through the intervening reaction high after two roughly equal lows. That definition delays entry until price is already well above the tested support.
Waiting for that neckline confirmation can force a stop either tight enough to invite a whipsaw or so near the prior low that the reward-to-risk geometry deteriorates.
DJIA daily double bottom, June–December 1998
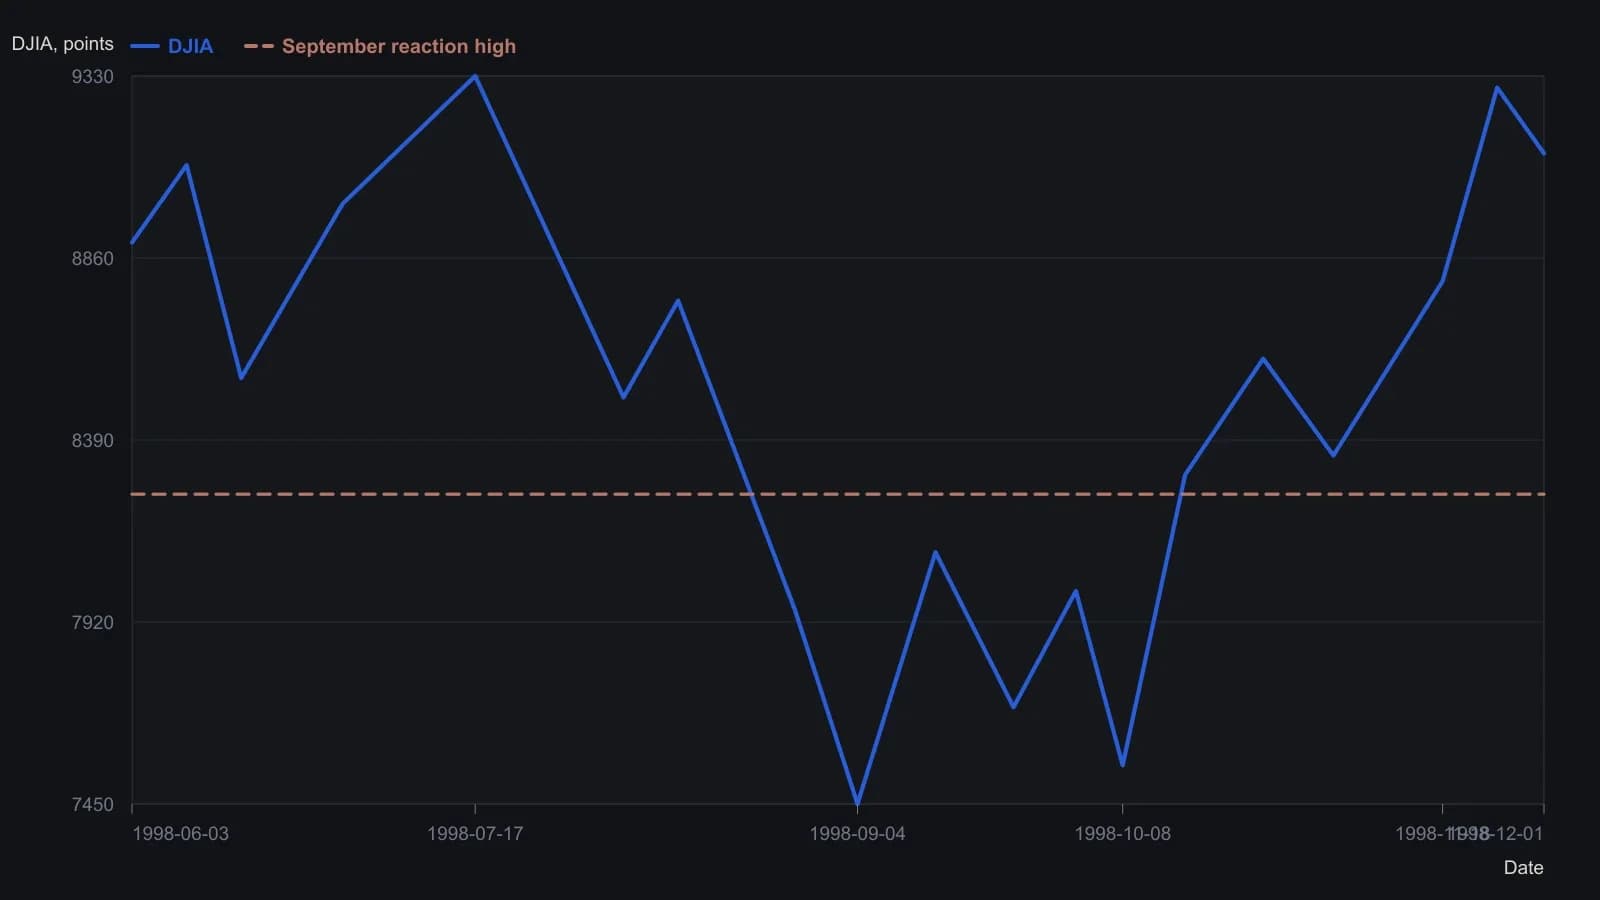
Price marks are rounded to the nearest 50 index points, matching the 500-point grid on the raster. The threshold is the orange resistance line drawn on the source at the September reaction high. The printed 1 December session was open 9116.55, high 9141.27, low 8987.82, close 9133.54. PPO(12,26,9) and CMF(15) appear on the same figure but use different units and are not plotted here.
A complementary oscillator and money-flow pair
The construction pairs a close-based percentage oscillator with a volume-based money-flow measure specifically to avoid stacking two close-only momentum tools that describe the same information. Multicolinearity, in this usage, is that error of stacking indicators that share the same input and describe the same price change.
How the percentage oscillator is built
The percentage oscillator uses 12- and 26-period exponential averages and a 9-period exponential trigger, the same common MACD window, to mark momentum changes over about two to five weeks. Those paired short and long exponential averages set the oscillator sign and define that two-to-five-week momentum window.
Unlike absolute MACD, the oscillator scales the short-minus-long average difference by the short average so the same construction can be compared across different price levels and longer histories. In this workflow the oscillator is a momentum confirmation filter rather than a standalone entry.
Spreadsheet construction seeds simple averages, then recurses each exponential average with factor 2/(N+1). The oscillator is formed as (12-EMA - 26-EMA)/12-EMA, and that series is smoothed with a 9-period exponential trigger. The same recursive weighting is used for the 12-, 26-, and 9-period averages and for the trigger line.
What completes a second-low confirmation
A second-low confirmation is treated as complete only after a positive oscillator divergence is validated by a cross above the 9-period trigger, typically while the oscillator is still negative. Positive divergence here means a second decline that is weaker on the oscillator than on price. That weaker reading is not treated as confirmation until the trigger cross occurs.
Buying pressure at the second low
Money flow is computed from close location in the high-low range times volume over 15 periods so buying pressure can stay positive even on a down close. A reading above +10% is the preferred condition near the second low.
The 15-period money-flow window is chosen to stay near the oscillator's 12-period short average while covering three full weeks rather than a 10-period span judged too short.
A short-term reversal as the timing catalyst
A one- to two-day reversal at the second low is required as the timing catalyst after the oscillator and money-flow filters. The accepted forms are engulfing, hammer, morning star, piercing, outside reversal, or breakaway gap.
All readings on this track · 80 readings
- 1988Rebuild MACD-Mo and MACD-H before treating them as signals
- 1989Four-span MACD lookbacks as perishable parameters
- 1989Weekly then daily MACD confirmation on individual stocks
- 1991Regime-gated MACD and stochastic rules inside a checklist
- 1991Constructing MACD signal lines and divergence tests
- 1991MACD parameter order and cycle phase lag
- 1992Lengthened bond MACD as an equity regime filter
- 1992Long-horizon MACD construction from paired exponential averages
- 1993Constructing a signed ten-point trend filter
- 1994Constructing lag-reduced double exponential averages for MACD
- 1994Seeding DEMA2 filters to build a MACD signal
- 1994Constructing MACD from lag-reduced exponential averages
- 1994TEMA1 from nested exponential averages, then a two-horizon MACD
- 1994Constructing entry and exit on a relative-strength MACD
- 1994Constructing a relative-strength MACD crossover spreadsheet
- 1995Consensus presignal filters for Relative Strength Index, MACD and the Stochastic oscillator
- 1997Confirm the MACD turn with price, then exit on the histogram
- 1997Reconstructing a stochastic oscillator, MACD, and a triple-smoothed oscillator
- 1997Moving-average windows before crossovers and MACD
- 1999Second-stage MACD on relative-strength inputs
- 1999Constructing MACD from exponential-average spreads for crossover and divergence
- 1999Coding candlesticks into numeric indicators
- 2001Second-low confirmation with a percentage oscillator and money-flow filter
- 2001Constructing MACD from exponential average spreads and a signal line
- 2002Separate bounded and trend-following oscillator rules
- 2002Sort the regime before assigning MACD and stochastic jobs
- 2002Building classic divergence filters from RSI and MACD
- 2002Weekly highs and lows as trend gates
- 2002Constructing channel-normalized Fisher reversal signals
- 2002Affine-price and the Fisher transform as a constructed companion to MACD
- 2003Regularized EMA construction with a MACD line and a thrust oscillator
- 2003Curvature-penalized exponential averages versus MACD
- 2003MACD, moving averages, and a trend filter as one timing system
- 2003Fractional MACD and linear-regression reversal construction
- 2004Weekly MACD-histogram timing of bear-market rallies
- 2004Candlestick triggers filtered by MACD divergence
- 2004Staging energy-complex tops with trendline, breakout, and MACD
- 2005Selling climax holds versus fails
- 2006Treat a sideways Wave as permission before a breakout
- 2007MACD with a Stochastic oscillator for spotting trend reversals
- 2007Rebuilding an S&P 500 fifth-wave count after a broken target
- 2007Constructing MACD, RSI, and stochastic confirmation for futures
- 2007MACD histogram divergence needs a confirming close
- 2007Write the plan as a stack: ratio, boundary, then oscillators
- 2008MACD divergence and Stochastic oscillator confirmation on lumber futures
- 2008Assign confirmation, timing, and a stop before a currency pair is tested
- 2008Confirm the ten-bagger launch path before the MACD exit
- 2008Reading the offloaded evidence file
- 2008A Leader companion for MACD direction warnings
- 2008Relative strength exits with MACD averages and RSI
- 2008Assign one job per indicator in a three-screens rule set
- 2008Sequencing RSI, MACD, and average crossovers
- 2010Constructing the Schaff Trend Cycle from MACD and a dominant-cycle window
- 2010Schaff Trend Cycle as a MACD and Stochastic oscillator combination
- 2010Combining Relative Strength Index, the stochastic oscillator, and MACD as slope filters
- 2010Short-term wave and ratio clues without direction calls
- 2010A precise pullback entry and an unplanned profit-protection exit
- 2010Filtering MACD false signals with trendline breaks
- 2011Vendor feeds as an input variable in a MACD evaluation
- 2012Out-of-the-money versus in-the-money option sensitivity to implied volatility
- 2012MACD window tuning as hold-time control
- 2012Combining a moving-average crossover with MACD and support-resistance
- 2012Testing a published MACD entry with a histogram and signal-line agreement filter
- 2012Treat sample systems as a lab before live rules
- 2013Constructing moving averages and MACD from one price series
- 2013The next-bar price that forces a MACD signal-line cross
- 2013Constructing next-bar MACD reversal prices
- 2013Constructing inverted MACD reversal prices
- 2014Shared-filter combinations of the stochastic oscillator, MACD, and RSI
- 2014Square-root lookbacks for combined MACD and RSI
- 2015Audit open interest and trend before trusting oscillator crossovers
- 2016MACD without a signal line, confirmed by moving-average trend filters
- 2016Use RSI, MACD, and a moving average as a market-health consensus
- 2016MACD line versus histogram is a display problem first
- 2017Weekly and daily MACD on a single daily chart
- 2017Weekly and daily MACD as a stacked momentum filter
- 2017Nested weekly and daily MACD from paired EMA spreads
- 2018Weekly and daily PPO scale versus MACD, with bounded RSI and stochastic readings
- 2018Constructing a weekly and daily percentage price oscillator
- 2020Constructing Wyckoff tape reading with MACD, moving-average, and RSI filters