1994issue C111-8
Constructing entry and exit on a relative-strength MACD
A relative-strength ratio, one security close divided by a benchmark close, replaces raw price as the MACD input. Specified pairings then use polarity, a trigger-line cross, and in one case a one-point trailing stop as bar-by-bar entry and exit rules.
- A relative-strength ratio is formed by dividing a security close by a benchmark close and is used as the series on which MACD is calculated.
- One specified ratio MACD uses 12- and 26-period averages, with a 9-period average of the MACD as the trigger line.
- Three pairings buy and sell from polarity against zero and the signal average, from the sign of a ratio MACD histogram, or from a next-open trigger-line rule.
- The histogram pairing adds a one-point trailing stop as a separate exit, and weekly compression applies the same MACD and scan rules to weekly bars.
How the relative-strength ratio is formed
A relative-strength ratio is formed by dividing a security close by a benchmark close. That constructed series is then used as the input on which MACD is calculated, in place of raw price.
How the ratio MACD and trigger line are specified
One specified MACD on that ratio uses 12- and 26-period averages. A 9-period average of the MACD is the trigger line. The trigger line is the signal average of the ratio MACD, used to define a cross and to confirm polarity.
A database filter can keep only cases in which the ratio MACD crosses from below its trigger line to above it.
How entry and exit are paired
One pairing buys on the close when the ratio MACD is above both zero and its signal average, and sells on the close when the ratio MACD is below both zero and its signal average.
Another pairing buys when a histogram of ratio MACD minus its signal is above zero and sells when that histogram is below zero. The histogram pairing also specifies a one-point trailing stop as an additional exit. That trailing stop follows price by a fixed distance and can force an exit independently of the MACD rules.
A third pairing buys at the next open when the ratio MACD is above its trigger line and above zero, and exits a long at the next open when the ratio MACD is below the trigger line.
Each pairing is a rule-based entry. The stated buy, sell, or exit condition is applied the same way on every bar.
Weekly compression and scaling
Daily relative-strength charts can be compressed to weekly bars before the same MACD and scan rules are applied. Scaling the ratio by 10 is stated as a viewing convenience that does not change the MACD.
GM relative-strength MACD versus its trigger, 1993
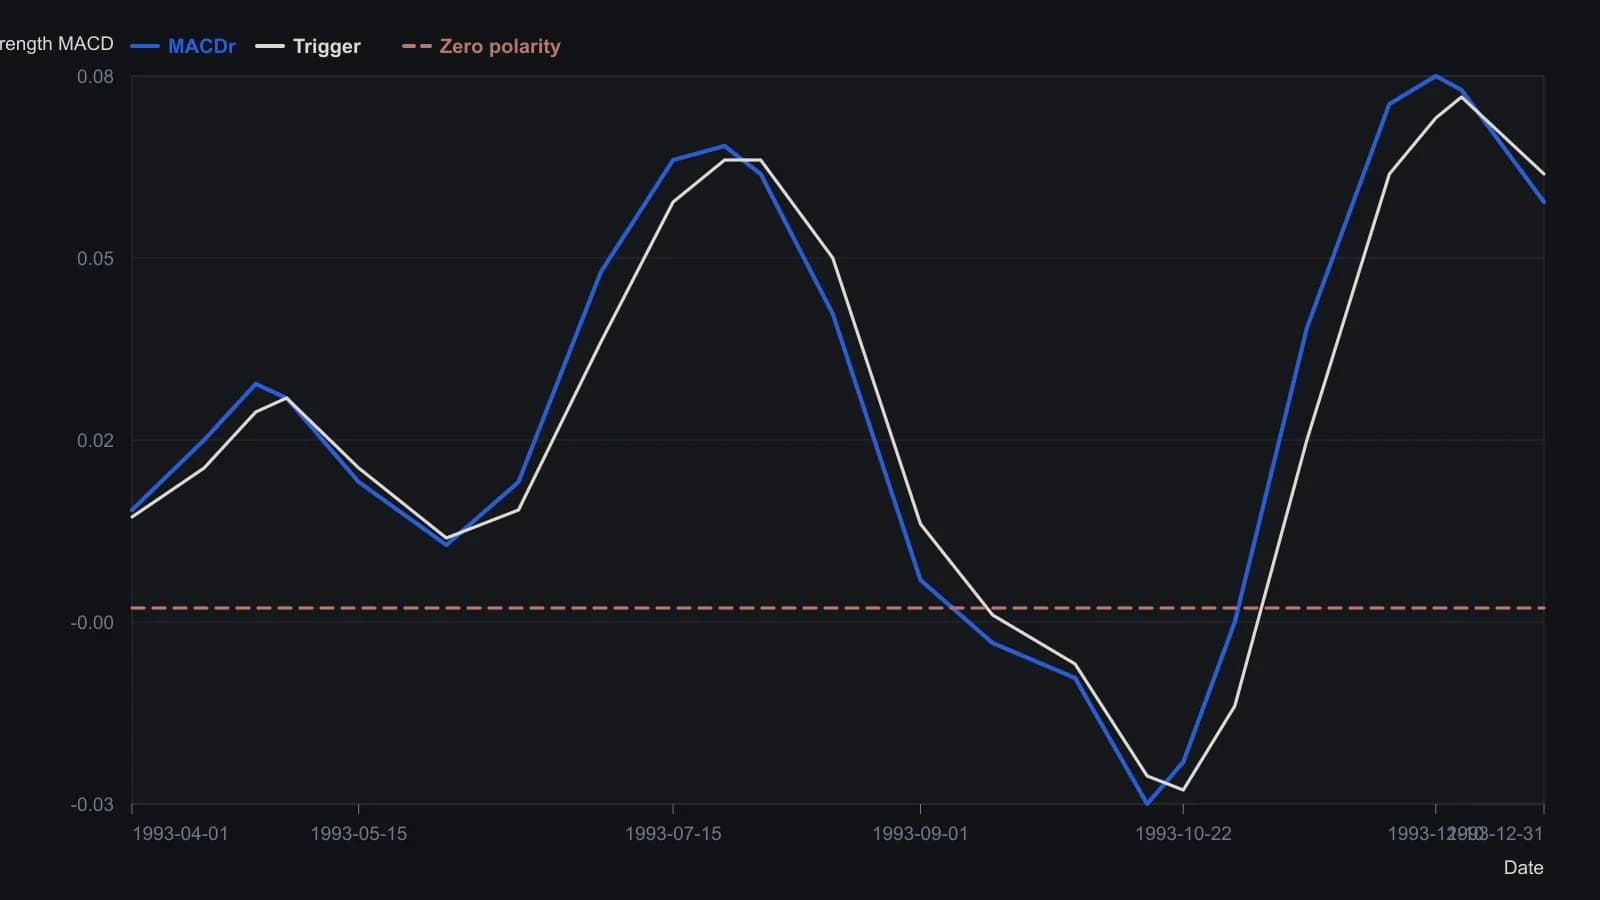
Readings are approximate from the raster; the source did not tabulate the series. Behold! built MACDr as the 22-period EMA of (GM close / NYSE close)×10 minus the 44-period EMA, with a 9-period EMA trigger. The long rule required MACDr above both the trigger and zero; the exit was a trigger cross down.
All readings on this track · 80 readings
- 1988Rebuild MACD-Mo and MACD-H before treating them as signals
- 1989Four-span MACD lookbacks as perishable parameters
- 1989Weekly then daily MACD confirmation on individual stocks
- 1991Regime-gated MACD and stochastic rules inside a checklist
- 1991Constructing MACD signal lines and divergence tests
- 1991MACD parameter order and cycle phase lag
- 1992Lengthened bond MACD as an equity regime filter
- 1992Long-horizon MACD construction from paired exponential averages
- 1993Constructing a signed ten-point trend filter
- 1994Constructing lag-reduced double exponential averages for MACD
- 1994Seeding DEMA2 filters to build a MACD signal
- 1994Constructing MACD from lag-reduced exponential averages
- 1994TEMA1 from nested exponential averages, then a two-horizon MACD
- 1994Constructing entry and exit on a relative-strength MACD
- 1994Constructing a relative-strength MACD crossover spreadsheet
- 1995Consensus presignal filters for Relative Strength Index, MACD and the Stochastic oscillator
- 1997Confirm the MACD turn with price, then exit on the histogram
- 1997Reconstructing a stochastic oscillator, MACD, and a triple-smoothed oscillator
- 1997Moving-average windows before crossovers and MACD
- 1999Second-stage MACD on relative-strength inputs
- 1999Constructing MACD from exponential-average spreads for crossover and divergence
- 1999Coding candlesticks into numeric indicators
- 2001Second-low confirmation with a percentage oscillator and money-flow filter
- 2001Constructing MACD from exponential average spreads and a signal line
- 2002Separate bounded and trend-following oscillator rules
- 2002Sort the regime before assigning MACD and stochastic jobs
- 2002Building classic divergence filters from RSI and MACD
- 2002Weekly highs and lows as trend gates
- 2002Constructing channel-normalized Fisher reversal signals
- 2002Affine-price and the Fisher transform as a constructed companion to MACD
- 2003Regularized EMA construction with a MACD line and a thrust oscillator
- 2003Curvature-penalized exponential averages versus MACD
- 2003MACD, moving averages, and a trend filter as one timing system
- 2003Fractional MACD and linear-regression reversal construction
- 2004Weekly MACD-histogram timing of bear-market rallies
- 2004Candlestick triggers filtered by MACD divergence
- 2004Staging energy-complex tops with trendline, breakout, and MACD
- 2005Selling climax holds versus fails
- 2006Treat a sideways Wave as permission before a breakout
- 2007MACD with a Stochastic oscillator for spotting trend reversals
- 2007Rebuilding an S&P 500 fifth-wave count after a broken target
- 2007Constructing MACD, RSI, and stochastic confirmation for futures
- 2007MACD histogram divergence needs a confirming close
- 2007Write the plan as a stack: ratio, boundary, then oscillators
- 2008MACD divergence and Stochastic oscillator confirmation on lumber futures
- 2008Assign confirmation, timing, and a stop before a currency pair is tested
- 2008Confirm the ten-bagger launch path before the MACD exit
- 2008Reading the offloaded evidence file
- 2008A Leader companion for MACD direction warnings
- 2008Relative strength exits with MACD averages and RSI
- 2008Assign one job per indicator in a three-screens rule set
- 2008Sequencing RSI, MACD, and average crossovers
- 2010Constructing the Schaff Trend Cycle from MACD and a dominant-cycle window
- 2010Schaff Trend Cycle as a MACD and Stochastic oscillator combination
- 2010Combining Relative Strength Index, the stochastic oscillator, and MACD as slope filters
- 2010Short-term wave and ratio clues without direction calls
- 2010A precise pullback entry and an unplanned profit-protection exit
- 2010Filtering MACD false signals with trendline breaks
- 2011Vendor feeds as an input variable in a MACD evaluation
- 2012Out-of-the-money versus in-the-money option sensitivity to implied volatility
- 2012MACD window tuning as hold-time control
- 2012Combining a moving-average crossover with MACD and support-resistance
- 2012Testing a published MACD entry with a histogram and signal-line agreement filter
- 2012Treat sample systems as a lab before live rules
- 2013Constructing moving averages and MACD from one price series
- 2013The next-bar price that forces a MACD signal-line cross
- 2013Constructing next-bar MACD reversal prices
- 2013Constructing inverted MACD reversal prices
- 2014Shared-filter combinations of the stochastic oscillator, MACD, and RSI
- 2014Square-root lookbacks for combined MACD and RSI
- 2015Audit open interest and trend before trusting oscillator crossovers
- 2016MACD without a signal line, confirmed by moving-average trend filters
- 2016Use RSI, MACD, and a moving average as a market-health consensus
- 2016MACD line versus histogram is a display problem first
- 2017Weekly and daily MACD on a single daily chart
- 2017Weekly and daily MACD as a stacked momentum filter
- 2017Nested weekly and daily MACD from paired EMA spreads
- 2018Weekly and daily PPO scale versus MACD, with bounded RSI and stochastic readings
- 2018Constructing a weekly and daily percentage price oscillator
- 2020Constructing Wyckoff tape reading with MACD, moving-average, and RSI filters