2011issue C0242-47
Vendor feeds as an input variable in a MACD evaluation
A fixed, unoptimized MACD reversal rule on one Russell 2000 sample can look consistent across charts and still change its signed outcome when the same OHLC bars are sourced from different vendor feeds.
- Vendor-to-vendor OHLC disagreements on a mid-2005 to mid-2010 Russell 2000 sample can look like hundredths on a single bar and still fail to cancel when summed.
- A 0.01 per-bar discrepancy over 1,257 trading days equals 12.57 index points, or 1,257 currency units at 100 units per Russell 2000 point on a single contract path.
- Equal-looking charts can rest on different open definitions and rounding. The originating exchange print supplied only closes for part of the window and at finer decimal precision than typical vendor files.
- The exercise held one unoptimized MACD specification and a market-order fill to expose data-source effects. Commercial vendor series clustered on similarly negative outcomes, while the exchange series was the outlier and the only one near a non-negative result.
The MACD rule was held fixed
A MACD oscillator is used here as a fixed, unoptimized reversal rule that turns a repeatable chart condition into a testable long-or-short hypothesis. The historical exercise held one unoptimized MACD specification on one Russell 2000 sample to expose data-source effects. It was not designed to prove that a MACD reversal rule works.
The evaluation used a market-order fill, an at-market entry, so the comparison isolates data differences rather than order-type effects.
OHLC disagreements that look like hundredths
A five-year Russell 2000 sample from mid-2005 to mid-2010 can show vendor-to-vendor OHLC disagreements that look like hundredths on a single bar but do not cancel when summed. That pattern is accumulated tick error: tiny per-bar differences that look negligible on a single day but add into a material point total when summed across a multi-year sample.
In one two-vendor summation, closes were 52 points lower, opens 40 points higher, highs 65 points lower, and lows 48 points higher, with the signed gaps alternating rather than lining up in one direction. Range invariance, the idea that a day's high minus low might stay stable even when open and close prints disagree, is a check, not an assumption.
A 0.01 per-bar discrepancy accumulated over 1,257 trading days equals 12.57 index points. At 100 currency units per Russell 2000 point that is 1,257 units on a single contract path.
Two vendors can show long stretches of identical zeros in a difference sheet and still leave a non-zero close total, with most of one close gap concentrated on a single session.
Opens, rounding, and the exchange print
The originating index series supplied only closes for part of the window, to six decimal places, while vendor files typically carried two decimal places. That exchange print is a reference close, available at finer decimal precision than typical vendor files.
Vendors may not share the same definition of the open. Some record the first traded print, so equal-looking charts can still rest on different OHLC construction.
Signed outcomes under the same market-order rule
Under that fixed MACD market-order rule, commercial vendor series produced similarly negative outcomes, while the exchange series was the outlier and the only one near a non-negative result.
Across roughly 100 hypothetical trades the vendor-to-vendor P&L gap was only a few currency units, which is smaller than typical live bid-ask and fill variation.
Editorial: the small vendor-to-vendor P&L gap is why a standard oscillator rule can look consistent across commercial charts, even though the exchange series still shows that changing the feed can change the signed outcome.
Russell 2000 daily closes from vendors T, M and G
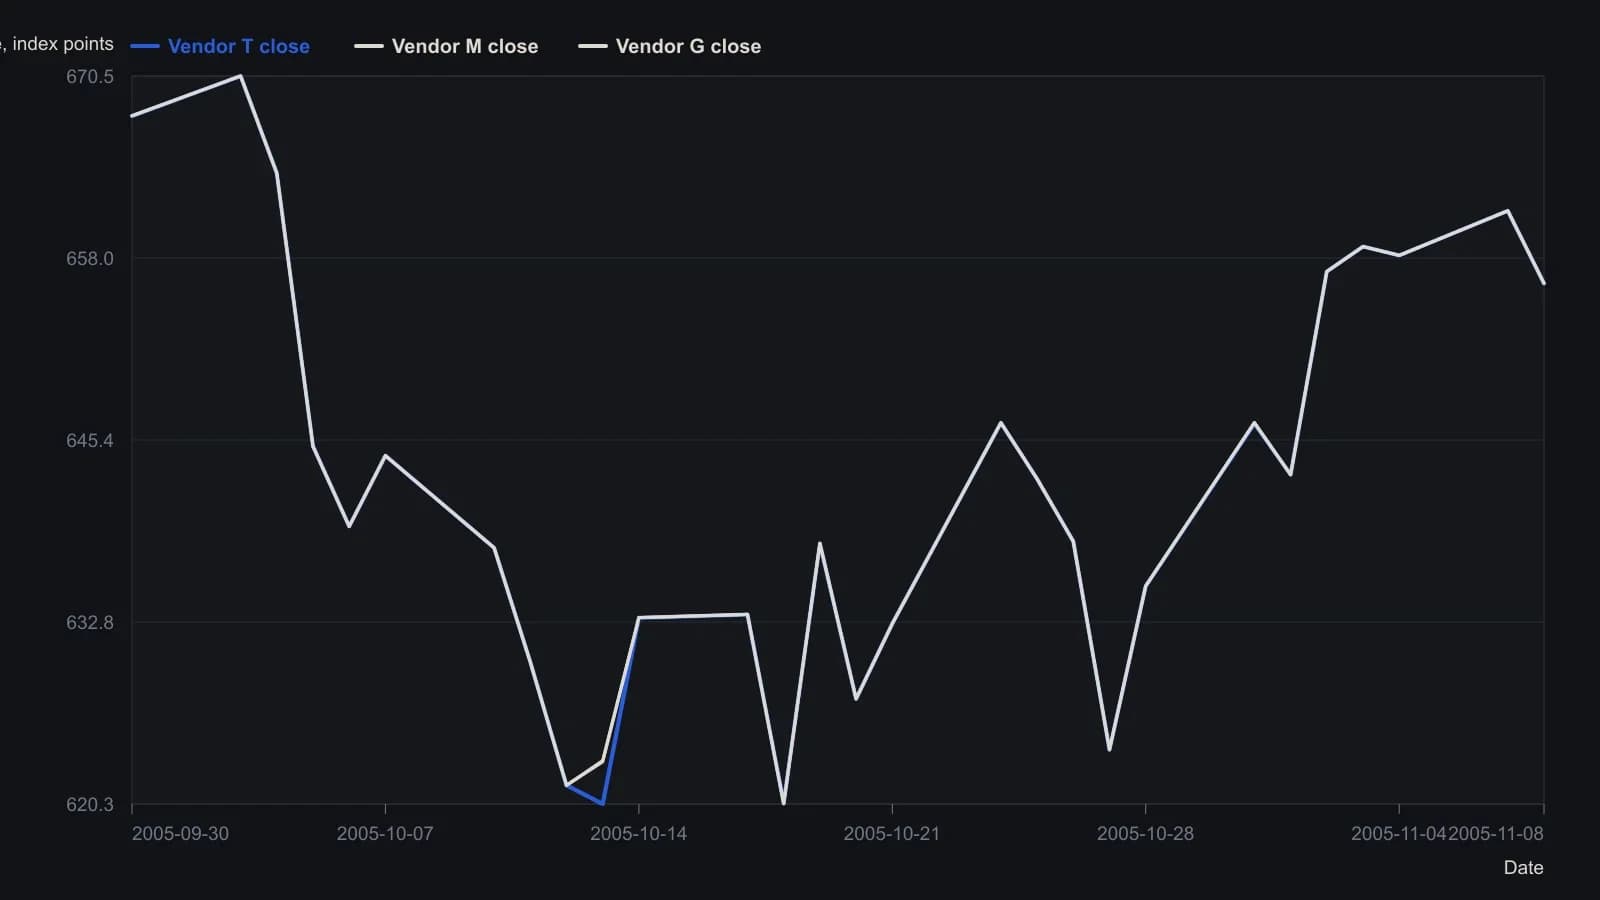
Only the readable opening rows of the sheet are plotted (30 September through 8 November 2005), not the full five-year dump. The last scorched row was omitted. Vendors M and G often carry the prior close into the next open; vendor T prints a distinct session open.
All readings on this track · 80 readings
- 1988Rebuild MACD-Mo and MACD-H before treating them as signals
- 1989Four-span MACD lookbacks as perishable parameters
- 1989Weekly then daily MACD confirmation on individual stocks
- 1991Regime-gated MACD and stochastic rules inside a checklist
- 1991Constructing MACD signal lines and divergence tests
- 1991MACD parameter order and cycle phase lag
- 1992Lengthened bond MACD as an equity regime filter
- 1992Long-horizon MACD construction from paired exponential averages
- 1993Constructing a signed ten-point trend filter
- 1994Constructing lag-reduced double exponential averages for MACD
- 1994Seeding DEMA2 filters to build a MACD signal
- 1994Constructing MACD from lag-reduced exponential averages
- 1994TEMA1 from nested exponential averages, then a two-horizon MACD
- 1994Constructing entry and exit on a relative-strength MACD
- 1994Constructing a relative-strength MACD crossover spreadsheet
- 1995Consensus presignal filters for Relative Strength Index, MACD and the Stochastic oscillator
- 1997Confirm the MACD turn with price, then exit on the histogram
- 1997Reconstructing a stochastic oscillator, MACD, and a triple-smoothed oscillator
- 1997Moving-average windows before crossovers and MACD
- 1999Second-stage MACD on relative-strength inputs
- 1999Constructing MACD from exponential-average spreads for crossover and divergence
- 1999Coding candlesticks into numeric indicators
- 2001Second-low confirmation with a percentage oscillator and money-flow filter
- 2001Constructing MACD from exponential average spreads and a signal line
- 2002Separate bounded and trend-following oscillator rules
- 2002Sort the regime before assigning MACD and stochastic jobs
- 2002Building classic divergence filters from RSI and MACD
- 2002Weekly highs and lows as trend gates
- 2002Constructing channel-normalized Fisher reversal signals
- 2002Affine-price and the Fisher transform as a constructed companion to MACD
- 2003Regularized EMA construction with a MACD line and a thrust oscillator
- 2003Curvature-penalized exponential averages versus MACD
- 2003MACD, moving averages, and a trend filter as one timing system
- 2003Fractional MACD and linear-regression reversal construction
- 2004Weekly MACD-histogram timing of bear-market rallies
- 2004Candlestick triggers filtered by MACD divergence
- 2004Staging energy-complex tops with trendline, breakout, and MACD
- 2005Selling climax holds versus fails
- 2006Treat a sideways Wave as permission before a breakout
- 2007MACD with a Stochastic oscillator for spotting trend reversals
- 2007Rebuilding an S&P 500 fifth-wave count after a broken target
- 2007Constructing MACD, RSI, and stochastic confirmation for futures
- 2007MACD histogram divergence needs a confirming close
- 2007Write the plan as a stack: ratio, boundary, then oscillators
- 2008MACD divergence and Stochastic oscillator confirmation on lumber futures
- 2008Assign confirmation, timing, and a stop before a currency pair is tested
- 2008Confirm the ten-bagger launch path before the MACD exit
- 2008Reading the offloaded evidence file
- 2008A Leader companion for MACD direction warnings
- 2008Relative strength exits with MACD averages and RSI
- 2008Assign one job per indicator in a three-screens rule set
- 2008Sequencing RSI, MACD, and average crossovers
- 2010Constructing the Schaff Trend Cycle from MACD and a dominant-cycle window
- 2010Schaff Trend Cycle as a MACD and Stochastic oscillator combination
- 2010Combining Relative Strength Index, the stochastic oscillator, and MACD as slope filters
- 2010Short-term wave and ratio clues without direction calls
- 2010A precise pullback entry and an unplanned profit-protection exit
- 2010Filtering MACD false signals with trendline breaks
- 2011Vendor feeds as an input variable in a MACD evaluation
- 2012Out-of-the-money versus in-the-money option sensitivity to implied volatility
- 2012MACD window tuning as hold-time control
- 2012Combining a moving-average crossover with MACD and support-resistance
- 2012Testing a published MACD entry with a histogram and signal-line agreement filter
- 2012Treat sample systems as a lab before live rules
- 2013Constructing moving averages and MACD from one price series
- 2013The next-bar price that forces a MACD signal-line cross
- 2013Constructing next-bar MACD reversal prices
- 2013Constructing inverted MACD reversal prices
- 2014Shared-filter combinations of the stochastic oscillator, MACD, and RSI
- 2014Square-root lookbacks for combined MACD and RSI
- 2015Audit open interest and trend before trusting oscillator crossovers
- 2016MACD without a signal line, confirmed by moving-average trend filters
- 2016Use RSI, MACD, and a moving average as a market-health consensus
- 2016MACD line versus histogram is a display problem first
- 2017Weekly and daily MACD on a single daily chart
- 2017Weekly and daily MACD as a stacked momentum filter
- 2017Nested weekly and daily MACD from paired EMA spreads
- 2018Weekly and daily PPO scale versus MACD, with bounded RSI and stochastic readings
- 2018Constructing a weekly and daily percentage price oscillator
- 2020Constructing Wyckoff tape reading with MACD, moving-average, and RSI filters