2002issue C111-3
Constructing channel-normalized Fisher reversal signals
Reversal timing is treated as a construction problem. After testing whether a series lives at the extremes rather than in a bell curve, mid-price is mapped through a bounded channel and a tail-stretching logarithm so a moving-average cross, a MACD overlay, and a relative-strength-index input can each be compared against the same turning-point hypothesis.
- Market prices are described as lacking a Gaussian probability density, contrary to the common modeling story that about 68 percent of samples fall within one standard deviation of the mean.
- In a two-value square-wave sketch each level has a 50 percent occupancy, so a moving-average cross registers a move only after the series has already switched. A sinewave occupancy built from 2000 samples also concentrates near the maxima and minima.
- Channel-normalization rescales mid-price into the open interval from -1 to 1. A Fisher transform then keeps roughly unit gain near the mean and strongly amplifies values near the bounds, turning a cyclic input density into a nearly Gaussian output density.
- Cyclic turns are marked by crossing the transformed series with its one-bar trigger. A ten-times amplified rate of change locates larger swings, a scaled MACD overlay is kept as a rounded and lagging comparison, and the same stretch can follow a relative-strength-index normalization.
Occupancy comes before a crossover
Market prices are described as lacking a Gaussian probability density, contrary to the common modeling story that about 68 percent of samples fall within one standard deviation of the mean. A probability-density-function records the relative frequency with which a price or oscillator occupies each value inside a stated range. The gaussian-assumption says samples cluster in a bell curve around a mean, with most observations near the center rather than at the extremes.
Why a moving-average cross arrives late
In a two-value square-wave sketch each level has a 50 percent occupancy, so a moving-average cross would register a move only after the series had already switched to the opposite value. A moving-average is a lagging location baseline. A simple price cross of that baseline is used here as the default detector that fails when a series spends most of its time at extremes.
A sinewave occupancy built from 2000 samples concentrates near the maxima and minima, producing a cycle density closer to a square wave than to a bell curve.
A bounded mid-price map and a tail stretch
Channel-normalization rescales a mid-price series to the highest and lowest values of a lookback window, then centers and stretches it into the open interval from -1 to 1. The fisher-transform is a logarithmic map applied to a series already confined inside that open interval so values near the bounds are amplified and the output occupancy becomes closer to a bell curve.
The transform is defined as one-half the natural logarithm of (1 + x) divided by (1 - x), with the input x required to stay strictly inside the open interval from -1 to 1. Near the mean the map has roughly unit gain when the absolute input is below 0.5, while values approaching either bound are strongly amplified, turning a cyclic input density into a nearly Gaussian output density.
The working recipe
The working recipe rescales mid-price, computed as high plus low divided by 2, inside an adjustable 10-bar high-low channel, applies an exponential smoother with alpha 0.33, clamps absolute values of 0.99 to 0.999, then adds a one-half one-bar recursion after the logarithm.
Comparison layers on the same hypothesis
The transformed series plotted against its one-bar delay is the crossover construction used to mark cyclic turning points. That delayed series is the one-bar-trigger: the transformed series delayed by one observation and used as a crossover counterpart.
A similarly scaled MACD overlay is introduced as a conventional comparison whose turning points are described as rounded and lagging relative to the tail-stretched series. MACD is a conventional momentum overlay kept on a comparable scale so those rounded, delayed turns can be compared with the tail-stretched reversal series.
Because the channel length is 10 bars, ten times the rate of change of the transformed series is crossed with the series itself as a second construction for locating major turns. That period-matched multiple is the amplified-rate-of-change, crossed back through the series to mark larger swings.
The same logarithmic stretch is also specified after a series is already normalized, including by a relative-strength-index construction, so peak swings become relatively rare events used to mark reversals. The relative-strength-index is a bounded oscillator that already lives on a normalized scale and can receive the same logarithmic stretch used on channel-normalized mid-price.
Editorial: the moving-average cross, the MACD overlay, and the relative-strength-index input are comparison layers that can each be falsified against the same turning-point hypothesis.
US 96H daily closes, August 1995 to March 1996
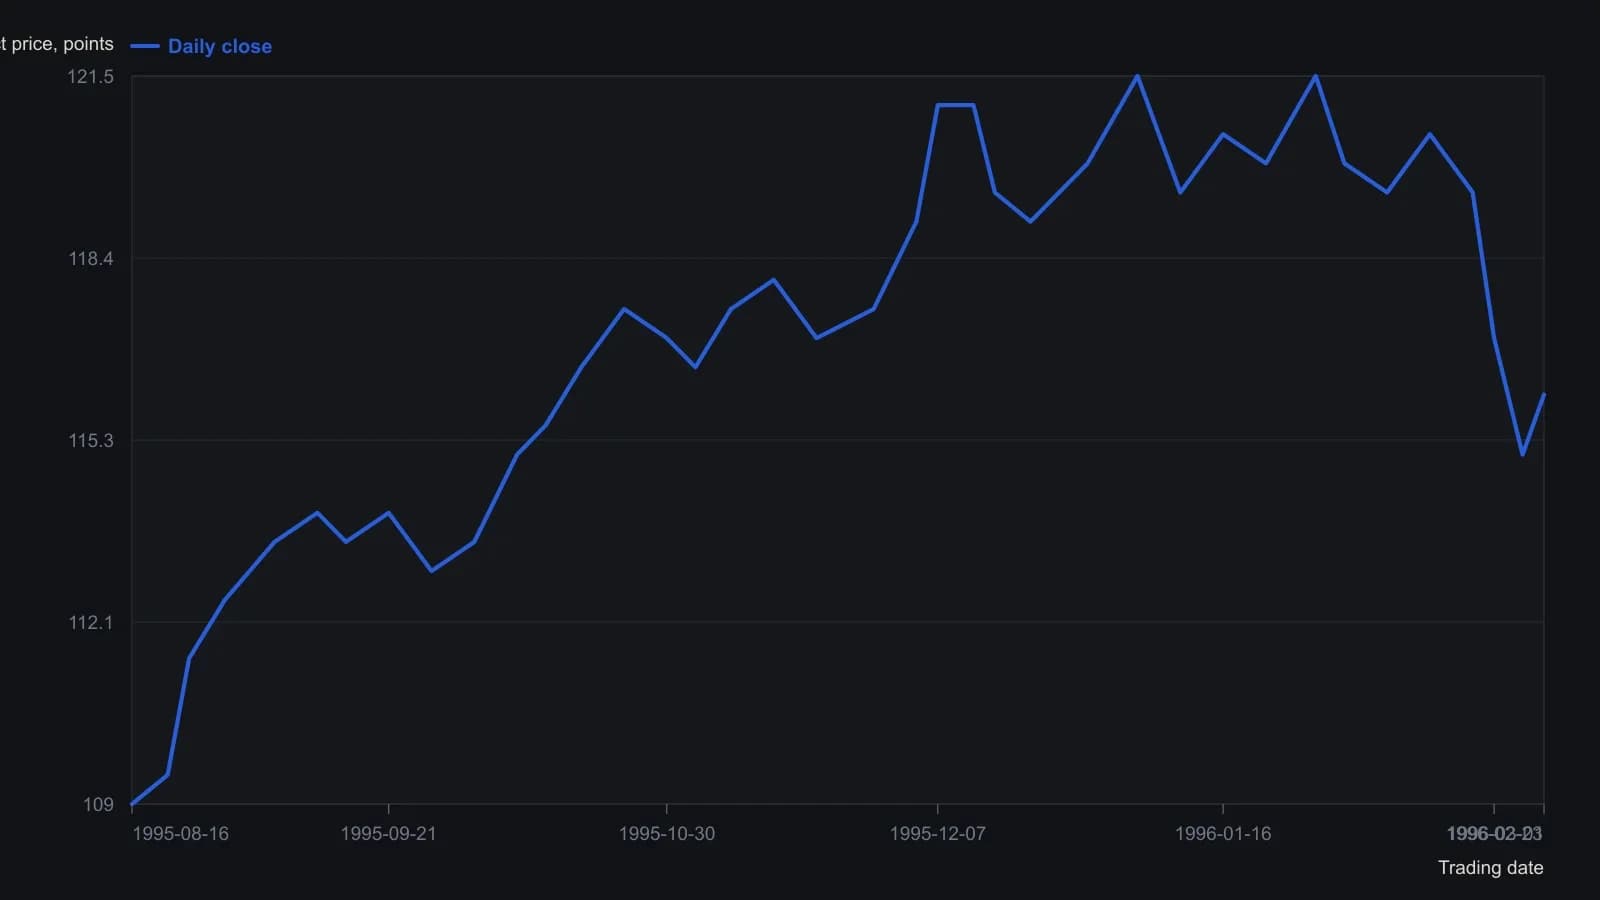
Closes read from the Figure 6 candlesticks to the nearest half-point. Ehlers actually feeds the 10-day high-low channel of (H+L)/2, not the close, into the Fisher transform. Header quote on 1 March 1996: O 114.91, H 116.16, L 114.78, C 116.03. Fisher last prints on this pane are −2.93 and −3.51; the oscillator itself is too faint on the raster to digitize as a second series.
All readings on this track · 80 readings
- 1988Rebuild MACD-Mo and MACD-H before treating them as signals
- 1989Four-span MACD lookbacks as perishable parameters
- 1989Weekly then daily MACD confirmation on individual stocks
- 1991Regime-gated MACD and stochastic rules inside a checklist
- 1991Constructing MACD signal lines and divergence tests
- 1991MACD parameter order and cycle phase lag
- 1992Lengthened bond MACD as an equity regime filter
- 1992Long-horizon MACD construction from paired exponential averages
- 1993Constructing a signed ten-point trend filter
- 1994Constructing lag-reduced double exponential averages for MACD
- 1994Seeding DEMA2 filters to build a MACD signal
- 1994Constructing MACD from lag-reduced exponential averages
- 1994TEMA1 from nested exponential averages, then a two-horizon MACD
- 1994Constructing entry and exit on a relative-strength MACD
- 1994Constructing a relative-strength MACD crossover spreadsheet
- 1995Consensus presignal filters for Relative Strength Index, MACD and the Stochastic oscillator
- 1997Confirm the MACD turn with price, then exit on the histogram
- 1997Reconstructing a stochastic oscillator, MACD, and a triple-smoothed oscillator
- 1997Moving-average windows before crossovers and MACD
- 1999Second-stage MACD on relative-strength inputs
- 1999Constructing MACD from exponential-average spreads for crossover and divergence
- 1999Coding candlesticks into numeric indicators
- 2001Second-low confirmation with a percentage oscillator and money-flow filter
- 2001Constructing MACD from exponential average spreads and a signal line
- 2002Separate bounded and trend-following oscillator rules
- 2002Sort the regime before assigning MACD and stochastic jobs
- 2002Building classic divergence filters from RSI and MACD
- 2002Weekly highs and lows as trend gates
- 2002Constructing channel-normalized Fisher reversal signals
- 2002Affine-price and the Fisher transform as a constructed companion to MACD
- 2003Regularized EMA construction with a MACD line and a thrust oscillator
- 2003Curvature-penalized exponential averages versus MACD
- 2003MACD, moving averages, and a trend filter as one timing system
- 2003Fractional MACD and linear-regression reversal construction
- 2004Weekly MACD-histogram timing of bear-market rallies
- 2004Candlestick triggers filtered by MACD divergence
- 2004Staging energy-complex tops with trendline, breakout, and MACD
- 2005Selling climax holds versus fails
- 2006Treat a sideways Wave as permission before a breakout
- 2007MACD with a Stochastic oscillator for spotting trend reversals
- 2007Rebuilding an S&P 500 fifth-wave count after a broken target
- 2007Constructing MACD, RSI, and stochastic confirmation for futures
- 2007MACD histogram divergence needs a confirming close
- 2007Write the plan as a stack: ratio, boundary, then oscillators
- 2008MACD divergence and Stochastic oscillator confirmation on lumber futures
- 2008Assign confirmation, timing, and a stop before a currency pair is tested
- 2008Confirm the ten-bagger launch path before the MACD exit
- 2008Reading the offloaded evidence file
- 2008A Leader companion for MACD direction warnings
- 2008Relative strength exits with MACD averages and RSI
- 2008Assign one job per indicator in a three-screens rule set
- 2008Sequencing RSI, MACD, and average crossovers
- 2010Constructing the Schaff Trend Cycle from MACD and a dominant-cycle window
- 2010Schaff Trend Cycle as a MACD and Stochastic oscillator combination
- 2010Combining Relative Strength Index, the stochastic oscillator, and MACD as slope filters
- 2010Short-term wave and ratio clues without direction calls
- 2010A precise pullback entry and an unplanned profit-protection exit
- 2010Filtering MACD false signals with trendline breaks
- 2011Vendor feeds as an input variable in a MACD evaluation
- 2012Out-of-the-money versus in-the-money option sensitivity to implied volatility
- 2012MACD window tuning as hold-time control
- 2012Combining a moving-average crossover with MACD and support-resistance
- 2012Testing a published MACD entry with a histogram and signal-line agreement filter
- 2012Treat sample systems as a lab before live rules
- 2013Constructing moving averages and MACD from one price series
- 2013The next-bar price that forces a MACD signal-line cross
- 2013Constructing next-bar MACD reversal prices
- 2013Constructing inverted MACD reversal prices
- 2014Shared-filter combinations of the stochastic oscillator, MACD, and RSI
- 2014Square-root lookbacks for combined MACD and RSI
- 2015Audit open interest and trend before trusting oscillator crossovers
- 2016MACD without a signal line, confirmed by moving-average trend filters
- 2016Use RSI, MACD, and a moving average as a market-health consensus
- 2016MACD line versus histogram is a display problem first
- 2017Weekly and daily MACD on a single daily chart
- 2017Weekly and daily MACD as a stacked momentum filter
- 2017Nested weekly and daily MACD from paired EMA spreads
- 2018Weekly and daily PPO scale versus MACD, with bounded RSI and stochastic readings
- 2018Constructing a weekly and daily percentage price oscillator
- 2020Constructing Wyckoff tape reading with MACD, moving-average, and RSI filters