2007issue C031-6
Anticipating a moving-average crossover before confirmation
A 20-day and 30-day simple moving average pair can be rewritten as a next-bar threshold close, so a moving-average-crossover is visible one day before the averages cross. The archive workflow then keeps only probable cross days and treats a cross prediction as a rule-based-entry only when trend-following conditions already hold.
- A 20-day and 30-day simple moving average pair can be turned into a threshold close that identifies a descending or ascending crossover one day before the averages themselves cross.
- Requiring the next bar’s return to stay inside twice the extreme one-day return from a long lookback rejects unreachable threshold closes and leaves only a small share of bars as probable cross days.
- Across the same 100-stock NASDAQ 100 universe, the prediction series led the confirmed-cross series by one day on individual names and on a composite breadth ticker, and most predictions later confirmed.
- Knowing the prediction at the close of day zero defines an execution window through the next session, but the archive presents that rule-based-entry as a short-horizon trend-following test rather than a congestion trade.
Rewrite the crossover as a threshold close
A moving-average-crossover is a rule that fires when a shorter simple moving average crosses a longer one. In this workflow that cross is the event to anticipate, not the entry itself.
A 20-day and 30-day simple moving average pair can be turned into a next-bar threshold close: the next-session close that would make the shorter and longer simple moving averages meet on the following bar. A cross prediction is a same-day signal that the current close has already crossed that threshold close, which implies a confirmed average cross is expected on the next bar.
Keep only probable cross days
A negative or otherwise unreachable threshold close can be rejected by requiring the next bar’s return to stay inside twice the extreme one-day return observed over a long lookback. That filter leaves only a small share of bars as probable cross days, meaning the implied threshold close still lies inside a realistic next-bar return band so a crossover is possible rather than arithmetically excluded.
On a single-name example using an 800-bar lookback, that realistic-return band implied a next-bar daily-return range of +48% to -26%, and most candles were classified as having no practical chance of a 20/30-day average cross.
A one-day lead on names and breadth
When predicted and confirmed crossovers are counted across the same 100-stock NASDAQ 100 universe, the prediction series leads the confirmed-cross series by one day at the market-breadth level as well as on individual names. A composite breadth ticker is that daily count, across a defined stock universe, of how many names show a predicted or confirmed ascending or descending crossover.
Across the NASDAQ 100 sample, four simple-average pairs produced hundreds to thousands of descending and ascending predictions, with the majority later confirmed and only a small percentage failing in each direction. The 20/30-day pair generated 1772 descending and 1766 ascending predictions, of which 85.79% and 88.09% respectively fell into the leading confirmation bucket reported for that pair. Lengthening the slower average reduced prediction counts, for example to 562 descending and 621 ascending predictions on the 20/100-day pair, while the 50/100-day pair showed the highest leading-confirmation shares at 92.50% descending and 91.76% ascending.
The same test on an indicator
The same threshold-close prediction can be applied after replacing raw close with an indicator series, so a slow and fast moving average of that indicator can be anticipated in the same way as a price-average cross.
CSCO next-bar StochD threshold against the 0–100 band
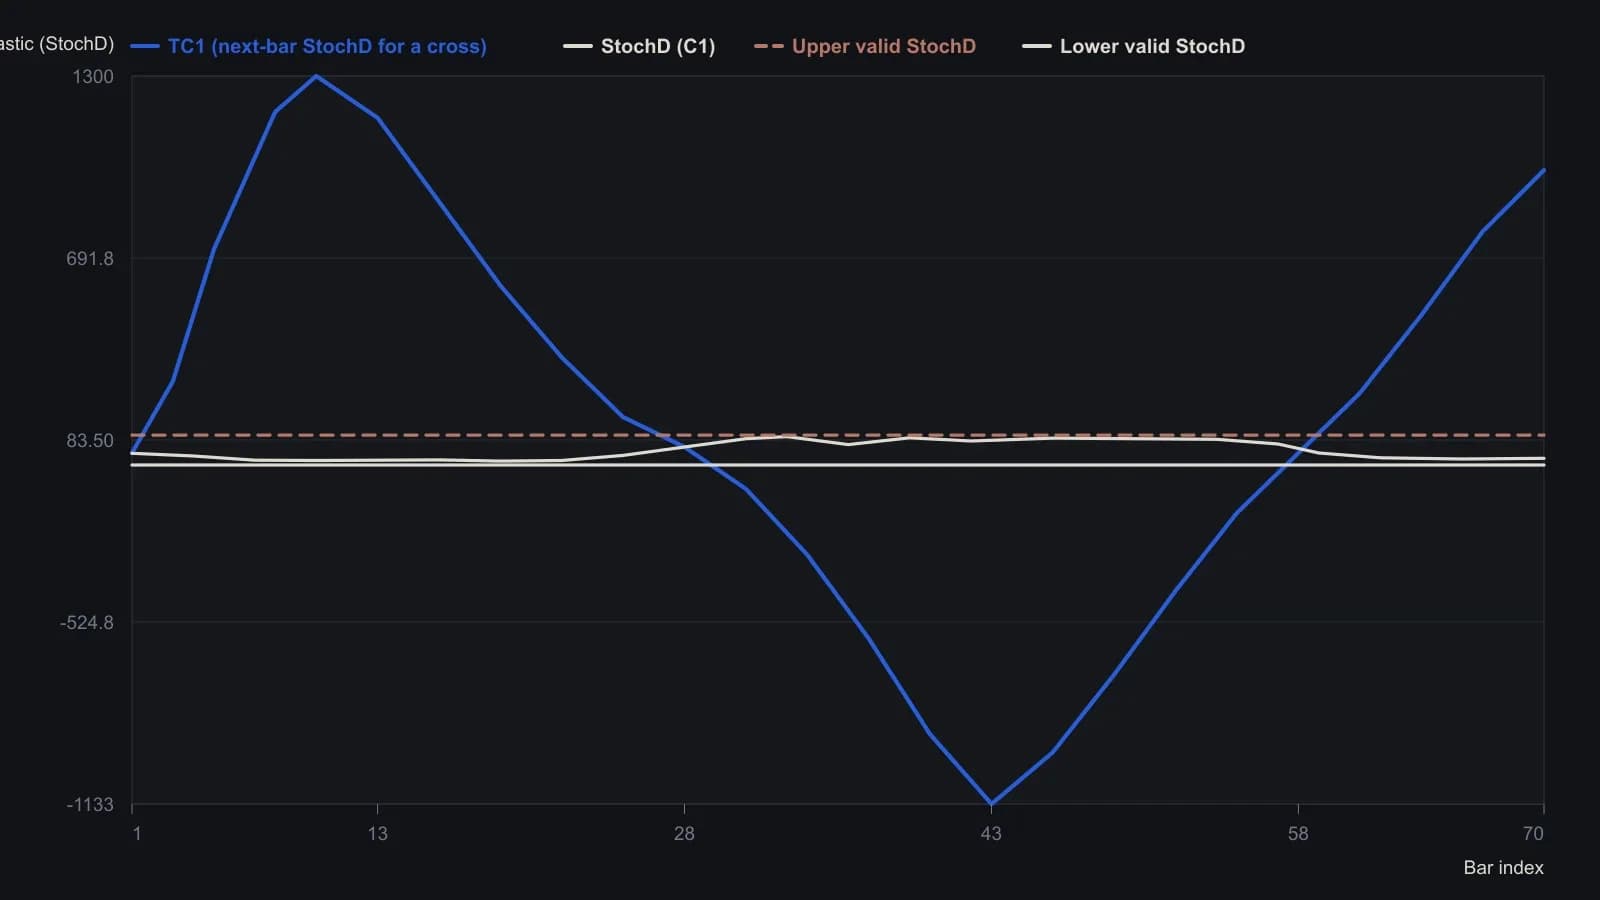
The source replaces price with StochD (C1) inside the same 20/30 SMA threshold-close formula. Because StochD cannot print outside 0–100, any TC1 outside that interval is an impossible cross.
Place the entry only in a persistent trend
Knowing the prediction at the close of day zero creates a defined execution window through the next session’s range and the following open, so a rule-based-entry can be placed before the lagging confirmed cross would otherwise fire. That rule-based-entry is an entry, delay, or abstention decision defined by a closed-form next-day close, a realistic-return filter, and whether the predicted cross is later confirmed.
The procedure is presented as a short-horizon trend-following test. Trend-following here only treats predicted and confirmed crossovers as actionable when price is already moving in a persistent direction, and treats congestion as a reason to stand aside. Predicted crossovers can be traded during persistent trends, including with partial orders, but are not described as effective during congestion.
All readings on this track · 57 readings
- 1988Constructing moving averages: weights, smoothing and crossovers
- 1988Constructing breadth and average trend states
- 1989Evaluating an always-in-the-market moving-average crossover
- 1989Constructing symmetric market-breadth ratio accumulators
- 1989Objective crossover tests of Fibonacci wave ratios
- 1990Volume-adjusted moving average construction
- 1991Constructing a mechanical crossover on a synthetic price series
- 1991A two-speed breadth reading for intermediate market direction
- 1992A Deutschemark yield map with dual-average and relative-strength timing
- 1992Confirming currency-fund trends with a crossover and a filter
- 1992A moving-average slope filter for crossover signals
- 1992Occupancy and split-sample tests for average crossovers
- 1994Gold-mining seasonality and bond-fund duration switching
- 1994Price oscillator from two moving averages
- 1995Explicit exponential weights and binary entry filters
- 1996Currency futures crossover with slope, bond filter, and stop
- 1996Two-market average crossover entry with a fixed stop
- 1997Construction of a filtered three-average crossover
- 1998Two-group exponential average compression as a trend filter
- 1998Constructing r-squared trend filters with dual lookbacks
- 1998Moving-average length is a habit, not a secret
- 1999Solving the close that triggers a moving-average crossover
- 2000Kagi yang and yin control versus crossover noise
- 2000Constructing simple moving average crossover filters
- 2000Building a vertical-horizontal filter to gate trend signals
- 2000Two-average crossover as a check on trend following
- 2003Stacked exponential-average retracement entries and extreme stops
- 2003Evaluating oscillator thresholds against optimized crossovers
- 2004Constructing a semicycle trend-quality filter
- 2004Commodity subgroups labeled by crossover, support, or convergence
- 2004Full-window evaluation of crossover trend systems
- 2004Two-average trend filters as a classroom critique of indicator stacking
- 2005Three-layer confirmation from a moving-average cross, candles, and Q-stick
- 2005Charting put prices beside an equity breakdown
- 2005Range-gated moving-average crossover construction
- 2007Anticipating a simple-average crossover with a threshold-close
- 2007Anticipating moving-average crossovers one bar ahead
- 2007Lead-series moving-average crossovers with a stochastic and relative strength index
- 2007Next-bar SMA crossover hypotheses from theoretical crossing values
- 2007Anticipating a moving-average crossover before confirmation
- 2007A three-horizon moving-average stack as a construction problem
- 2007Confirming trend with regression slope and r-squared
- 2008Constructing a multi-timeframe smoothed crossover
- 2008Best-day clusters versus trend filters
- 2008Allied markets as a confirmation gate for crossover and breakout signals
- 2008Weekly exponential-average crossover as a mechanical trend case study
- 2010Evaluating a 200-day crossover as long, short, and stand-aside rules
- 2010Read a 10-and-40 trend on two neighboring time frames
- 2012Sampling unit as a first-class parameter on dual simple moving averages
- 2012Constructing index-ETF entries from volatility-index persistence
- 2013Moving-average baselines versus crossover signals
- 2013Constructing a typical-price and heikin-ashi crossover as one mechanical procedure
- 2016A three-gate checklist for longs after a sharp drop
- 2016Weekly inflation-ratio crossover for commodity regimes
- 2017Normalized Laguerre zero-axis warning as a two-marker construction
- 2019Range-weighted construction of an adaptive exponential moving average
- 2020Construct a second-pullback entry after a moving-average crossover