1992issue C081-10
Occupancy and split-sample tests for average crossovers
A 24-year weekly history of a major industrial average was scored in two adjacent 12-year windows by holding each average-crossover stance until the opposite cross. Editorial reading: treat the crossover as a multi-week regime label, and accept the filter as an evaluated baseline only if those two windows agree.
- Regime occupancy scores every week spent in a bullish or bearish stance after a moving-average-crossover, not only the week the lines meet.
- Each occupied week was a directional hit when later price rose after a short-over-long stance, or fell after a short-under-long stance, at 1, 5, 13, 26, and 52 weeks ahead.
- Close versus the 4-week exponential average was near even money for the following week in both 12-year windows.
- Editorial reading: the 13-versus-26 pairing had the best mean directional score on the nearer horizons, but the two split-sample windows did not confirm each other, so that pairing is not an accepted evaluated baseline.
Two adjacent weekly windows
A 24-year weekly history of a major industrial average was scored in two adjacent 12-year windows, 1968 to 1979 and 1980 to 1991. The split-sample window divides that long weekly history into two consecutive 12-year blocks to test whether a directional result repeats.
The filters compared the weekly close with 4-, 13-, 26-, and 52-week exponential averages and also compared those averages with one another. A moving average in this setting is a lookback summary of ordered prices used as an explicit baseline for later directional forecasts over a stated sampling interval.
An exponential average was defined as the prior average plus a smoothing weight times the gap between the latest price and that prior average, with the weight approximated as 2/(n+1). Exponential smoothing is that recursive blend of the latest price with the prior average.
A stance that lasts until the opposite cross
A moving-average-crossover turns the relative position of a faster average, or of price versus an average, into a bullish or bearish stance that lasts until the opposite cross. After a bullish cross the stance stayed bullish until a bearish cross, so every intervening week was scored, not only the week of the cross.
Regime occupancy is that choice to score every week spent in the stance, not only the week the lines meet, so a significance test has enough observations.
Directional hits at several horizons
Each occupied week was judged by whether later price moved with the short-versus-long alignment at 1, 5, 13, 26, and 52 weeks ahead. A directional hit counts the week correct when later price rises after a short-over-long stance, or falls after a short-under-long stance.
A chi-squared test marked a result as probably significant, significant, or highly significant when chance would produce it about once in 20, 100, or 1,000 repeats. Those chi-squared bands label how rarely a hit rate would appear under chance in about 20, 100, or 1,000 repeats of the same test.
13-week directional hit rate by DJIA average crossover, two 12-year windows
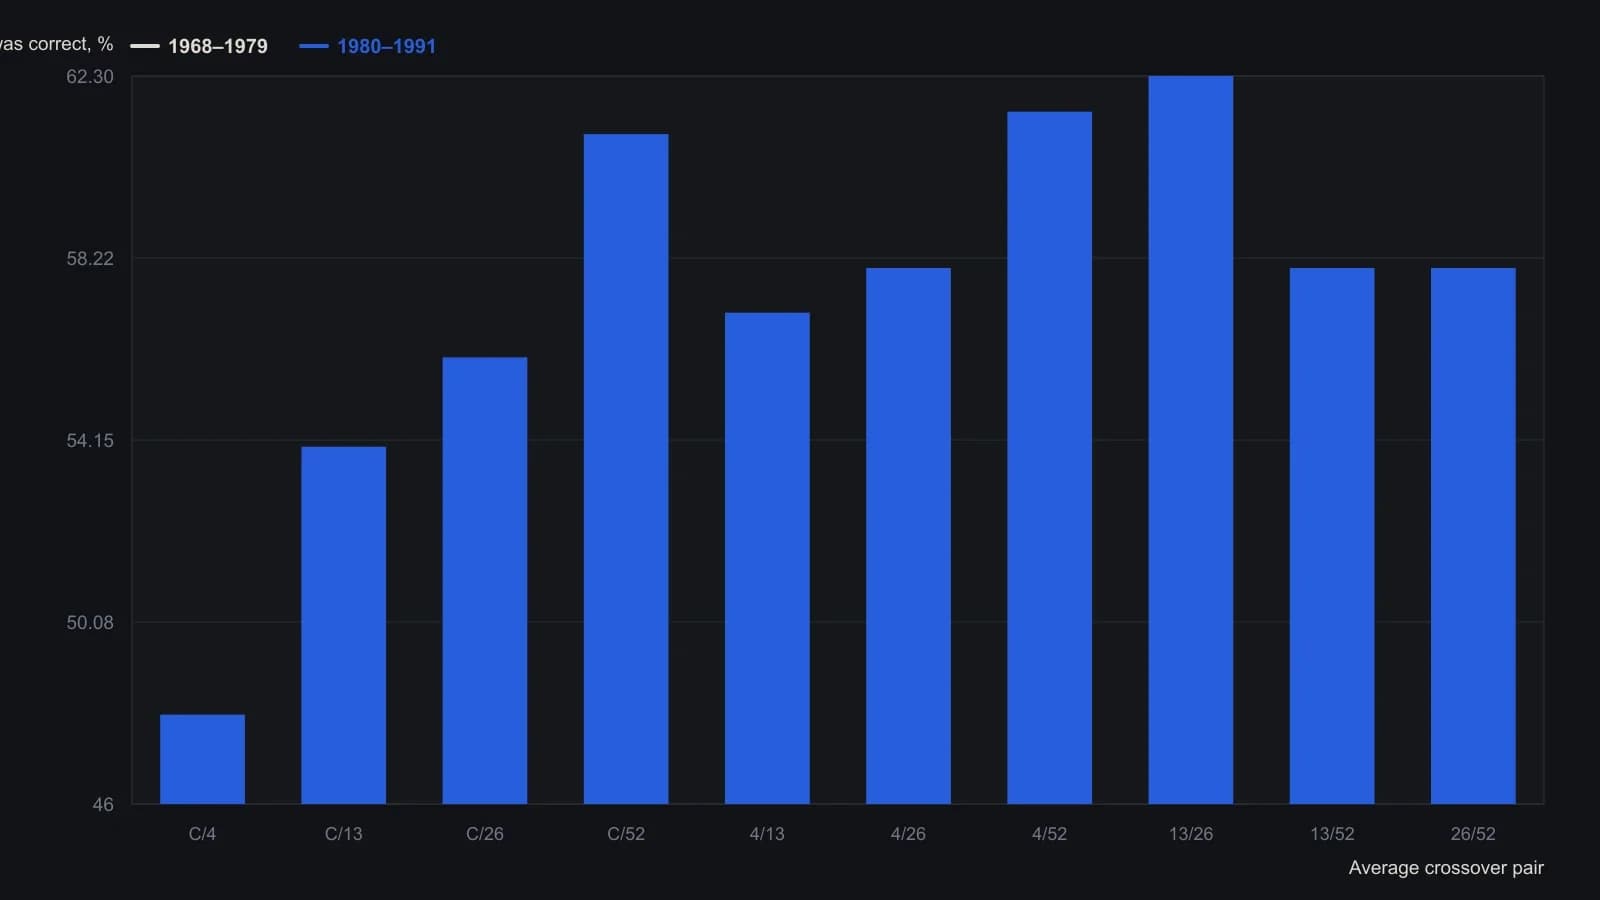
Every occupied week after a bullish or bearish cross is scored, not just the crossover week. HS on the figure is Merrill’s chi-squared label for a result that would occur by chance once in 1,000 trials. Y-axis on the printed figure runs 40 percent at the top to 60 percent at the bottom.
What repeated, and what did not
Close versus the 4-week average was near even money for the following week in both 12-year windows.
The 13-week horizon produced the strongest cluster of directional hits. The first 12-year window otherwise showed little departure from chance at short and intermediate horizons.
Year-ahead scores for the longer pairs in the first window sat below 50 percent and were read as trend-change cues rather than trend continuation.
Averaging the 1-, 5-, 13-, and 26-week horizons, the 13-versus-26 pairing posted the best mean directional score, but the two 12-year windows did not confirm each other.
All readings on this track · 57 readings
- 1988Constructing moving averages: weights, smoothing and crossovers
- 1988Constructing breadth and average trend states
- 1989Evaluating an always-in-the-market moving-average crossover
- 1989Constructing symmetric market-breadth ratio accumulators
- 1989Objective crossover tests of Fibonacci wave ratios
- 1990Volume-adjusted moving average construction
- 1991Constructing a mechanical crossover on a synthetic price series
- 1991A two-speed breadth reading for intermediate market direction
- 1992A Deutschemark yield map with dual-average and relative-strength timing
- 1992Confirming currency-fund trends with a crossover and a filter
- 1992A moving-average slope filter for crossover signals
- 1992Occupancy and split-sample tests for average crossovers
- 1994Gold-mining seasonality and bond-fund duration switching
- 1994Price oscillator from two moving averages
- 1995Explicit exponential weights and binary entry filters
- 1996Currency futures crossover with slope, bond filter, and stop
- 1996Two-market average crossover entry with a fixed stop
- 1997Construction of a filtered three-average crossover
- 1998Two-group exponential average compression as a trend filter
- 1998Constructing r-squared trend filters with dual lookbacks
- 1998Moving-average length is a habit, not a secret
- 1999Solving the close that triggers a moving-average crossover
- 2000Kagi yang and yin control versus crossover noise
- 2000Constructing simple moving average crossover filters
- 2000Building a vertical-horizontal filter to gate trend signals
- 2000Two-average crossover as a check on trend following
- 2003Stacked exponential-average retracement entries and extreme stops
- 2003Evaluating oscillator thresholds against optimized crossovers
- 2004Constructing a semicycle trend-quality filter
- 2004Commodity subgroups labeled by crossover, support, or convergence
- 2004Full-window evaluation of crossover trend systems
- 2004Two-average trend filters as a classroom critique of indicator stacking
- 2005Three-layer confirmation from a moving-average cross, candles, and Q-stick
- 2005Charting put prices beside an equity breakdown
- 2005Range-gated moving-average crossover construction
- 2007Anticipating a simple-average crossover with a threshold-close
- 2007Anticipating moving-average crossovers one bar ahead
- 2007Lead-series moving-average crossovers with a stochastic and relative strength index
- 2007Next-bar SMA crossover hypotheses from theoretical crossing values
- 2007Anticipating a moving-average crossover before confirmation
- 2007A three-horizon moving-average stack as a construction problem
- 2007Confirming trend with regression slope and r-squared
- 2008Constructing a multi-timeframe smoothed crossover
- 2008Best-day clusters versus trend filters
- 2008Allied markets as a confirmation gate for crossover and breakout signals
- 2008Weekly exponential-average crossover as a mechanical trend case study
- 2010Evaluating a 200-day crossover as long, short, and stand-aside rules
- 2010Read a 10-and-40 trend on two neighboring time frames
- 2012Sampling unit as a first-class parameter on dual simple moving averages
- 2012Constructing index-ETF entries from volatility-index persistence
- 2013Moving-average baselines versus crossover signals
- 2013Constructing a typical-price and heikin-ashi crossover as one mechanical procedure
- 2016A three-gate checklist for longs after a sharp drop
- 2016Weekly inflation-ratio crossover for commodity regimes
- 2017Normalized Laguerre zero-axis warning as a two-marker construction
- 2019Range-weighted construction of an adaptive exponential moving average
- 2020Construct a second-pullback entry after a moving-average crossover