1995issue C121-7
Explicit exponential weights and binary entry filters
Equal-weighted averages apply the same weight to every bar they include, while exponential averages assign weights from a mathematical formula. A weighting-factor can replace the usual length-to-constant conversion so the weight itself is the input. A relative-strength-index cross and a moving-average-crossover can then share one report if each is written as an entry-filter and read after a named holding-window.
- A conventional exponential average converts a length into a constant equal to 2 divided by that length plus 1, so that length is not a trailing window of that many bars.
- A weighting-factor of 0.2 matches a conventional length of 9, and raising the factor pulls the smoother toward current prices.
- After the first bar, the recursive update multiplies the new price by the factor and the prior smoothed value by one minus the factor.
- An entry-filter equals one on a signal day and zero otherwise, so a relative-strength-index rule and a moving-average-crossover can be swapped without rewriting the rest of the test.
Write the weight as a factor
Equal-weighted averages apply the same weight to every bar they include, while exponential averages assign weights from a mathematical formula. Exponential-smoothing is a recursive average that applies a stated weight to the newest observation and the complementary weight to the prior smoothed value.
A conventional exponential average converts a length into a constant equal to 2 divided by that length plus 1, so the length input does not mean a trailing window of that many bars. Substituting a decimal factor for that derived constant makes the weight itself the input. That weighting-factor is a decimal input that sets how much of each new price enters the smoother, replacing a length-to-constant conversion. A factor of 0.2 matches a conventional length of 9.
Raising the factor pulls the smoother toward current prices, which is the inverse of raising a length input. After the first bar, the recursive update multiplies the new price by the factor and the prior smoothed value by one minus the factor.
Write each entry as a filter
A relative-strength-index is used here as a long-side entry filter when it crosses upward through a stated threshold. A long-side entry can be defined as the relative-strength-index crossing upward through 30 and then inspected after a 60-day holding-window. A holding-window is a fixed number of sampling intervals after an entry signal over which later outcomes are tabulated.
The same screening layout can count those signals over a 1,000-trading-day lookback and record how many positions were ahead after the chosen hold, plus average percentage advances and declines.
A moving-average-crossover is a signal formed when a shorter average of price crosses a longer average in a specified direction. The same report can test a 10-period average crossing upward through a 50-period average by replacing only the formula that equals 1 on the signal day and 0 otherwise. That entry-filter lets alternative constructions be substituted without rewriting the rest of the test. The 60-day holding-window can be changed, or several holding windows can be checked in one report by adding more formulas.
RSI-30 upcross entries after a 60-day hold
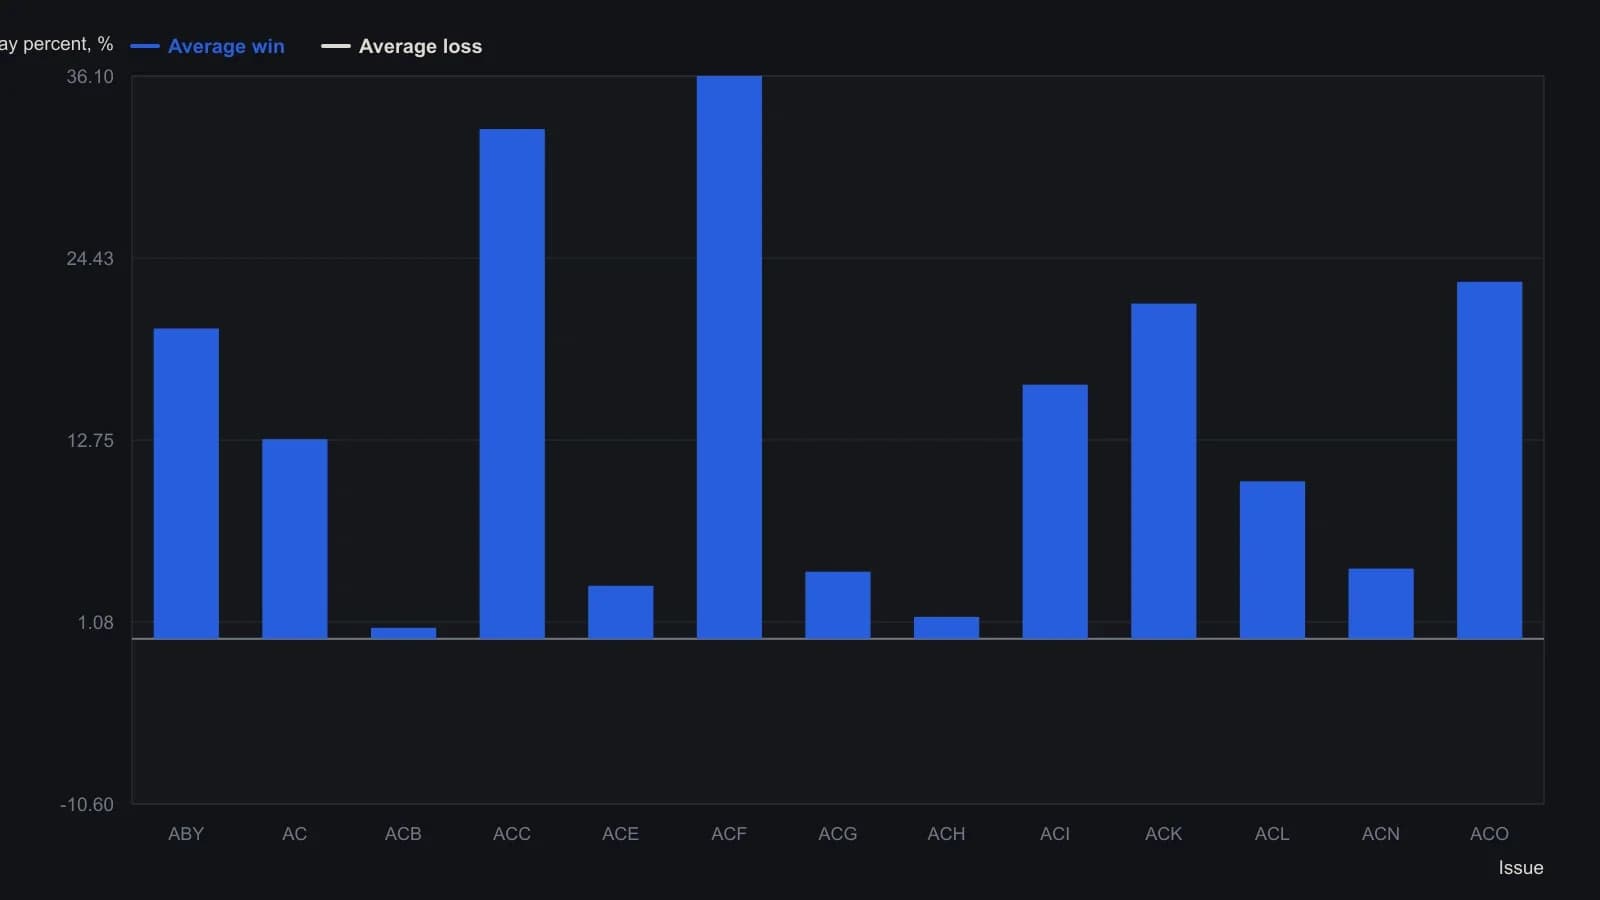
The report counts signals over the last 1,000 trading days and marks each long 60 days later. The entry is written as a binary filter so the same sheet can swap in other rules.
All readings on this track · 57 readings
- 1988Constructing moving averages: weights, smoothing and crossovers
- 1988Constructing breadth and average trend states
- 1989Evaluating an always-in-the-market moving-average crossover
- 1989Constructing symmetric market-breadth ratio accumulators
- 1989Objective crossover tests of Fibonacci wave ratios
- 1990Volume-adjusted moving average construction
- 1991Constructing a mechanical crossover on a synthetic price series
- 1991A two-speed breadth reading for intermediate market direction
- 1992A Deutschemark yield map with dual-average and relative-strength timing
- 1992Confirming currency-fund trends with a crossover and a filter
- 1992A moving-average slope filter for crossover signals
- 1992Occupancy and split-sample tests for average crossovers
- 1994Gold-mining seasonality and bond-fund duration switching
- 1994Price oscillator from two moving averages
- 1995Explicit exponential weights and binary entry filters
- 1996Currency futures crossover with slope, bond filter, and stop
- 1996Two-market average crossover entry with a fixed stop
- 1997Construction of a filtered three-average crossover
- 1998Two-group exponential average compression as a trend filter
- 1998Constructing r-squared trend filters with dual lookbacks
- 1998Moving-average length is a habit, not a secret
- 1999Solving the close that triggers a moving-average crossover
- 2000Kagi yang and yin control versus crossover noise
- 2000Constructing simple moving average crossover filters
- 2000Building a vertical-horizontal filter to gate trend signals
- 2000Two-average crossover as a check on trend following
- 2003Stacked exponential-average retracement entries and extreme stops
- 2003Evaluating oscillator thresholds against optimized crossovers
- 2004Constructing a semicycle trend-quality filter
- 2004Commodity subgroups labeled by crossover, support, or convergence
- 2004Full-window evaluation of crossover trend systems
- 2004Two-average trend filters as a classroom critique of indicator stacking
- 2005Three-layer confirmation from a moving-average cross, candles, and Q-stick
- 2005Charting put prices beside an equity breakdown
- 2005Range-gated moving-average crossover construction
- 2007Anticipating a simple-average crossover with a threshold-close
- 2007Anticipating moving-average crossovers one bar ahead
- 2007Lead-series moving-average crossovers with a stochastic and relative strength index
- 2007Next-bar SMA crossover hypotheses from theoretical crossing values
- 2007Anticipating a moving-average crossover before confirmation
- 2007A three-horizon moving-average stack as a construction problem
- 2007Confirming trend with regression slope and r-squared
- 2008Constructing a multi-timeframe smoothed crossover
- 2008Best-day clusters versus trend filters
- 2008Allied markets as a confirmation gate for crossover and breakout signals
- 2008Weekly exponential-average crossover as a mechanical trend case study
- 2010Evaluating a 200-day crossover as long, short, and stand-aside rules
- 2010Read a 10-and-40 trend on two neighboring time frames
- 2012Sampling unit as a first-class parameter on dual simple moving averages
- 2012Constructing index-ETF entries from volatility-index persistence
- 2013Moving-average baselines versus crossover signals
- 2013Constructing a typical-price and heikin-ashi crossover as one mechanical procedure
- 2016A three-gate checklist for longs after a sharp drop
- 2016Weekly inflation-ratio crossover for commodity regimes
- 2017Normalized Laguerre zero-axis warning as a two-marker construction
- 2019Range-weighted construction of an adaptive exponential moving average
- 2020Construct a second-pullback entry after a moving-average crossover