2005issue C061-4
Charting put prices beside an equity breakdown
A 2005 case charts Newmont's head-and-shoulders breakdown on the stock and reads the March 40 put as its own options-price-chart, looking for positive-stochastic-divergence, an oversold seven-ten-stochastic, and an ema-crossover on the listed contract.
- Listed put and call prices are treated as an options-price-chart so the contract's trend can be read independently of the underlying.
- Editorial interpretation: the stock may state the breakdown, but the idea is not treated as timed until the put prints positive-stochastic-divergence and an ema-crossover.
- Entries are located with divergences, recognized patterns, and support or resistance on the option chart, near a make-or-break-level.
- The working vehicle in the case is a one-strike-out-of-the-money put, priced around 1.00 and within a few weeks of expiration.
Two charts, two jobs
The piece treats the listed prices of puts and calls as an options-price-chart. That series is read for the contract's own trend instead of inferring direction only from the underlying.
Editorial interpretation: keep the two jobs separate. The underlying supplies the directional hypothesis. The listed put is treated as timed only after it prints its own positive-stochastic-divergence and a short-versus-long moving-average cross.
The stock states the breakdown
As of mid-January 2005, Newmont Mining was described as having broken the neckline of a head-and-shoulders top and pulling back to test that neckline as resistance near 43. A formation high near 50 and a neckline at 43 were used to project a minimum downside of about seven points toward 36.
The listed put as the vehicle
March 2005 40 puts, then one-strike-out-of-the-money given nearby 45 and 42.50 strikes, were offered as an options expression of that breakdown view.
The text records conflicting selection rules for directional buyers, ranging from high-delta in-the-money contracts and at-the-money options near expiration to cheaper out-of-the-money contracts and mid-priced contracts chosen to shrink percentage bid-ask cost. The working preference stated in the text is a contract one strike away, priced around 1.00, and within a few weeks of expiration.
Confirmation on the put chart
Divergences, recognized patterns, and support or resistance on the option chart are used to locate entries near a make-or-break-level. That zone is the chart-defined invalidation area, so the distance from entry to stop stays small relative to the intended move.
The Newmont March 2005 40-strike put printed positive-stochastic-divergence on its late-November and December declines. After a December higher low versus November, that put's 10-day exponential moving average crossed above its 50-day average in January, the ema-crossover on the contract's own closes, while a seven-ten-stochastic reading was described as oversold.
The same oscillator shape on another put
The General Motors January 40 put showed higher seven-ten-stochastic troughs against lower option-price lows from mid-December into early January. That is the same positive-stochastic-divergence shape: oscillator troughs that rise while the option prints lower price lows.
Editorial interpretation: the second contract is shown so the confirmation logic can be seen on more than one listed put. It is not a broader market claim.
Newmont Mining daily close through the head-and-shoulders breakdown
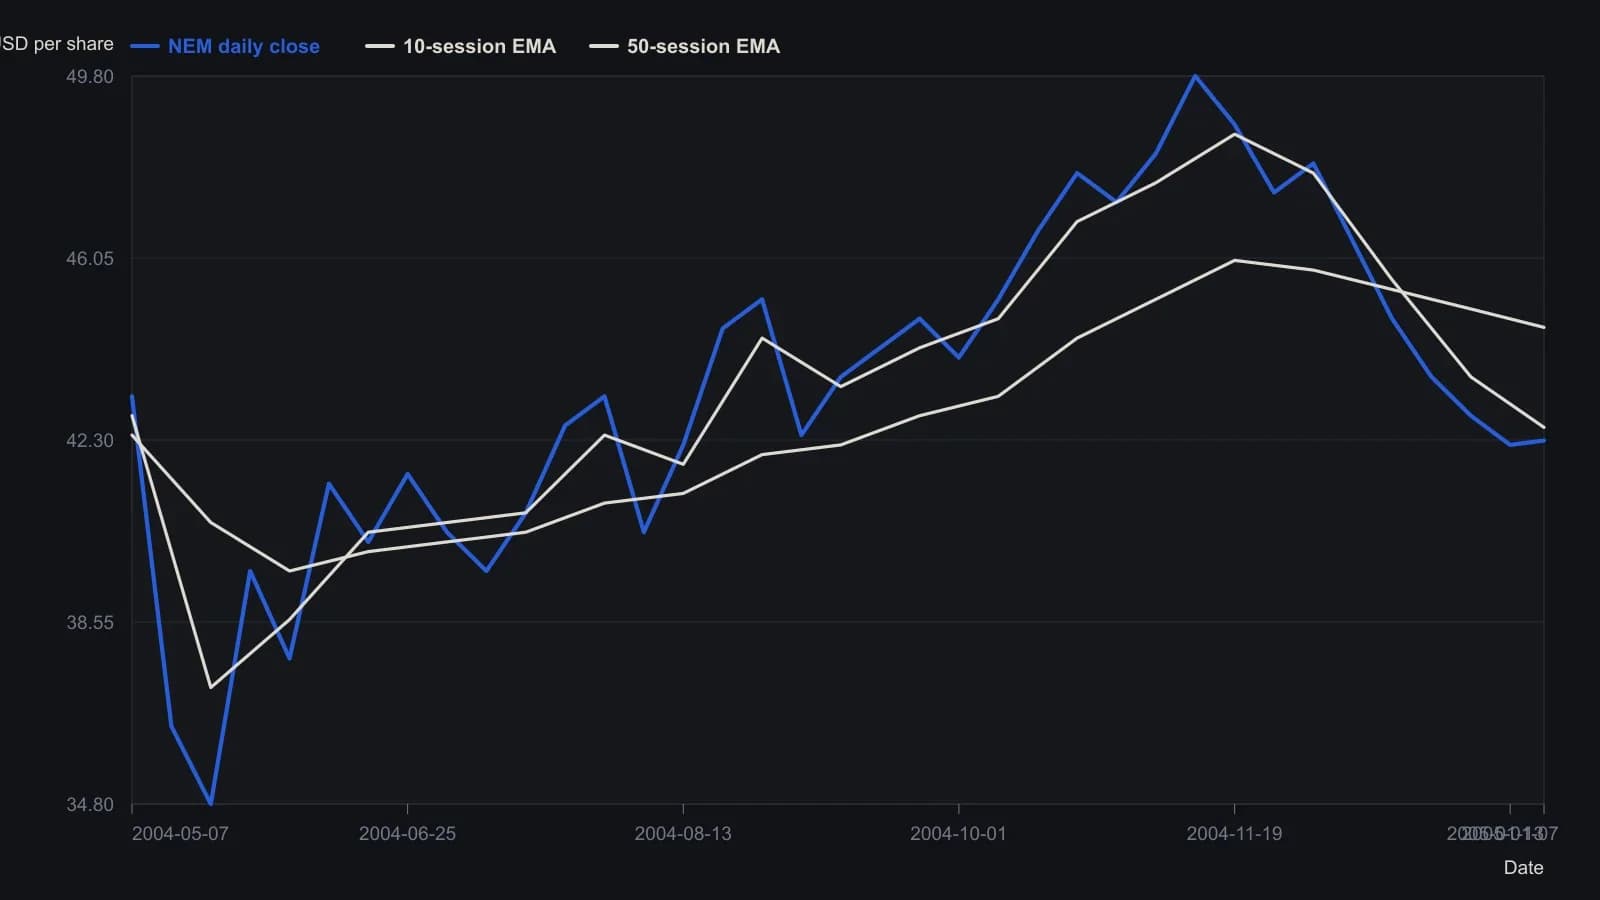
Path values are visual readings from the daily candlestick pane on a linear 34–50 scale, sampled about weekly so the raster is not over-specified. Last close 42.29, 10-session EMA 42.56 and 50-session EMA 44.62 are the printed quote-strip figures as of 13 January 2005. The article’s neckline (~43), formation high (~50) and May 2004 low (~35) match the same pane.
All readings on this track · 57 readings
- 1988Constructing moving averages: weights, smoothing and crossovers
- 1988Constructing breadth and average trend states
- 1989Evaluating an always-in-the-market moving-average crossover
- 1989Constructing symmetric market-breadth ratio accumulators
- 1989Objective crossover tests of Fibonacci wave ratios
- 1990Volume-adjusted moving average construction
- 1991Constructing a mechanical crossover on a synthetic price series
- 1991A two-speed breadth reading for intermediate market direction
- 1992A Deutschemark yield map with dual-average and relative-strength timing
- 1992Confirming currency-fund trends with a crossover and a filter
- 1992A moving-average slope filter for crossover signals
- 1992Occupancy and split-sample tests for average crossovers
- 1994Gold-mining seasonality and bond-fund duration switching
- 1994Price oscillator from two moving averages
- 1995Explicit exponential weights and binary entry filters
- 1996Currency futures crossover with slope, bond filter, and stop
- 1996Two-market average crossover entry with a fixed stop
- 1997Construction of a filtered three-average crossover
- 1998Two-group exponential average compression as a trend filter
- 1998Constructing r-squared trend filters with dual lookbacks
- 1998Moving-average length is a habit, not a secret
- 1999Solving the close that triggers a moving-average crossover
- 2000Kagi yang and yin control versus crossover noise
- 2000Constructing simple moving average crossover filters
- 2000Building a vertical-horizontal filter to gate trend signals
- 2000Two-average crossover as a check on trend following
- 2003Stacked exponential-average retracement entries and extreme stops
- 2003Evaluating oscillator thresholds against optimized crossovers
- 2004Constructing a semicycle trend-quality filter
- 2004Commodity subgroups labeled by crossover, support, or convergence
- 2004Full-window evaluation of crossover trend systems
- 2004Two-average trend filters as a classroom critique of indicator stacking
- 2005Three-layer confirmation from a moving-average cross, candles, and Q-stick
- 2005Charting put prices beside an equity breakdown
- 2005Range-gated moving-average crossover construction
- 2007Anticipating a simple-average crossover with a threshold-close
- 2007Anticipating moving-average crossovers one bar ahead
- 2007Lead-series moving-average crossovers with a stochastic and relative strength index
- 2007Next-bar SMA crossover hypotheses from theoretical crossing values
- 2007Anticipating a moving-average crossover before confirmation
- 2007A three-horizon moving-average stack as a construction problem
- 2007Confirming trend with regression slope and r-squared
- 2008Constructing a multi-timeframe smoothed crossover
- 2008Best-day clusters versus trend filters
- 2008Allied markets as a confirmation gate for crossover and breakout signals
- 2008Weekly exponential-average crossover as a mechanical trend case study
- 2010Evaluating a 200-day crossover as long, short, and stand-aside rules
- 2010Read a 10-and-40 trend on two neighboring time frames
- 2012Sampling unit as a first-class parameter on dual simple moving averages
- 2012Constructing index-ETF entries from volatility-index persistence
- 2013Moving-average baselines versus crossover signals
- 2013Constructing a typical-price and heikin-ashi crossover as one mechanical procedure
- 2016A three-gate checklist for longs after a sharp drop
- 2016Weekly inflation-ratio crossover for commodity regimes
- 2017Normalized Laguerre zero-axis warning as a two-marker construction
- 2019Range-weighted construction of an adaptive exponential moving average
- 2020Construct a second-pullback entry after a moving-average crossover