2013issue C018-11
Moving-average baselines versus crossover signals
The archive treats a simple moving average as a market-specific lookback for reading trend direction. Golden-cross and death-cross stories are then set aside as lagging events that often arrive late or prove false, and so cannot serve as a buy or sell rule.
- The archive names simple, exponential, and weighted averages, then confines the discussion to the simple moving average: the arithmetic mean of prices over a stated lookback, used to read trend direction rather than a trading range.
- A lookback is chosen market by market. A 50-day simple average may fit one listing and fail on another, and the line should be rechecked by visual inspection or by backtesting rather than forced onto current prices.
- Trend is classified from swing structure first. The average only locates add-on entries after a long is already profitable, the exit is a trend change, and a sideways slip does not cancel an uptrend unless the last major swing low is broken.
- A golden cross and a death cross are a shorter average crossing a longer one. The archive treats both as lagging events that often arrive late or prove false, and it rejects crossover timing as a buy or sell rule.
The average is a lookback
The archive names three moving-average constructions: simple, exponential, and weighted. It confines the discussion to the simple moving average, the arithmetic mean of prices over a stated period.
That average is treated as a tool for reading trend direction. When a market is stuck in a trading range, the archive says a different class of indicator is preferable.
Editorial note: treat the moving average as a lookback a market either continues to respect or quietly outgrows.
No universal window
The archive rejects a universal lookback. A 50-day simple average may fit one listing and fail on another, so the window must be chosen market by market.
A market’s relationship to a given average can change over time. The line should be rechecked, by visual inspection or by backtesting, rather than forced onto current prices.
One equity index is discussed against a 250-day simple average. Another is discussed against a 150-day simple average. The window is presented as market-specific rather than fixed.
Sensex daily closes versus the 250-day SMA
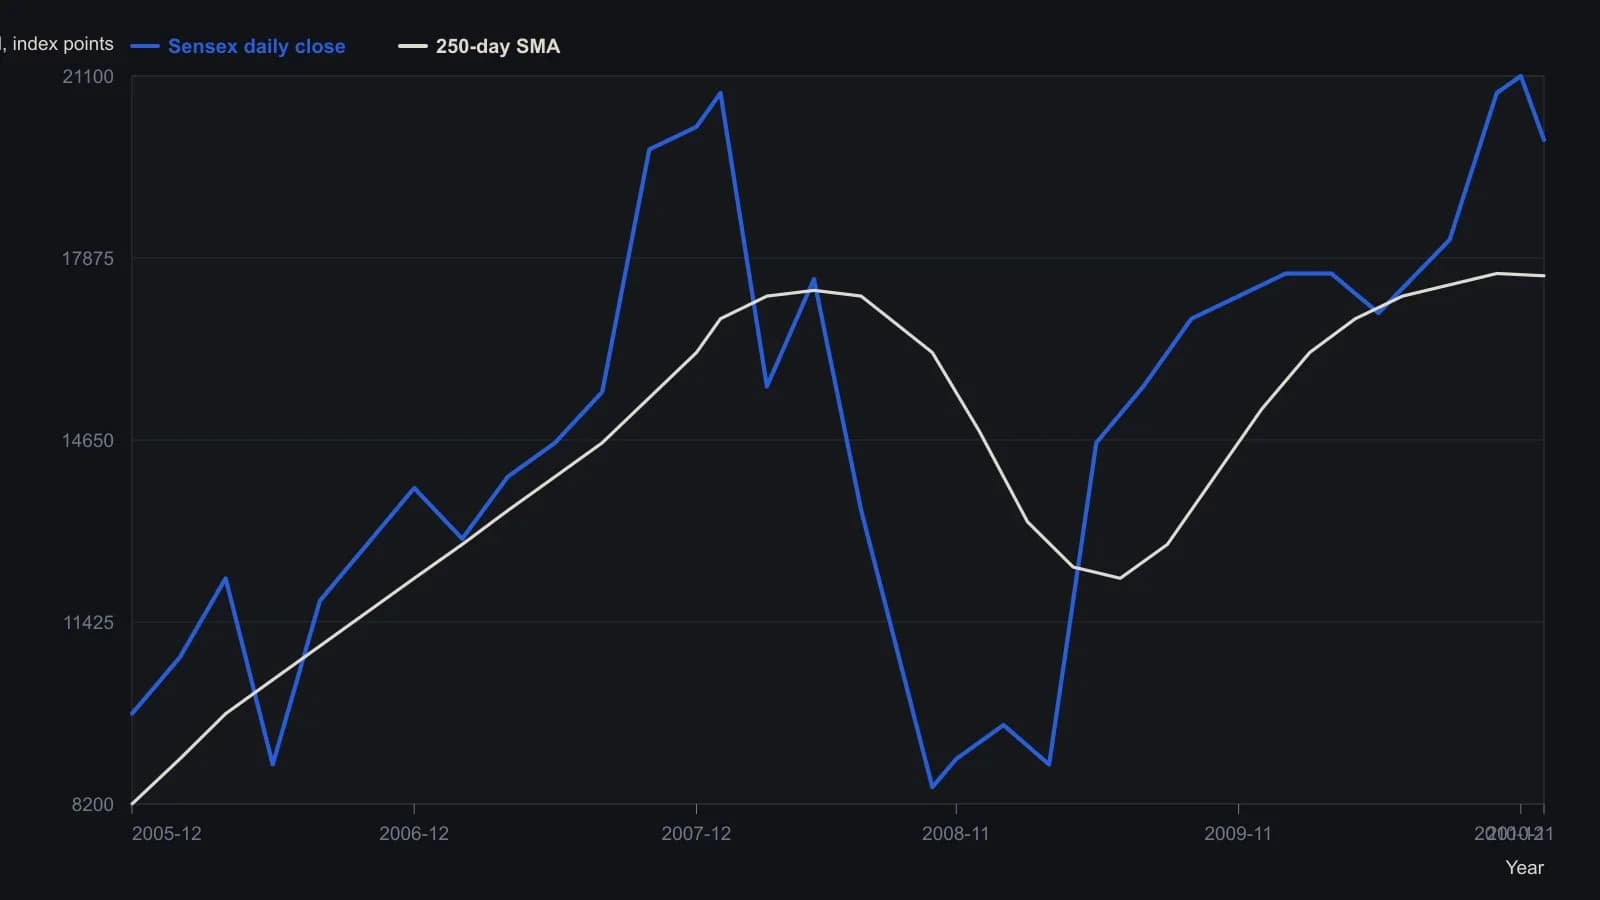
Digitized from the published candle chart; about 40 points keep the 2006–10 path and 250-day SMA without inventing intra-bar precision. Header last 19966.93, high 21206.77, low 7697.39, and SMA 17999.14 match the raster callouts.
Swing structure first
The archive first classifies trend from swing highs and lows. The average is used only to locate add-on entries after a long is already profitable.
The exit is a trend change, not a wait for the average to turn.
When an uptrend slips into a sideways interval, the trend label stays intact so long as the last major swing low is not decisively broken, even if price dips through the average.
Crossovers as lagging events
A golden cross is a shorter average crossing above a longer one. A death cross is the reverse.
The archive argues that both are lagging events that often arrive late or prove false.
In an early-July 2010 case, a 50-day average crossed below a 200-day average and a golden cross followed a few days later while price continued higher. The archive uses that sequence to reject crossover timing as a buy or sell rule.
All readings on this track · 57 readings
- 1988Constructing moving averages: weights, smoothing and crossovers
- 1988Constructing breadth and average trend states
- 1989Evaluating an always-in-the-market moving-average crossover
- 1989Constructing symmetric market-breadth ratio accumulators
- 1989Objective crossover tests of Fibonacci wave ratios
- 1990Volume-adjusted moving average construction
- 1991Constructing a mechanical crossover on a synthetic price series
- 1991A two-speed breadth reading for intermediate market direction
- 1992A Deutschemark yield map with dual-average and relative-strength timing
- 1992Confirming currency-fund trends with a crossover and a filter
- 1992A moving-average slope filter for crossover signals
- 1992Occupancy and split-sample tests for average crossovers
- 1994Gold-mining seasonality and bond-fund duration switching
- 1994Price oscillator from two moving averages
- 1995Explicit exponential weights and binary entry filters
- 1996Currency futures crossover with slope, bond filter, and stop
- 1996Two-market average crossover entry with a fixed stop
- 1997Construction of a filtered three-average crossover
- 1998Two-group exponential average compression as a trend filter
- 1998Constructing r-squared trend filters with dual lookbacks
- 1998Moving-average length is a habit, not a secret
- 1999Solving the close that triggers a moving-average crossover
- 2000Kagi yang and yin control versus crossover noise
- 2000Constructing simple moving average crossover filters
- 2000Building a vertical-horizontal filter to gate trend signals
- 2000Two-average crossover as a check on trend following
- 2003Stacked exponential-average retracement entries and extreme stops
- 2003Evaluating oscillator thresholds against optimized crossovers
- 2004Constructing a semicycle trend-quality filter
- 2004Commodity subgroups labeled by crossover, support, or convergence
- 2004Full-window evaluation of crossover trend systems
- 2004Two-average trend filters as a classroom critique of indicator stacking
- 2005Three-layer confirmation from a moving-average cross, candles, and Q-stick
- 2005Charting put prices beside an equity breakdown
- 2005Range-gated moving-average crossover construction
- 2007Anticipating a simple-average crossover with a threshold-close
- 2007Anticipating moving-average crossovers one bar ahead
- 2007Lead-series moving-average crossovers with a stochastic and relative strength index
- 2007Next-bar SMA crossover hypotheses from theoretical crossing values
- 2007Anticipating a moving-average crossover before confirmation
- 2007A three-horizon moving-average stack as a construction problem
- 2007Confirming trend with regression slope and r-squared
- 2008Constructing a multi-timeframe smoothed crossover
- 2008Best-day clusters versus trend filters
- 2008Allied markets as a confirmation gate for crossover and breakout signals
- 2008Weekly exponential-average crossover as a mechanical trend case study
- 2010Evaluating a 200-day crossover as long, short, and stand-aside rules
- 2010Read a 10-and-40 trend on two neighboring time frames
- 2012Sampling unit as a first-class parameter on dual simple moving averages
- 2012Constructing index-ETF entries from volatility-index persistence
- 2013Moving-average baselines versus crossover signals
- 2013Constructing a typical-price and heikin-ashi crossover as one mechanical procedure
- 2016A three-gate checklist for longs after a sharp drop
- 2016Weekly inflation-ratio crossover for commodity regimes
- 2017Normalized Laguerre zero-axis warning as a two-marker construction
- 2019Range-weighted construction of an adaptive exponential moving average
- 2020Construct a second-pullback entry after a moving-average crossover