2007issue C081-4
A three-horizon moving-average stack as a construction problem
Three spaced moving averages can mark when a market leaves a quieter base and enters a directional move. The construction uses the first completed stack as the setup, waits for a later break of that bar, and blocks new trades on the wrong side of the longest average.
- The three lookbacks must be clearly short, intermediate, and long; similar lengths weaken the moving-average trio as a reading of acceleration or deceleration.
- Only the first-alignment bar is the setup; later bars that remain stacked do not reset the follow-through trigger.
- A later break of that bar's extreme is the follow-through entry, and the long-horizon filter blocks new longs beneath the longest average and new shorts above it.
- A short-over-intermediate cross that remains beneath the 50-period average is not a completed upward realignment.
A trio that marks a change of stage
A trend-stage procedure can be assembled from three moving averages of different lengths. Relative order and crossovers mark when a market leaves a quieter basing interval and enters a directional advance or decline.
Those three lines are a moving-average trio: a short, intermediate, and long average read together as one stage-and-trend instrument rather than as three separate lines.
Lookback spacing comes first
The three lookbacks must be clearly short, intermediate, and long relative to one another. Similar lengths weaken the stack as a reading of acceleration or deceleration.
Lookback spacing is that gap in length. It is what lets the trio show whether shorter-horizon price is outrunning or lagging longer-horizon price.
One specified construction uses 10-, 20-, and 50-period exponential moving averages on weekly bars so that alignment changes persist longer and shorter-bar noise is reduced.
Bullish and bearish alignment
The strongest upward stack is all three averages rising with the short average above the intermediate and the intermediate above the long. That state is bullish alignment.
The strongest downward stack is the reverse order with all three declining. That state is bearish alignment, with the averages falling and sitting in long-over-intermediate-over-short order.
Alignment names the lasting short-then-intermediate-then-long order in the direction of the move. Realignment names only the brief transition into that order.
The first-alignment bar is the setup
The construction treats the first bar on which the three averages complete a bullish or bearish stack as the setup bar, not later bars that merely remain stacked. That session is the first-alignment bar. Its high or low becomes the follow-through trigger.
A long is considered only if later price exceeds the high of the first bullish-alignment bar. A short is considered only if later price breaks the low of the first bearish-alignment bar. That later break is the follow-through entry, so the procedure does not act before price confirms the stack.
Weekly copper with a 10-20-50 exponential-average stack
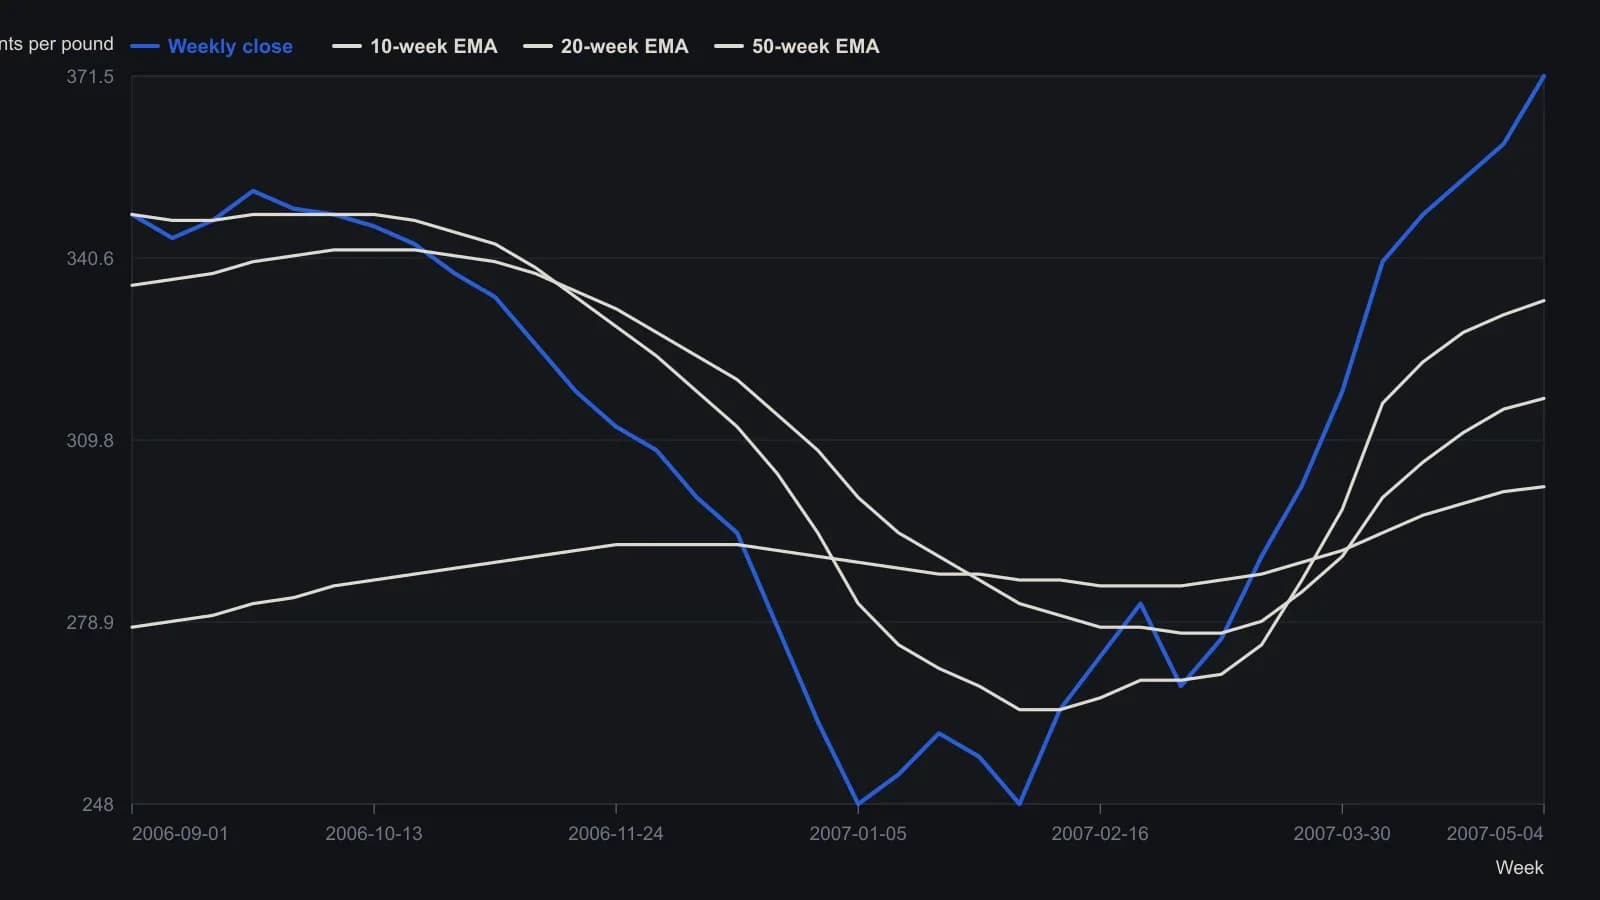
The source fixes the trio at 10-, 20- and 50-week exponential moving averages on weekly continuous copper. Mid-window prices are read from the labeled cents scale and are approximate to a few cents; the final averages 333.40, 316.80 and 301.82 are the prints on the chart.
The long-horizon filter vetoes opposing entries
The 50-period average is a directional constraint. The procedure does not initiate longs while price is below that average or shorts while price is above it. That rule is the long-horizon filter.
A short-over-intermediate cross that remains beneath the 50-period average is not counted as a completed upward realignment.
When two bars could be first
If two adjacent bars could be the first stacked bar and the software does not print indicator values, the construction uses the more conservative of the two session extremes as the follow-through threshold.
The same stack on other bars
The same stack can be applied on daily or hourly bars. Exits are defined separately as a close through the 20-period average, a break of the stack, or a recent swing extreme.
All readings on this track · 57 readings
- 1988Constructing moving averages: weights, smoothing and crossovers
- 1988Constructing breadth and average trend states
- 1989Evaluating an always-in-the-market moving-average crossover
- 1989Constructing symmetric market-breadth ratio accumulators
- 1989Objective crossover tests of Fibonacci wave ratios
- 1990Volume-adjusted moving average construction
- 1991Constructing a mechanical crossover on a synthetic price series
- 1991A two-speed breadth reading for intermediate market direction
- 1992A Deutschemark yield map with dual-average and relative-strength timing
- 1992Confirming currency-fund trends with a crossover and a filter
- 1992A moving-average slope filter for crossover signals
- 1992Occupancy and split-sample tests for average crossovers
- 1994Gold-mining seasonality and bond-fund duration switching
- 1994Price oscillator from two moving averages
- 1995Explicit exponential weights and binary entry filters
- 1996Currency futures crossover with slope, bond filter, and stop
- 1996Two-market average crossover entry with a fixed stop
- 1997Construction of a filtered three-average crossover
- 1998Two-group exponential average compression as a trend filter
- 1998Constructing r-squared trend filters with dual lookbacks
- 1998Moving-average length is a habit, not a secret
- 1999Solving the close that triggers a moving-average crossover
- 2000Kagi yang and yin control versus crossover noise
- 2000Constructing simple moving average crossover filters
- 2000Building a vertical-horizontal filter to gate trend signals
- 2000Two-average crossover as a check on trend following
- 2003Stacked exponential-average retracement entries and extreme stops
- 2003Evaluating oscillator thresholds against optimized crossovers
- 2004Constructing a semicycle trend-quality filter
- 2004Commodity subgroups labeled by crossover, support, or convergence
- 2004Full-window evaluation of crossover trend systems
- 2004Two-average trend filters as a classroom critique of indicator stacking
- 2005Three-layer confirmation from a moving-average cross, candles, and Q-stick
- 2005Charting put prices beside an equity breakdown
- 2005Range-gated moving-average crossover construction
- 2007Anticipating a simple-average crossover with a threshold-close
- 2007Anticipating moving-average crossovers one bar ahead
- 2007Lead-series moving-average crossovers with a stochastic and relative strength index
- 2007Next-bar SMA crossover hypotheses from theoretical crossing values
- 2007Anticipating a moving-average crossover before confirmation
- 2007A three-horizon moving-average stack as a construction problem
- 2007Confirming trend with regression slope and r-squared
- 2008Constructing a multi-timeframe smoothed crossover
- 2008Best-day clusters versus trend filters
- 2008Allied markets as a confirmation gate for crossover and breakout signals
- 2008Weekly exponential-average crossover as a mechanical trend case study
- 2010Evaluating a 200-day crossover as long, short, and stand-aside rules
- 2010Read a 10-and-40 trend on two neighboring time frames
- 2012Sampling unit as a first-class parameter on dual simple moving averages
- 2012Constructing index-ETF entries from volatility-index persistence
- 2013Moving-average baselines versus crossover signals
- 2013Constructing a typical-price and heikin-ashi crossover as one mechanical procedure
- 2016A three-gate checklist for longs after a sharp drop
- 2016Weekly inflation-ratio crossover for commodity regimes
- 2017Normalized Laguerre zero-axis warning as a two-marker construction
- 2019Range-weighted construction of an adaptive exponential moving average
- 2020Construct a second-pullback entry after a moving-average crossover