1990issue C091-3
Weekly advance-decline oscillator: weight map, extremes, and spike cycle
The weekly advance-decline oscillator is the difference between a 40% exponential and a 22% exponential of weekly advancing minus declining issues. A TradersWeek editorial reading keeps the zero-line rule and the deviation band as separate signals, and treats an 18-week spike cycle as a later hypothesis rather than a forecast.
- The weekly advance-decline oscillator is the difference between a 40% exponential and a 22% exponential of weekly advancing minus declining issues.
- The exponential weight map treats a four-week average as the weekly counterpart of a 20-day average, and an eight-week average as the counterpart of a 40-day average.
- Zero-line crossovers were checked as directional forecasts over one week, five weeks, 13 weeks, 26 weeks, and one year, while unusual highs and lows used a full standard deviation and two-thirds of a standard deviation around zero.
- A TradersWeek editorial reading treats the estimated 18-week spike cycle as a dominant-cycle hypothesis about spacing, not as a directional forecast.
A weekly series from advancing minus declining issues
The weekly advance-decline oscillator is the difference between a 40% exponential and a 22% exponential of weekly advancing minus declining issues.
The daily form was described as the deviation of a 10% exponential from a 5% exponential of daily advancing minus declining issues.
Exponential weight map
A four-week average was treated as the weekly counterpart of a 20-day average, and an eight-week average as the counterpart of a 40-day average.
That pairing is the exponential weight map: weekly smoothing constants are chosen so they stand in for stated multi-week average lengths that correspond to a daily lookback.
Zero-line rule
The zero-line rule is a signal definition that uses a change in the sign of the oscillator, not its distance from zero.
Zero-line crossovers were checked as directional forecasts over one week, five weeks, 13 weeks, 26 weeks, and one year.
Deviation band
Unusual highs and lows were defined with both a full standard deviation and two-thirds of a standard deviation around zero. Those high and low thresholds are the deviation band.
The full-standard-deviation weekly thresholds used for the five-week check were +280 and -280.
A TradersWeek editorial reading keeps these two rules apart. A sign change answers a different question than a move that reaches a deviation band.
Spike cycle
A regularly recurring pattern of upward and downward spikes was noted. The median cycle length on the charted span was estimated at 18 weeks.
That visual estimate of the typical spacing between successive extreme peaks or troughs is the spike cycle.
A TradersWeek editorial reading places this count last. It is a hypothesis about spacing on the charted span, not a substitute for the zero-line rule or the deviation band, and not itself a directional forecast.
Weekly McClellan oscillator, 1985–1990, with ±280 extremes
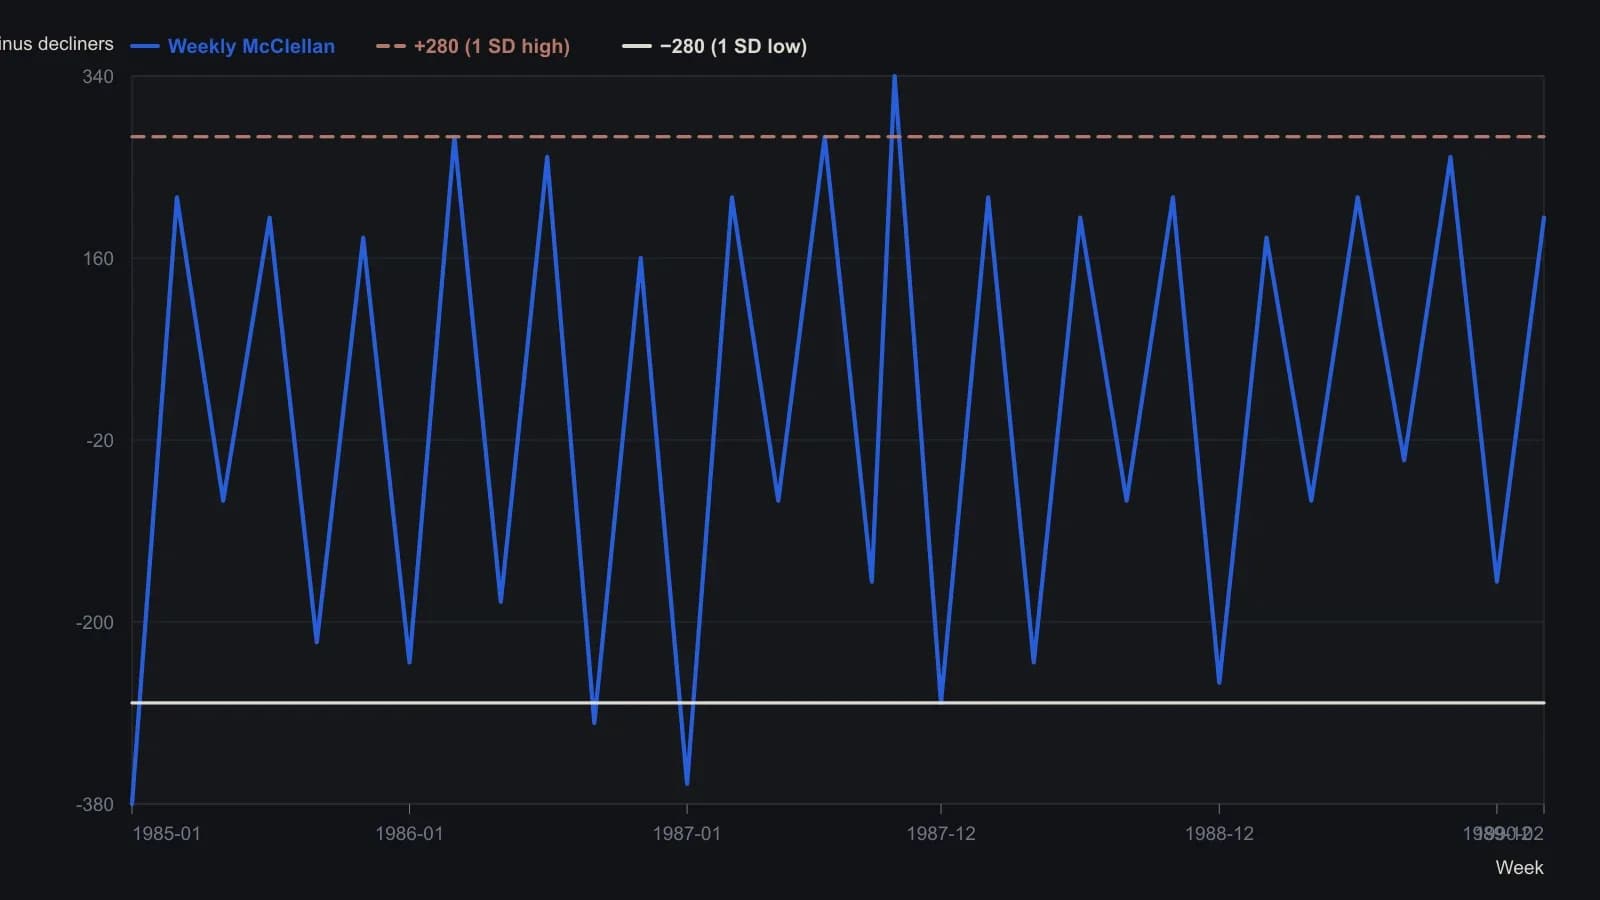
The source scan is vertically inverted; signs were restored so that plus 280 sits above zero. Weekly samples were thinned to turning points and year-boundary levels. Y-values are approximate to the nearest 20 oscillator units.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support