1991issue C071-11
Build the market clock before you read a price bar
The archive builds a market clock before it reads a price bar. First the Arms index tests breadth-volume share, then each session is redrawn as an Equivolume box, and only then does a short moving average leave a band around a longer average. Editorial note: a short-horizon band exit is a timing condition, not permission to fade the higher-horizon trend.
- Build the Arms index first so the clock records breadth-volume share, not only whether more names are up than down.
- Redraw each session as an Equivolume box so share count replaces calendar time and box shape records range bought or sold per unit of volume.
- Split the same index with nested moving averages, and treat a 4-day move outside the 15 percent envelope as timing, not as a fade of an established uptrend.
- Measure turning points as volume-cycle distances because the horizontal axis is share turnover and no trade means no market event.
Build the clock before the bar
The archive does not begin with a price bar. It first asks whether advancing issues are receiving their share of trading, then redraws each session so share count replaces calendar time, and only then lets a short moving average leave a band around a longer average.
Editorial reading: keep that construction order. A short-horizon band exit is a timing condition. It is not permission to fade the higher-horizon trend.
Start with the Arms index
In 1967 the breadth-volume index was assembled from four quote-machine fields: advances, declines, advancing volume, and declining volume. The assembly tests breadth-volume share, whether advancing or declining issues are attracting more than a proportionate amount of total volume.
The index is advances over declines, divided by advancing volume over declining volume. A print of 1.00 is a standoff. Readings below 1.00 assign extra volume to advancing issues. Readings above 1.00 assign extra volume to declining issues. Speed and direction of change are ranked above the absolute print.
That construction is the Arms index: a market-breadth measure that divides the advance-to-decline count by the ratio of advancing volume to declining volume and asks whether rising issues are receiving a proportionate share of trading.
Split the same index by horizon
The same index is then split by horizon with moving averages. A 21/55 crossover stands for the long term. The 21-day and 10-day averages stand for the intermediate term. A 4-day average is reserved for short-term timing.
A short-term band is built by multiplying a 13-day moving average of the daily index by 1.15 and 0.85. A buy or sell condition is defined only when the 4-day average of the index moves outside that 15 percent envelope.
On the 55-day moving average of the index, a reading near 1.10 or 110 is labeled very oversold and the high 80s are labeled very overbought. The 96-98 zone is used as a mid-scale reference for a less extreme long-horizon state.
A 4-day overbought reading is not used to fade an established uptrend. Any decline in that setting is treated as likely to stay limited while the major trend remains up.
Four-day Arms index leaving the 13-day band
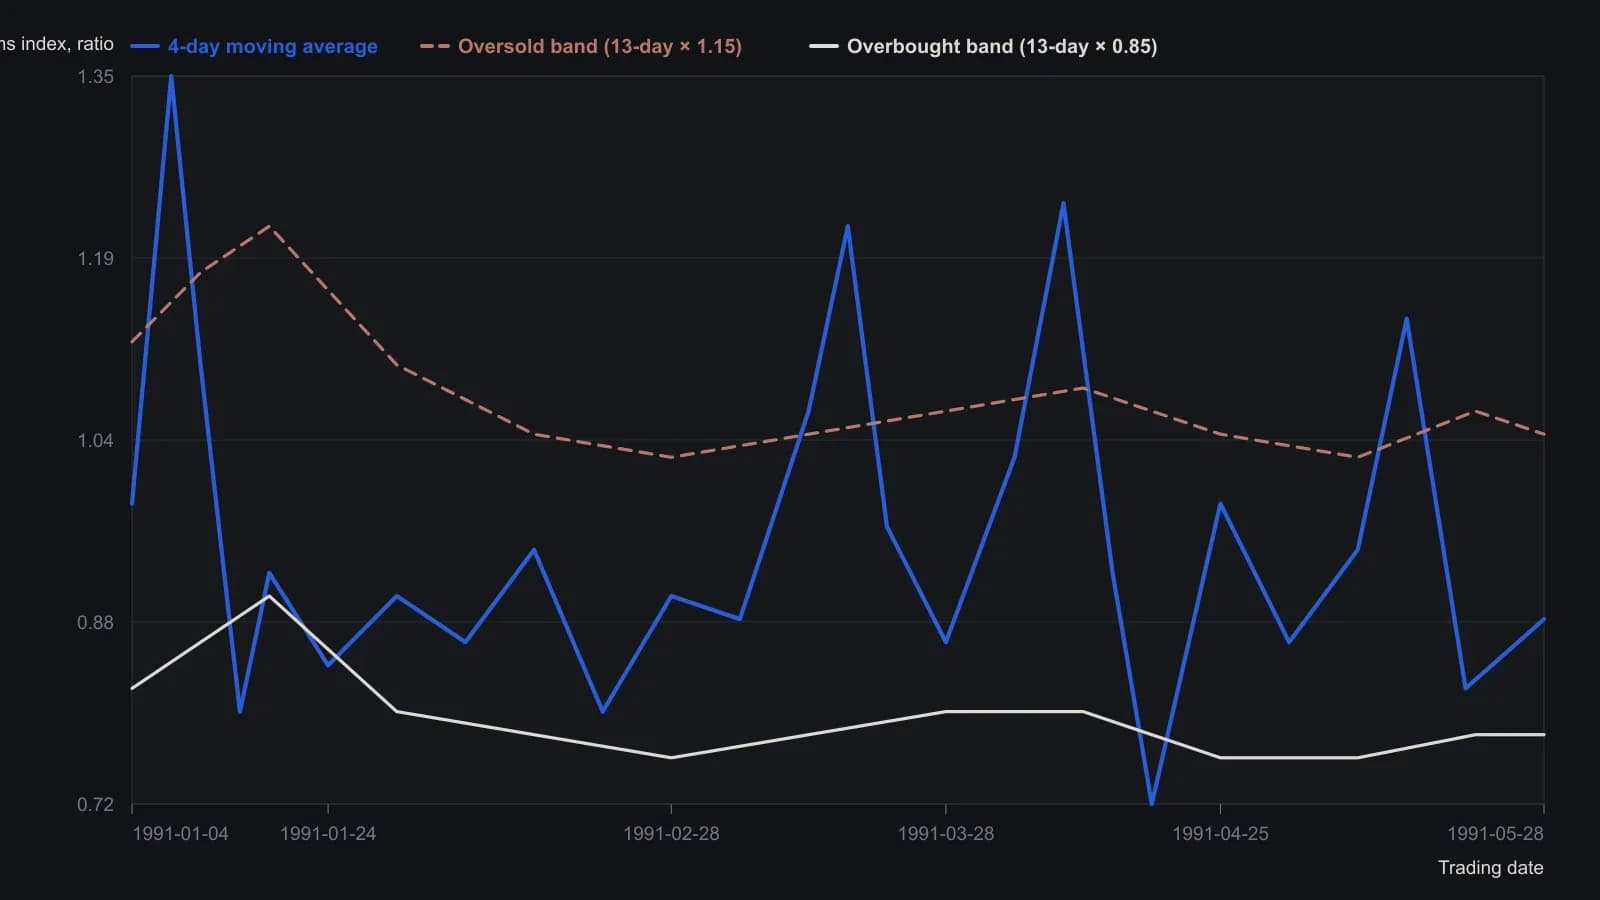
Band edges are the 13-session average of the daily Arms index scaled by 1.15 (oversold) and 0.85 (overbought). Arms called the overlay accurate but prone to whipsaw. Month ticks on the figure read January–May; the year follows the April 1991 interview. Values are approximate readings from a coarse inverted raster, rounded to 0.02.
Replace clock time with an Equivolume box
Each session is drawn as an Equivolume box with the high at the top, the low at the bottom, and volume as width. A tall thin box records wide range on light volume. A short wide box records narrow range on heavy volume. Box shape is the visual record of how much range was bought or sold per unit of volume.
Because the horizontal axis is share volume rather than clock time, turning points are measured as volume distances. That interval is a volume cycle: a measured interval of share turnover between successive highs or lows, used in place of a calendar interval because no trade means no market event. The market-level cycle discussed had grown from about 8 billion shares to about 40 billion shares and was then completing in less than a year.
Screen names, then rank ease of movement
Issue selection is confined to a 500-name universe and a daily screen for volume that is large relative to price change. About three or four names typically flag each day. After discarding those with an obvious news explanation, about one or two names a week retain the sought price-volume profile.
Ease of movement is the session midpoint change divided by the box ratio, then converted to an oscillator with a 13-day moving average. The box ratio is volume units for one session divided by range units for the same session, the denominator that turns a price midpoint change into an ease-of-movement value so issues at different price levels can be ranked on one scale. Daily charts use the zero-line cross. Longer multi-day charts use extremes because of lag.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support