1989issue C091-5
Constructing a dual-rate advance-decline oscillator
The breadth oscillator is built from the daily New York Stock Exchange advance-decline difference by subtracting a slower 5 percent trend from a faster 10 percent trend. A summation index then adds each day's oscillator value so the same dual-trend residual can be read on an intermediate-to-long horizon.
- The oscillator is built from the daily New York Stock Exchange advance-decline difference, not from a price index.
- The dual-rate trend pair applies a 10 percent trend and a 5 percent trend, treated as equivalent to a 20-day and a 40-day weighted moving average, because those rates were taken to represent the two most dominant short-to-intermediate cycle lengths.
- The breadth oscillator is the faster trend minus the slower trend; the summation index is the running total of that residual.
- Readings use the current value, that value relative to prior readings, and the patterns those readings form, together with assigned oscillator bands and explicit summation level tests.
A breadth series, not a price index
The oscillator is built from the daily New York Stock Exchange advance-decline difference rather than from a price index. That advance-decline difference is the daily count of issues closing higher minus issues closing lower, and it is the raw breadth input to every later step.
The later trends, the residual, and the running sum are all taken from that same daily difference. A price index is not substituted at any stage of the construction.
The dual-rate trend pair
A 10 percent trend and a 5 percent trend are applied to that daily difference. Those two rates were treated as equivalent to a 20-day and a 40-day weighted moving average.
The two trend rates were chosen because they were taken to represent the two most dominant short-to-intermediate cycle lengths in the breadth series. Together they form the dual-rate trend pair: a faster 10 percent smoother and a slower 5 percent smoother applied to the same advance-decline series.
The oscillator was described as forming recurring patterns and as showing a 22- to 24-week interval between important bottoming formations. That dominant-cycle spacing is the recurring interval between important oscillator bottoms used to justify the chosen smoothing rates.
Oscillator residual and summation index
The breadth oscillator is defined as the faster 10 percent trend minus the slower 5 percent trend. It is read as an overbought-oversold residual of the dual-rate construction.
A companion summation index is constructed by adding each day's oscillator value, moving the same dual-trend residual onto an intermediate-to-long horizon.
Three features used to read the oscillator
Reading the constructed oscillator uses three jointly observed features: the current value, that value relative to prior readings, and the patterns those readings form.
The constructed series was assigned numeric bands, including brief extremes beyond +150 and -150, quieter turning zones between +60 and +90 and between -50 and -100, and reference levels at +130 and -130.
McClellan Oscillator, Summation Index, and NYSE Composite, 1986–1989
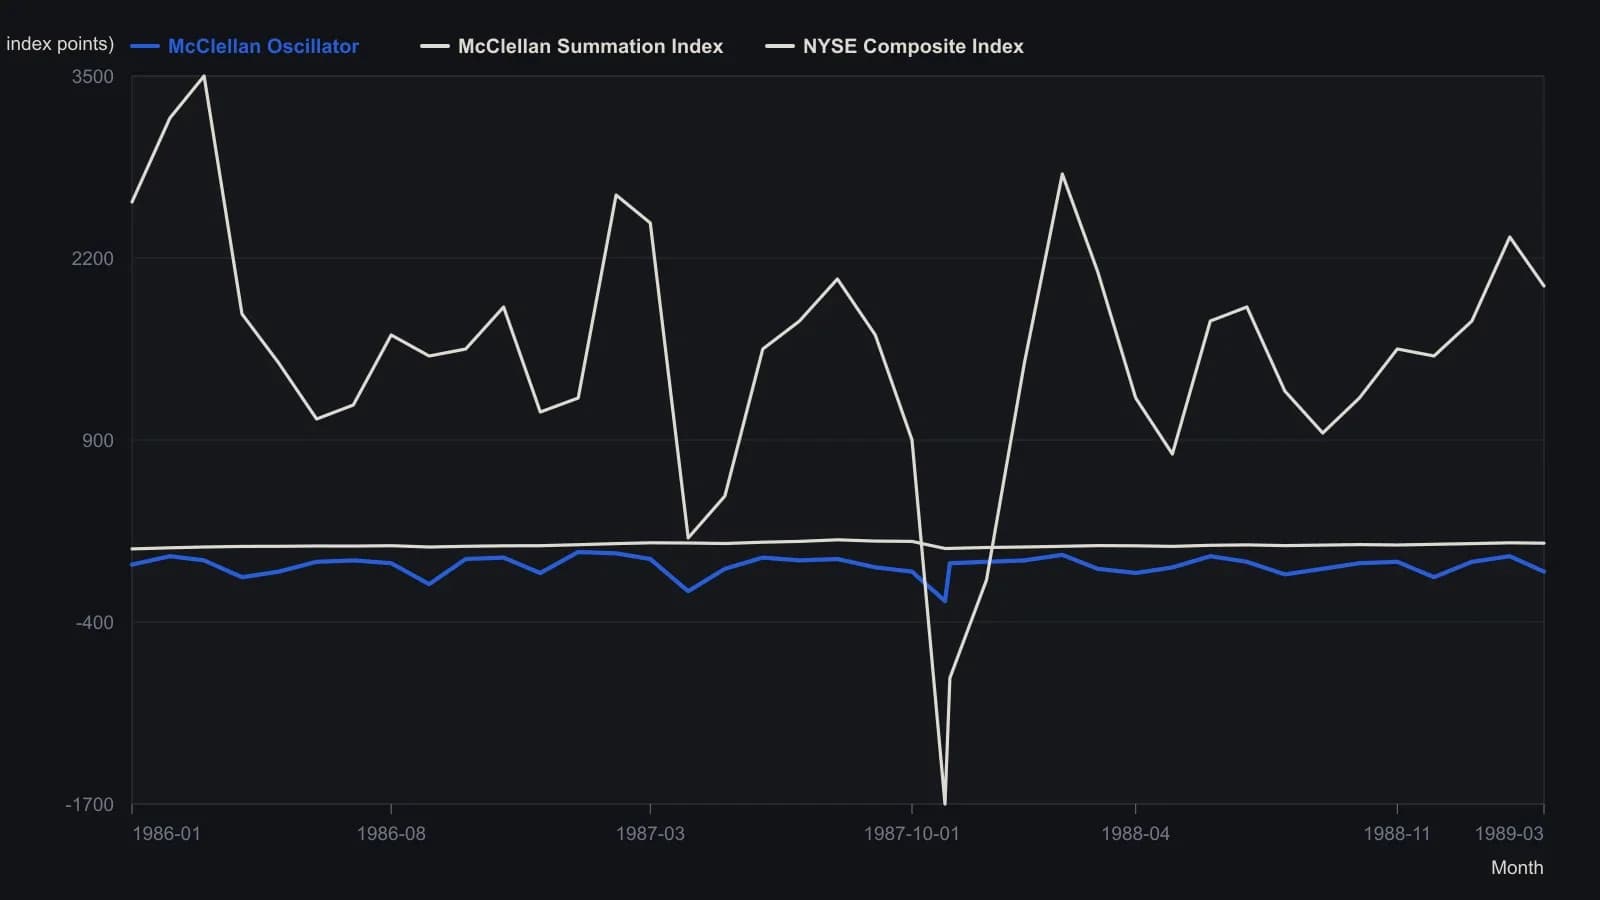
Black-and-white overlay of three series on two scales; oscillator is drawn against the annotated ±200 band (one-tenth the left-hand summation scale). Monthly samples plus crash extremes; readings are approximate to the printed grid.
Level tests on the summation index
The summation series was given explicit level tests: a rise from below -1500 through zero and above +2000, a later downward cross of zero after a reading above 2000, and a print at or below -1500.
Those constructed crossings of zero after an extreme are zero-line timing, treated as a separate timing event from the extreme itself.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support