1993issue C071-8
When advance-decline confirmation counts the wrong universe
A daily advance-decline line only answers the participation question for the issues it is allowed to count. In the early-1990s listing mix, a composite high could confirm the averages while the common-stock-only line lagged.
- A conventional daily advance-decline line is a running total of net advances minus declines, then compared with the averages to judge whether most listed issues are participating.
- After April 1991 the composite breadth universe printed three higher highs and three higher lows, while the common-stock breadth universe posted lower highs and lower lows during 1992.
- In that early-1990s mix, preferred stocks, closed-end bond funds and some utilities were described as more sensitive to the bond market than to the stock market.
- Editorial view: treat confirmation as a membership test first, because a composite advance-decline high can be an interest-rate verdict rather than proof that common stocks are participating.
What the daily line is testing
A conventional daily advance-decline line is a running total of each session's net advances minus declines. That running total is then compared with the averages to test whether most issues are participating.
A new high in the averages that is matched by a new high in the advance-decline line is treated as healthier participation. An unmatched new high is treated as more vulnerable. That mismatch is used especially when studying tops.
One listing, two breadth universes
Two parallel daily advance-decline series can be built from the same exchange listing. The common-stock breadth universe is limited to common stocks, so rate-sensitive preferreds and bond-fund shares are left out. The composite breadth universe also includes preferred stocks, closed-end funds, warrants, rights and other share types.
Through 1990 the common-stock and composite advance-decline paths tracked closely. After April 1991 they diverged, with the composite printing three higher highs and three higher lows while the common-stock series posted lower highs and lower lows during 1992.
On 10 March 1993 the composite advance-decline line stood 13.23 percent above its 17 April 1991 high, while the common-stock-only line stood 2.11 percent above that same high.
When the listing mix tracks bonds
In that early-1990s listing mix, about one-third of exchange issues were described as more sensitive to the bond market than to the stock market. That rate-sensitive listing mix included roughly 19 percent preferred stocks, 11 percent closed-end bond funds up from 2 percent five years earlier, and about 2.5 percent electric utilities.
The split between the two advance-decline series was tied to an initial-public-offering surge after the first-quarter 1991 rally together with a drop in short-term yields from above 7.5 percent to below 6 percent that encouraged issuance of closed-end bond funds. Intermarket spillover into breadth is the way that yield drop can lift preferreds and bond funds and thereby inflate a composite advance-decline line that is then read as stock-market health.
A preferred-stock advance-decline line over the two years after April 1991 closely resembled the exchange bond advance-decline line. That resemblance was used as confirmation that about 30 percent of listed shares were tracking the bond market rather than the stock market.
Confirmation from the mixed count
When the exchange composite index broke out to new highs in November 1991, the composite advance-decline line confirmed that breakout just before a sharp reversal. The common-stock-only line never confirmed it.
After the 10 March high on both advance-decline lines, the common-stock-only series began to lag. Two-to-three-month divergences between a daily advance-decline line and the major averages were described as the more reliable window in that historical sample.
NYSE composite versus common-stock-only advance-decline lines, Oct 1992–Apr 1993
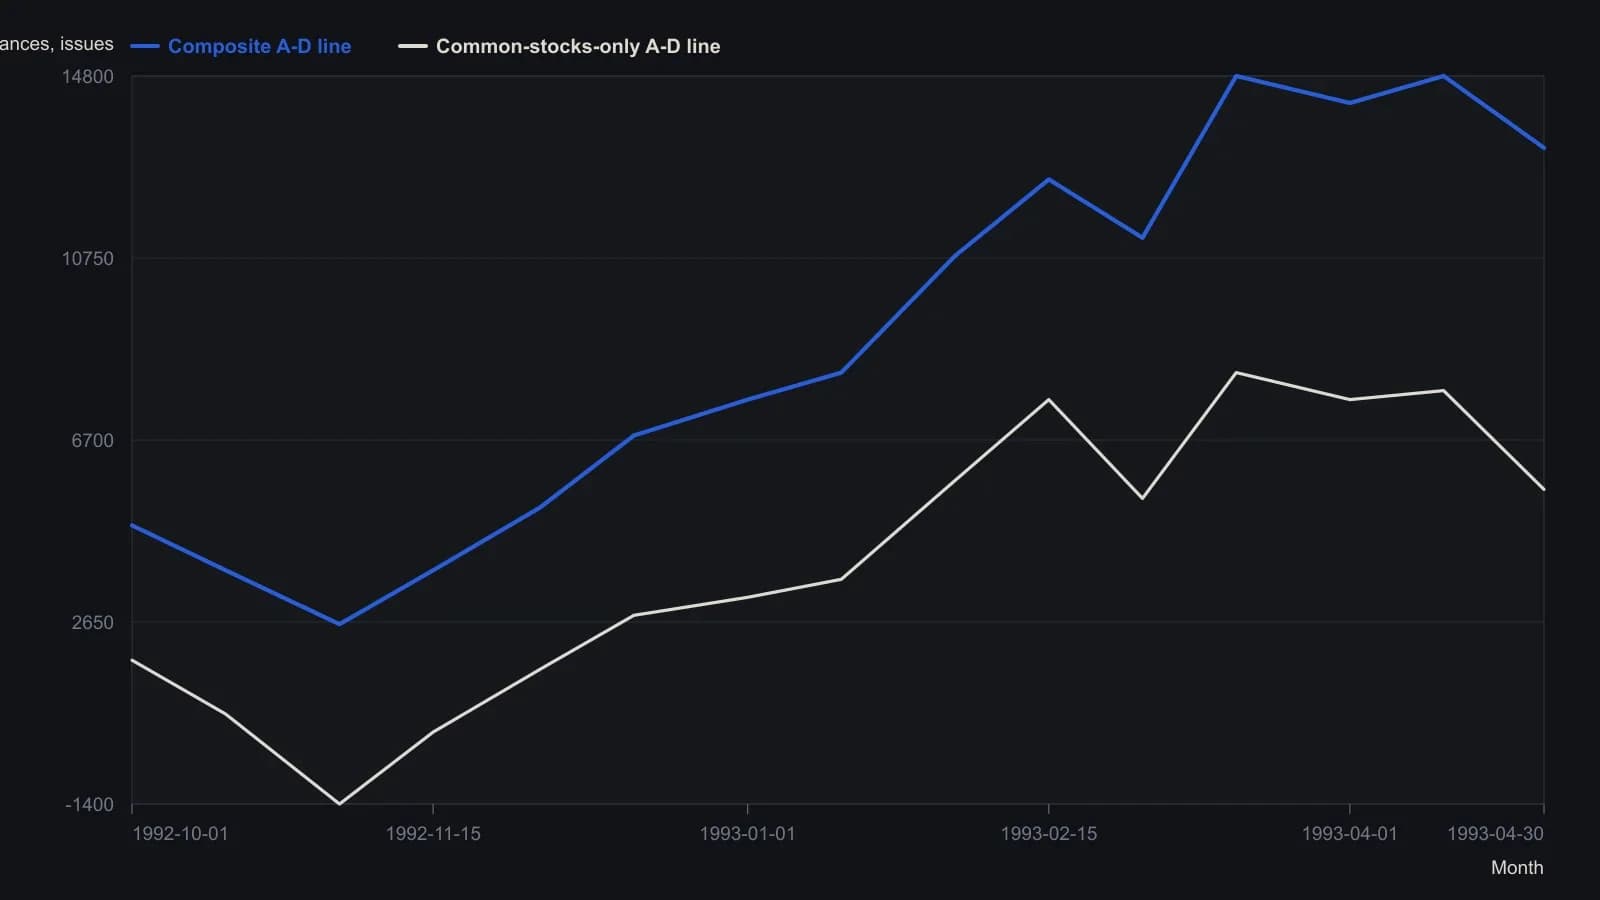
Screen print dated 2 May 1993, day stamp 930430, Full SUM with COMN ON. Cumulative net daily advances; y-values are approximate readings from the printed scale (−4000 to 16000). Month ticks are treated as month-start.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support