1995issue C051-16
Restating market breadth timing rules as ratios
A programmed recode of a multi-condition breadth timing system reproduced every published 1980-1990 buy and sell, then printed five extra signals in 1986 and 1987. Those extras became the audit that retired a premature buy clause and restated raw issue-count gates as advance/decline ratios.
- A recode that matches a published 1980-1990 signal list can still print extra buys and sells. Treat those extras as the audit, not as noise.
- A buy clause that had already produced published entries before the Dow Jones Industrial Average printed its final low was removed after the recode added another such buy on 16 October 1987.
- Gates that required more than 1000 advancing or declining NYSE issues were rewritten as advance/decline ratios so the same urgency still meant the same thing as listings rose from about 2000 to about 3000.
- A nine-to-one volume spike gate was added, a redundant buy was dropped, and the index-drawdown buy was tightened. The revised rules could not be tested before 1978 because the new-high/new-low window changed.
What the recode found
A programmed recode of a multi-condition breadth timing system reproduced every published 1980-1990 buy and sell. It also generated five additional signals in 1986 and 1987.
Market breadth here is daily participation across advancing versus declining issues and volume, read as a market-wide condition rather than a single-index price print. The work was handled as a mechanical trading system: a complete, programmable set of entry, exit, and stand-aside rules that can be recoded and checked against a published historical signal list.
Retiring a buy that tagged too early
One of those extra buys combined two specified buy conditions on 16 October 1987, the session before the Dow Jones Industrial Average fell 508 points. The same two buy conditions had already produced published entries before the Dow Jones Industrial Average printed its final low, which is why that buy clause was removed.
Deleting that clause removed the 16 October 1987 buy and changed the dates and prices of the two earlier matching buys, while leaving the rest of the signal list largely intact. A rule-based entry still fires only when a named combination of breadth, volume, and price-structure conditions is true together.
Modified Titanic cumulative DJIA points after dropping buy rule B3b
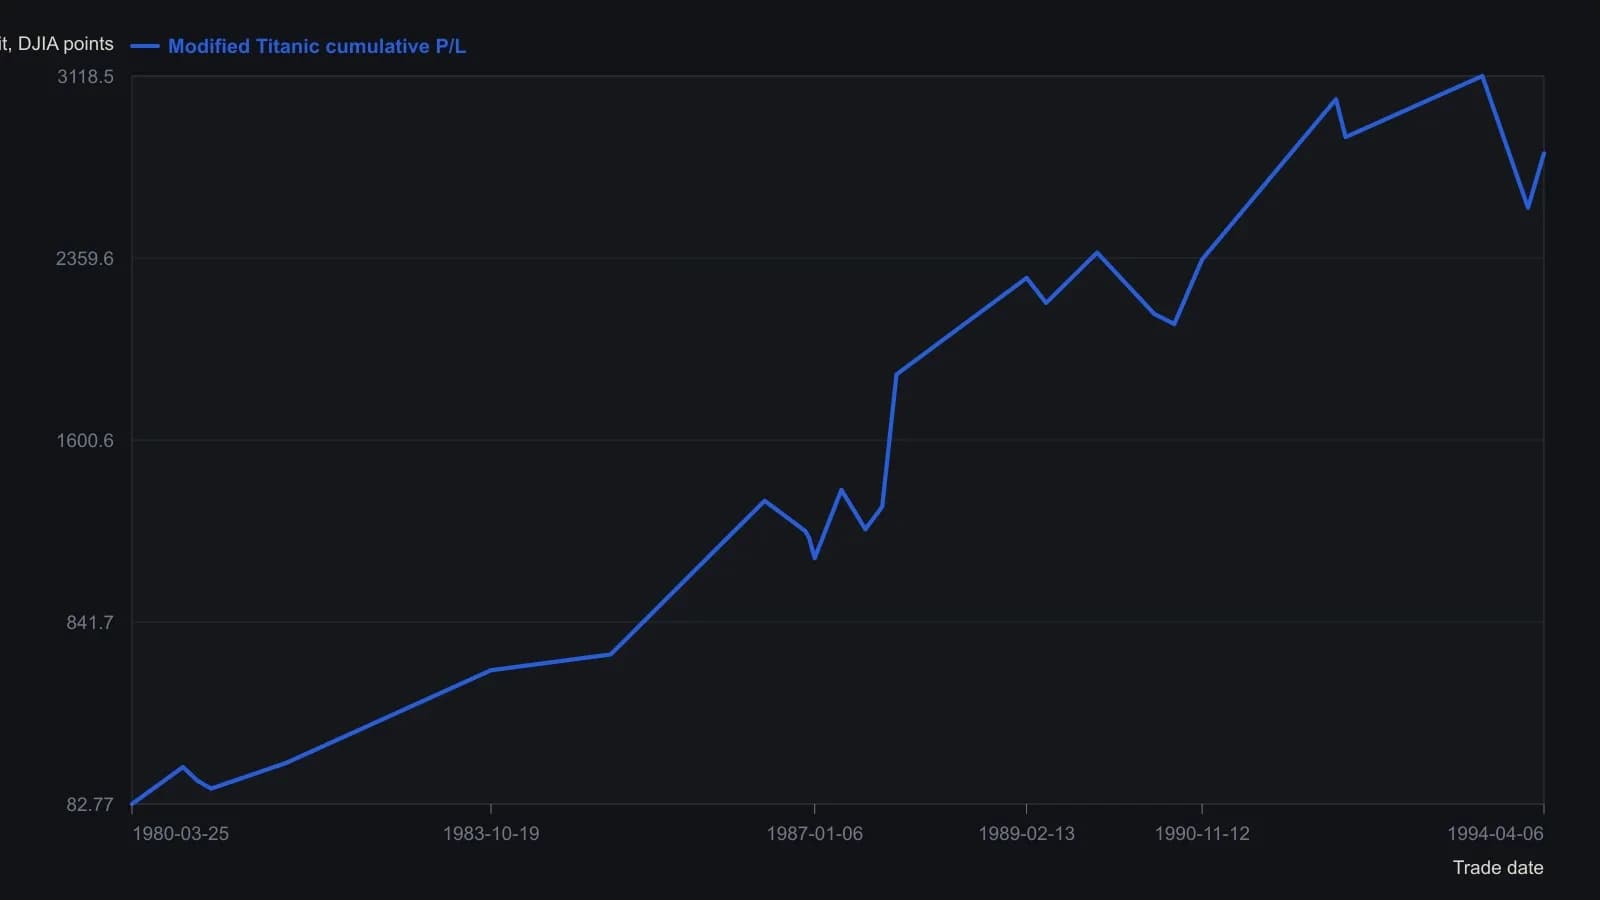
Condition B3b deleted. Extra 1986–87 signals prefixed x in the source; new F and R buys shown in brackets. Open-position P/L of 189.70 points after the last listed cover is not included. Test window DJIA daily 16 Feb 1979–20 Jan 1995.
Issue counts restated as ratios
Original clauses that required more than 1000 advancing or declining NYSE issues became easier to trip as listed issues rose from about 2000 in the 1980s to about 3000, including days when both advances and declines exceeded 1000. Those clauses were rewritten as advance/decline ratios, meaning advances divided by declines, or the reverse on the sell side, so an urgency threshold stays comparable as the number of listed issues grows.
The restated urgent-participation pair requires two consecutive sessions with advances at least twice declines, or the reverse on the sell side, and one of those sessions at least five times.
The restated persistent-participation pair requires advances at least 1.75 times declines, or the reverse, on three of four sessions. It replaces a four-of-seven lookback and stays below the urgent five-to-one bar.
Volume confirmation and the 1978 window break
A declining-volume spike greater than nine times advancing volume was added as an extra sell condition alongside two existing sells. The matching buy requires advancing volume greater than nine times declining volume and no such declining-volume spike in the prior two sessions. That volume spike gate is extra confirmation, with a two-session anti-spike filter on the buy side because selloffs more often print a down-volume climax and then a rebound.
After that volume buy was added, an earlier buy clause was dropped as redundant, and the index-drawdown buy was tightened from a 10 percent to a 9 percent decline from the 52-week high of the Dow Jones Industrial Average.
The revised rules could not be tested before 1978 because NYSE new-high and new-low counts switched on 1 January 1978 from a variable window of about two and a half to 14 1/2 months to a fixed 52-week window. That new-high/new-low window change would force a rewrite of the new-high/new-low sell condition, so it blocks a clean test of that sell on earlier dates.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support