2005issue C031-6
Intraday index-futures divergence as a three-part session hypothesis
This case study treats a five-minute index-futures session as a three-part hypothesis: wait for a stochastic extreme that price does not confirm, add size only after the next wave appears, and use market-breadth to keep, tighten, or exit rather than to start the trade.
- A buy or sell is defined only after session momentum prints an extreme that price does not confirm, and the trade is taken only after that stochastic turns.
- Session highs and lows are the reference for both the setup and the session-extreme-stop, so a failed entry is meant to exit near a defined invalidation.
- Market-breadth is refreshed on the same five-minute interval as the chart and is used after entry: hold when it strengthens, tighten when it weakens, and take profits quickly when it is near even.
- A fractional-add is allowed only after the position is already deep in profit, from a consolidation such as a flag, and each add stays smaller than the original so breakeven does not chase price.
The archive describes a futures method framed for five-minute index-futures timing. The same setups are also presented as usable to time entries on longer horizons.
Daily trend plus pre-marked support and resistance are required context for the five-minute hypothesis. Entries are intended at the opposite session extreme so a failed trade still exits near a defined invalidation.
How the setups are defined
A buy setup is defined when session momentum prints a low that price does not confirm. That mismatch is a divergence. The long is taken only after that momentum turns up.
A sell setup is defined when session momentum prints a high that price does not confirm. The short is taken only after that momentum turns down.
Session highs and lows are treated as the reference extremes for both the setup and the protective stop. On a buy setup the session-extreme-stop sits at the session low. On a sell setup it sits at the session high. The hypothesis is falsified if price later confirms the momentum extreme.
Fast and slow stochastic as the momentum gauge
Both a fast and a slow stochastic-oscillator are used as the session momentum gauge. The slow line is treated as the stricter, lower-frequency filter. The fast line is the more frequent but noisier alternative.
The archive describes the slow stochastic as producing fewer trades and a closer session-extreme-stop on the sell setup.
S&P 500 five-minute session with 20-period EMA
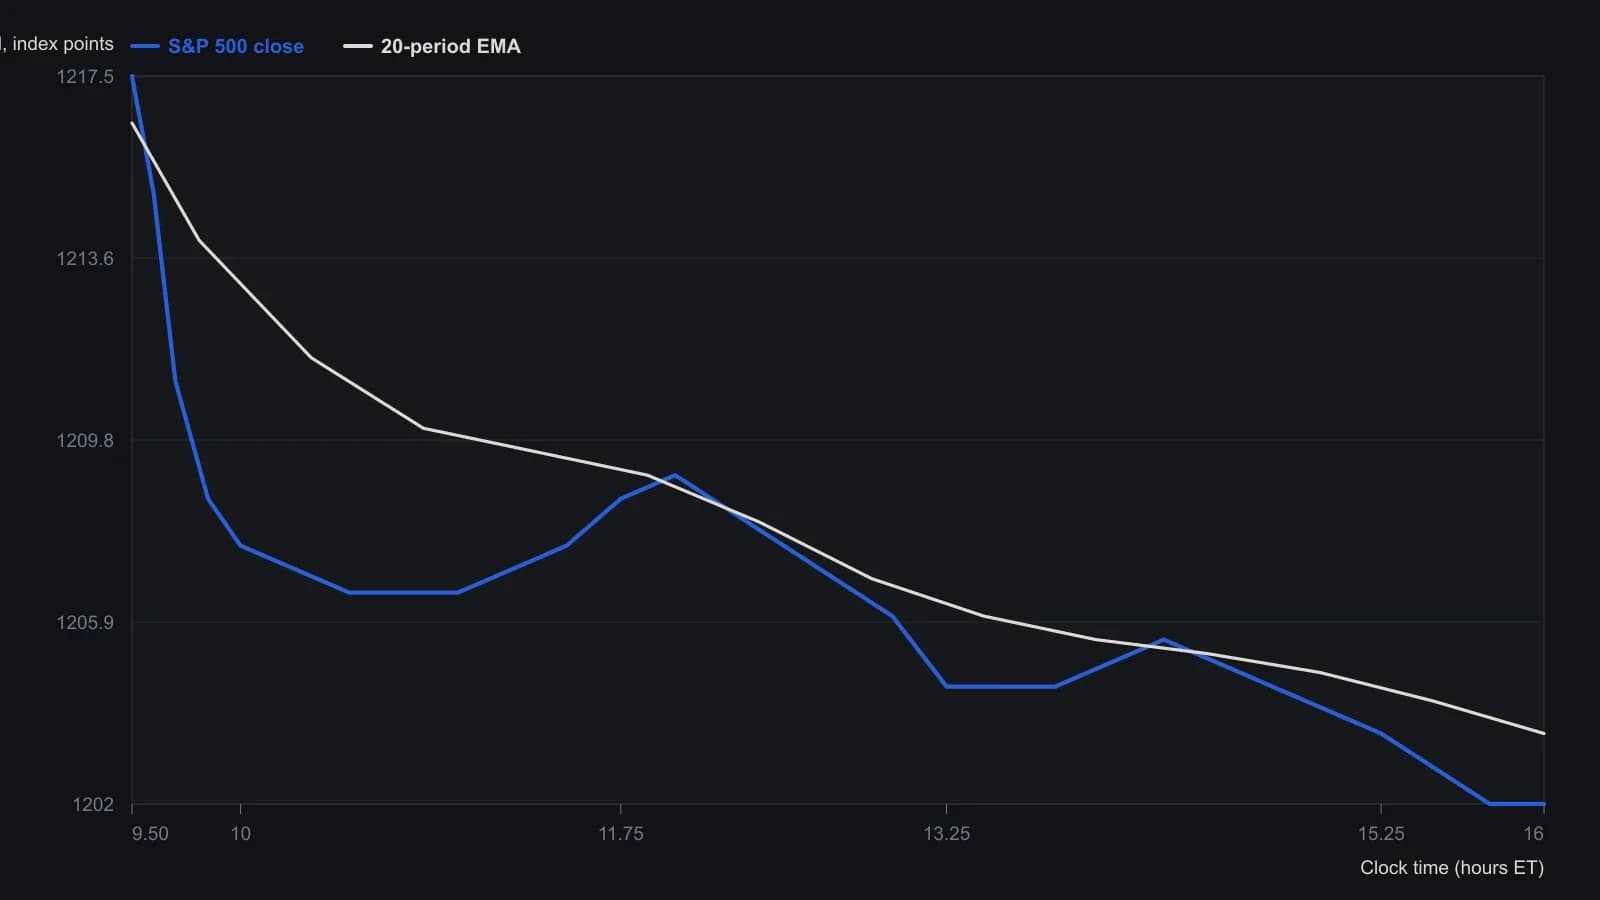
Yahoo five-minute ^GSPC with the printed 20-period EMA. Raster resolution does not support tick-level prints.
Breadth as a veto after entry
Market-breadth is refreshed on the same five-minute interval as the chart. It is used after entry, not to originate the setup.
Strengthening breadth supports holding. Weakening breadth tightens stops. A near even reading is treated as a cue to take profits quickly.
The strongest breadth confirmation described is a swing from one participation extreme to the opposite extreme rather than a reading that stays near balanced.
Adds only after the next wave
Adds are taken only after a position is already deep in profit, using consolidations such as bull or bear flags. Each add is a fractional-add, kept smaller than the original so the breakeven price does not chase the market.
Editorial note: TradersWeek maps that wait to an abc-wave. After a confirmed divergence the trade is meant to ride a three-leg sequence: an initial move, a counter-move or pause, then a continuation. The add belongs on that continuation, not on the opening print of disagreement.
When the session is choppy
When markets are described as choppy, directional size is reduced and quicker profits are preferred. The same setups can still be used to stand aside or exit without being forced into a full loss.
That choppy-regime is the counterpart of a near even participation reading. Directional adds are reduced or skipped because setups fail to extend.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support