1993issue C071-16
Constructing breadth momentum from advance-decline smoothing
Breadth momentum is built from many market components rather than from a single security’s price or volume. Advance-decline oscillators and diffusion indexes are assembled so shrinking participation can appear before a weighted average turns.
- Breadth momentum is built from many market components, so it can show participation that a weighted index may conceal.
- A shrinking set of issues joining an uptrend, or fewer issues falling as averages make a new low, is treated as a higher chance that the prevailing move is near a reversal.
- The work is grouped into advance-decline ratios, diffusion indexes of names in a defined positive trend, and a leftover set that includes high-low data and the Arms index.
- Longer smoothing spans are more stable but slower, while short spans give earlier signals at the cost of more volatility and false indications.
What breadth momentum is built from
Breadth momentum is built from many market components rather than from a single security’s price or volume. That construction can show participation that a weighted index may conceal.
A shrinking set of issues joining an uptrend, or fewer issues falling as averages make a new low, is treated as a higher chance that the prevailing move is near a reversal.
Three constructions
Breadth-momentum work is grouped into three constructions: advance-decline ratios, diffusion indexes of how many names sit in a defined positive trend, and a leftover set that includes high-low data and the Arms index.
An advance-decline oscillator
A common advance-decline oscillator is a period ratio of advancing to declining issues, often a 10-day span, smoothed with a moving average and recentered so the 50 percent midpoint maps to zero.
A 10-day advance-decline oscillator is presented as a way to warn that fewer issues are taking part in a rally or decline before the average itself turns.
Smoothing spans and unchanged issues
Longer smoothing spans are described as more stable but slower, while short spans give earlier signals at the cost of more volatility and false indications.
Including unchanged issues can keep long-horizon comparisons consistent as listings grow and can flag maturing moves when unchanged names rise as a share of the tape.
10-week and 26-week advance-decline ratios, 1989–1992
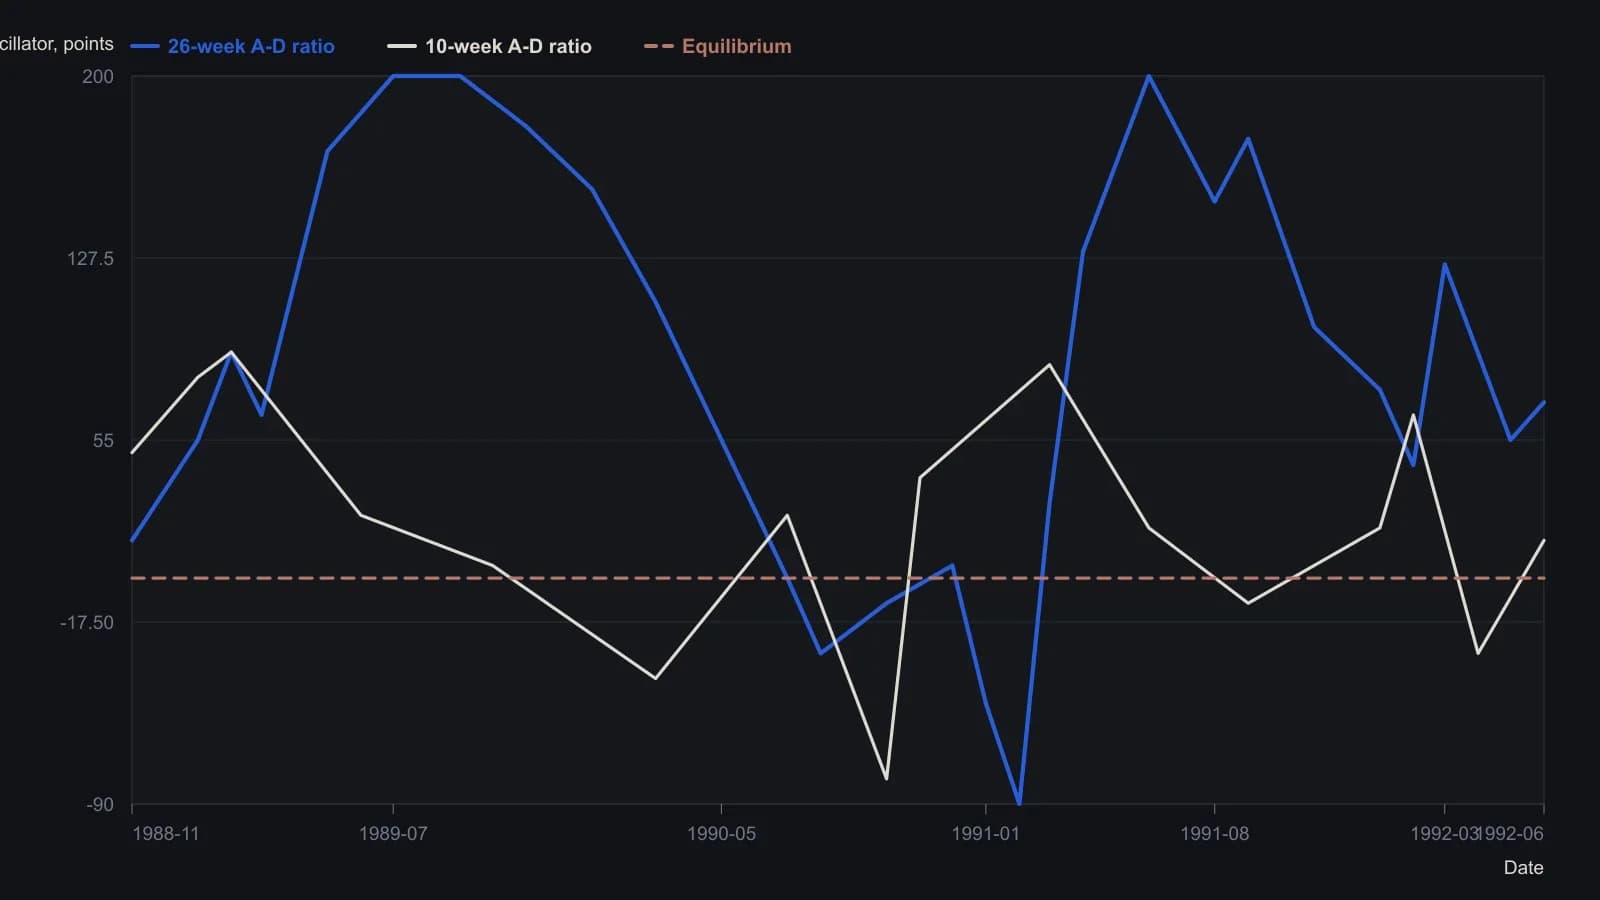
No printed data table accompanies the weekly panes. Y-values come from the labeled oscillator scales; the 26-week series appears clipped near +200 through late 1989 and again in mid-1991.
A diffusion index
A diffusion index counts the share of a basket meeting a defined trend rule, such as price above a chosen moving average or a rate of change above zero.
Splits from the average
A McClellan-style summation series can be compared with a market average for divergences. A timely trendline break aligned with an average reversal is described as a stronger combined signal.
In one weekly McClellan test, extremes near plus or minus 280, rather than zero-line crosses, were used as a five-week directional hypothesis: plus 280 pointed lower later, minus 280 pointed higher.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support