1994issue C061-3
Constructing calibrated market-breadth summation indexes
One net-advance residual can be rebuilt as an advance-decline line, a two-speed oscillator, or a calibrated summation index. Editorial reading: each rebuild is a different horizon hypothesis, not a new market fact.
- A net-advance residual is formed by pairing advancing-issue counts with declining-issue counts and subtracting the declining series from the advancing series.
- The advance-decline line is a running cumulative sum of that residual, while the two-speed oscillator is the gap between a faster and a slower exponential average of the same residual.
- The summation index accumulates that oscillator, and the calibrated summation index recombines the same two averages onto a fixed numeric scale.
- Under the zero-line convention, the sign of the calibrated index, not a price level, is the long-horizon breadth state.
Breadth as a restatement problem
Editorial reading: market breadth can be taught as a restatement problem. One net-advance residual is rebuilt in several ways, and each rebuild is a different horizon hypothesis rather than a new market fact.
The archive starts from that shared residual and then constructs a cumulative line, a two-speed gap, a running sum of that gap, and a zero-anchored recombination of the same two smoothers.
The shared net-advance residual
A net-advance series is formed by pairing advancing-issue counts with declining-issue counts and subtracting the declining series from the advancing series. That daily difference is the net-advance residual used as the shared raw input.
Later constructions in this workflow restate that residual. The archive does not introduce a second breadth series.
A cumulative line, a two-speed gap, and a summation
The advance-decline line is constructed as the cumulative sum of the net-advance residual. It is a running total of the same daily difference.
One oscillator construction subtracts a 39-period exponential moving average of the net-advance residual from a 19-period exponential moving average of the same residual. That gap is the two-speed oscillator.
An equivalent recursive construction updates two smoothers of the same advancing-minus-declining residual with constants 0.1 and 0.05, then subtracts the slower smoother from the faster smoother.
The summation index is constructed as the cumulative sum of that oscillator.
A calibrated recombination on a fixed scale
The calibrated summation index is defined as 1000 minus 9 times the 19-period exponential average plus 19 times the 39-period exponential average of the net-advance residual.
The same two recursive smoothers can be recombined as 1000 minus 9 times the 0.1 smoother plus 19 times the 0.05 smoother to produce that calibrated index.
Editorial reading: the calibration recenters the long-horizon reading on a fixed numeric scale so a later chart rule can use a zero line rather than a drifting cumulative level.
The zero-line convention
The archive treats the long-horizon breadth state as up when the calibrated summation index remains above zero.
It also treats a recent move of the summation index through zero as a negative long-horizon breadth reading.
Under the zero-line convention, the sign of the calibrated index, not a price level, is the long-horizon breadth state.
Calibrated summation index vs S&P 500, 1993–April 1994
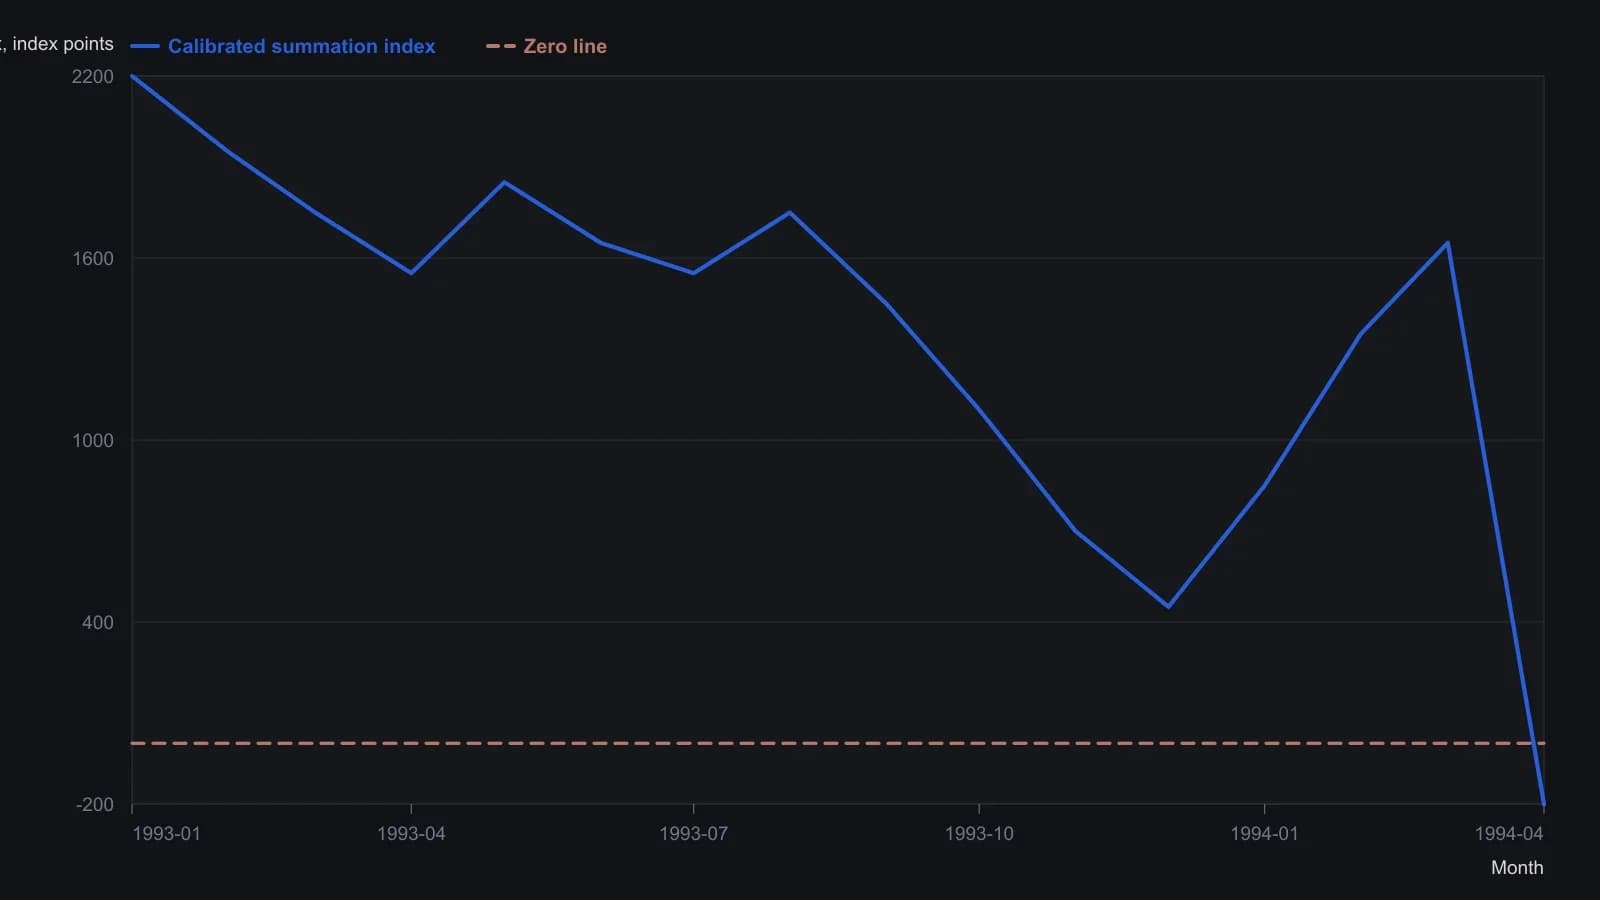
Raster is a scanned MetaStock print: y-scales are inverted on the page (higher index and higher S&P toward the bottom). Digitized at monthly anchors only; do not treat tenths as instrument precision.
All readings on this track · 71 readings
- 1987How a failed rebound, weak breadth, and cycle dates broke the 1987 bull case
- 1988Diagnosing market bottoms with breadth, divergence and averages
- 1988Diagnosing index tops with breadth divergences
- 1988Record highs versus seven-day breadth and divergence
- 1989Constructing a percentage-scaled internals composite
- 1989Constructing a weekly block-tick breadth z-score
- 1989Constructing a dual-rate advance-decline oscillator
- 1989Normalize advance-decline series for a common-scale comparison
- 1990Unchanged-issue share as a narrow-breadth case study
- 1990Evaluating daily and weekly unsigned plurality breadth
- 1990Constructing paired new-high and new-low breadth indicators
- 1990Ten-day HI/LO extremes as a long-horizon breadth signal
- 1990Confirming index cycles with breadth, volume, and waves
- 1990Index cycle gates from breadth and volume
- 1990Constructing advance-decline breadth indicators
- 1990Weekly advance-decline oscillator: weight map, extremes, and spike cycle
- 1990Price-weighted construction distorts breadth, support, and trend
- 1991A peak-sequence test from the new-highs-to-advances-ratio
- 1991Fuzzy rules that turn daily market-breadth into a session consensus
- 1991From daily breadth tallies to a weighted consensus signal
- 1991Retesting market-breadth when market structure changes
- 1991Constructing TRIN as a breadth-volume ratio
- 1991Build the market clock before you read a price bar
- 1991A construction audit of the long-horizon trading index
- 1991Independent formula timers kept as a testable combination
- 1992When identical TRIN prints come from different pairings
- 1992Grade closing tick before a next-session breadth hypothesis
- 1992Noncumulative advance-decline swing confirmation
- 1992Five-day sum construction of the trading index
- 1992Daily closing-trin extremes and next-day direction
- 1992A three-layer audit: regime, breadth, and group RSI
- 1992Constructing a nine-state trend, momentum, and breadth score
- 1993Constructing a market-volume-impact rating from nested averages
- 1993When advance-decline confirmation counts the wrong universe
- 1993Constructing breadth momentum from advance-decline smoothing
- 1993Constructing a cumulative market-thrust line
- 1994Three-horizon construction of the Haurlan index
- 1994Checklist-gated session entry in 1993 index futures
- 1994Read one advance-decline pair through three windows
- 1994Constructing calibrated market-breadth summation indexes
- 1994Constructing a two-speed advance-decline oscillator and a calibrated summation
- 1995NYSE tick extremes and candlestick reversal entries
- 1995Assembling range, breadth, and a stored stop into one procedure
- 1995Restating market breadth timing rules as ratios
- 1995Constructing breadth ratio gates after lookback drawdowns
- 1995Building a short-range breadth and price oscillator
- 1996Constructing a smoothed advance-decline trend filter
- 1996Smoothed advance-decline alerts at the 1987 and 1990 turning points
- 1996Constructing breadth, RSI, and stochastic range filters
- 1996New-high and new-low counts as a breadth construction
- 1996Constructing the four-input breadth-volume ratio
- 1996Constructing the McClellan oscillator and a calibrated summation index
- 1996Declare the oscillator seed, then calibrate only the summation index
- 1997Three-gate centered strength in market-breadth construction
- 1997Daily advance-decline and new-high new-low breadth signals
- 1999Index-fund positions as a majority-vote committee
- 2000Tick, tiki and TRIN as a three-layer session confirmation stack
- 2000Constructing an advance-decline oscillator from one listed tape
- 2001Market breadth, beta, and volume-price confirmation
- 2001Regime context from relative venue volume, breadth, and intermarket spreads
- 2002When NYSE breadth misreads operating-stock participation
- 2003Two-gate breadth divergence and a trend filter for rally tops
- 2003Market internals confirm or diverge from the index
- 2004Constructing the McClellan oscillator and summation index
- 2005Intraday index-futures divergence as a three-part session hypothesis
- 2005Breadth summation levels as a short-term signal filter
- 2005Checking trend versus range with breadth and divergence
- 2011Constructing a Nasdaq hi-lo index from highs, lows, and issues traded
- 2013Cumulative advance-decline versus a one-year average
- 2013A one-year breadth average as a participation gate
- 2015Falsifying a healthy correction with breadth and support