2004issue C051-4
Stress-test seasonal windows across regimes, then add channels
A late-February to mid-March long idea in May orange juice changed character once a longer history was put through a regime-split. A June-into-early-July window in September orange juice kept the same downward path and a Brazil frost-risk story. The preferred next step left the calendar as a research window and applied a three-price-channel breakout that could produce a stand-aside-year.
- A seasonal-window is a fixed calendar interval used as a research hypothesis, not a date-pair-rule that buys one close and exits another.
- Calendar holds shorter than one month were treated as especially likely chance alignments of two dates rather than durable seasonals.
- A genuine seasonal was expected to rest on an identifiable fundamental driver and to keep the same character in every regime-split chart.
- A window that repeated across subperiods and rested on a weather-fear-window story was then run as a three-price-channel procedure that allowed years with no entry.
A seasonal-window is a research hypothesis
A seasonal-window is a fixed calendar interval used as a research hypothesis for when a market may tend to move, not as an automatic entry and exit.
A date-pair-rule buys or sells on one calendar close and exits on another, without requiring confirmation from price structure. Calendar holds shorter than one month were treated as especially likely to be chance alignments of two dates rather than durable seasonals.
A genuine seasonal was expected to rest on an identifiable fundamental driver. A missing driver was treated as a marker of a computer-generated date pair.
The May orange juice window changed character
A late-February to mid-March long idea in May orange juice had been examined over only the most recent 17 years, even though a longer futures history was available.
Rebuilding May orange juice from 1968 through 2002 showed only a slight rise between 26 February and 17 March. A regime-split into four subperiod charts showed a downward path in 1968-76 and 1977-85, and the expected rise only in 1986-94 and 1995-2002.
Trade-by-trade review of that same May window reversed in character between 1968-85 and 1986-2002. That reversal was used to argue that a strong seasonal should appear in every subperiod chart.
A weather-fear-window that kept its shape
A June-into-early-July window in September orange juice showed a repeated downtrend on the full 1968-2002 chart and on each of four subperiod charts.
That second window was framed as a weather-fear-window: a Southern Hemisphere winter frost-risk episode in Brazil, with prices typically easing after freeze fears fade.
The calendar span stayed a research window
The preferred implementation treated the calendar span as a research window only, then applied a three-price-channel breakout procedure inside that span. The overlay used one channel for entry, one for a protective stop, and one for a trailing profit stop.
The same rules included the stand-aside-year case: a year inside the seasonal-window in which the channel-breakout rules generate no position.
Win rate of four orange-juice seasonal tests
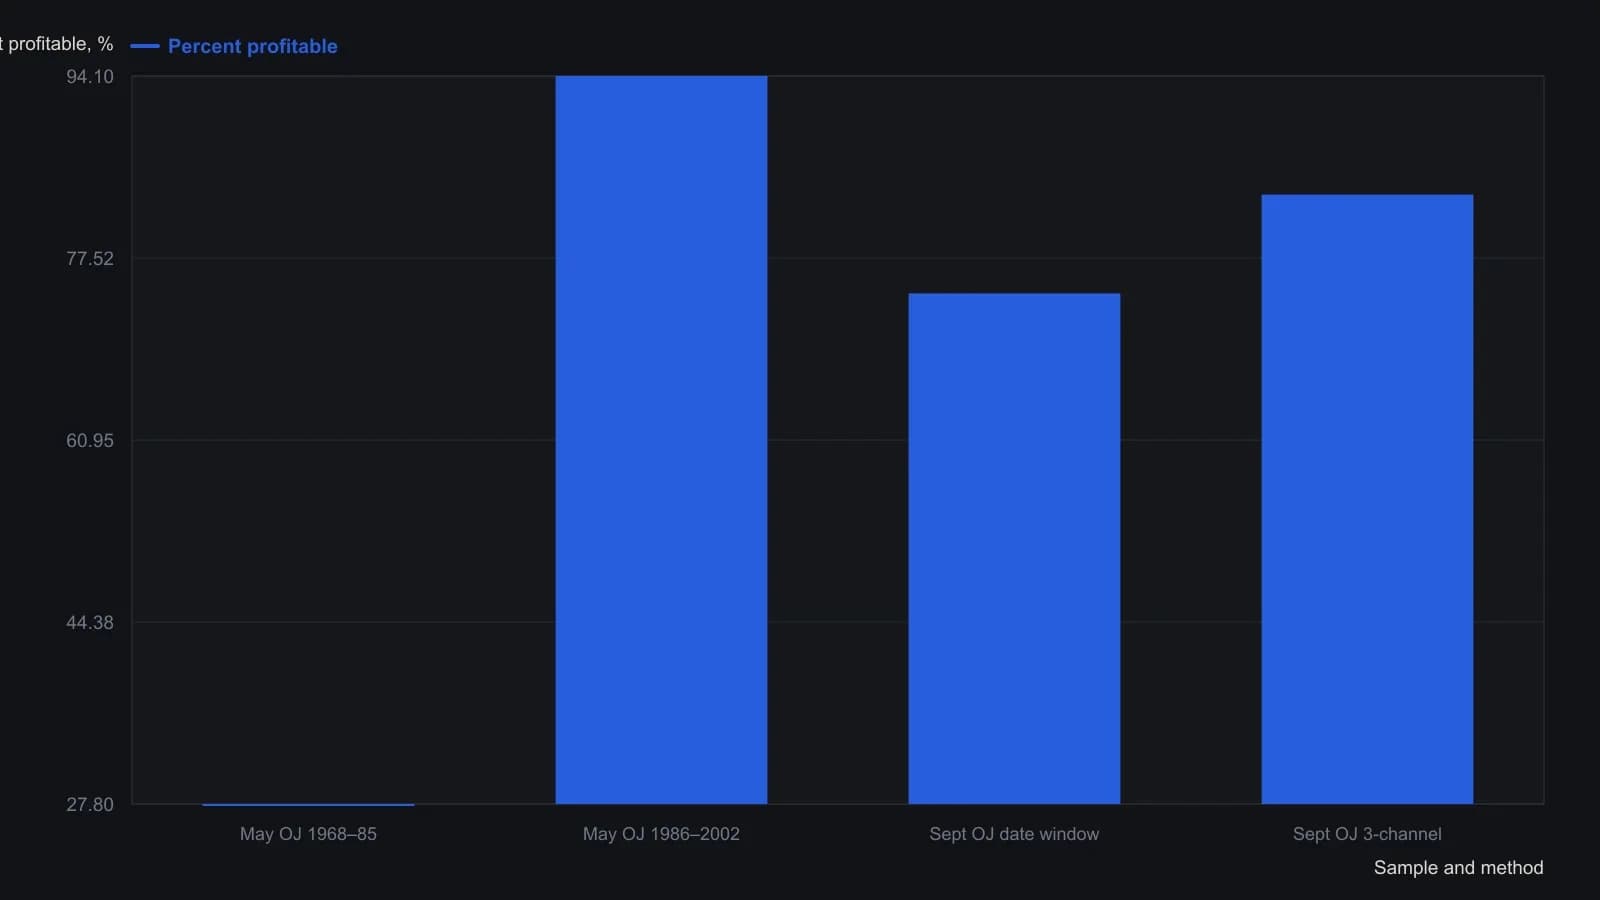
The channel-breakout test lists five stand-aside years; its 83.3 percent win rate is 25 winners out of 30 trades, not out of 35 calendar years. May and September are different contracts.
All readings on this track · 55 readings
- 1988Constructing price channels from trendlines
- 1988Three-point curved trend channel construction
- 1988Least-squares construction of channel trendlines
- 1988Three-zone price channel from quadratic smoothing
- 1989A variable-sensitivity stochastic built on three-sigma bounds
- 1989Close-minus-average oscillator for channel extremes
- 1989The six-stage hunt as a critique of one-click heroics
- 1990Fair-value gaps and a copper moving-average channel
- 1990Diversify markets, not systems, to cut trend-system variance
- 1991Constructing trendlines, price channels, and close-based breakouts
- 1991Constructing seasonal-cycle overlays with channel confirmation
- 1993Lag-compensated exponential trend channel construction
- 1993Constructing a lead-lag filter and price channel as one stack
- 1993Three stochastic warnings still need price-channel confirmation
- 1993Lead-lag smoothing for weekly trend-channel construction
- 1993Constructing zero-net-lag price channels
- 1995From a downtrend-line break to a regression channel
- 1995Validated trendline and price channel construction
- 1995Constructing price envelopes from averages, volatility, and regression
- 1996Constructing trendlines and channels from explicit swings
- 1998Fifty percent retracement as a channel regime test
- 1998Close-based channel rails as daily scenario maps
- 1999Constructing support, resistance, trendlines, and price channels
- 2001Cycle composites, price channels, and two-sided signals
- 2001Testing horizontal price channels with stops and scale
- 2002A two-stage momentum-shift and price-channel process
- 2002Wave-by-wave channel construction for Elliott counts
- 2002Affine channels as reusable trade hypotheses
- 2004Stress-test seasonal windows across regimes, then add channels
- 2004Regime permission from trendlines, channels, and range edges
- 2004Weekly-average and price-channel states on sector depositary baskets
- 2005Oil services catch-up after channel resistance breaks
- 2005Constructing a volatility-normalized cycle index
- 2005How a Darvas channel becomes a complete entry and exit procedure
- 2005Clustered Fibonacci and channel levels in news-driven forex
- 2005Treat a consolidating currency market as a time-frame problem
- 2005Channel walls that flip roles or recapture price
- 2006Stacking candlesticks, crossovers, and price channels
- 2006Failed uptrend channel breakout left the euro rangebound
- 2006Constructing a Wilson relative price channel from a range-bound strength index
- 2007Range bars change when a Bollinger squeeze counts as a breakout
- 2009One testable SPY procedure for a price channel, a trend rule, and a seasonal overlay
- 2010A gold-miner channel plan from value to false breakouts
- 2010A multi-timeframe channel from value to an overvalued zone
- 2010Asymmetric price channel construction for congested markets
- 2011Phasing many cycles at once with nested envelopes
- 2012Constructing adaptive horizontal price channels
- 2014Confirming support with trendlines, channels, and retracements
- 2015News-sentiment confirmation for support, channel, and volume tests
- 2015A three-layer permission stack: moving averages, a price channel, and weekly levels
- 2016Entropy-diff as a regime switch between trend following and a price channel
- 2017Competing rulers on a pound chart after Brexit
- 2017Test consolidation channel breakouts as one procedure
- 2020Constructing late-trend longs with a price channel, gap breakout, and trailing stop
- 2025Using IBM's multi-year price channel as a breakout teaching case