2002issue C101-5
Price regression line versus beta for index tracking
Two equities can share a beta of 1.00 and still post five-year price changes of opposite sign. The historical workflow contrasts that period-gain slope with a price-regression-line on price and index levels, then reads the coefficient of determination before treating the slope as a co-movement forecast.
- Two equities can share a beta of 1.00 and still post five-year price changes of opposite sign, so beta does not by itself establish that a series follows the market.
- Beta is the slope fitted to paired period-gains, while the price-regression-line maps a change in the index into an expected price-level change.
- The same price-on-index fit yields a coefficient of determination that shows how usable the slope is as a co-movement forecast.
- Sampling by beta near 1.0 or near 0.0 can both leave price paths linearly predictable versus the index, so the two constructions answer different questions.
Beta does not establish market following
Two equities can share a beta of 1.00 and still post five-year price changes of opposite sign. Beta does not by itself establish that a series follows the market.
Beta is constructed from paired period-gains. A period-gain is the percent change from a period's beginning value to its ending value. Each month's percent change in the instrument is plotted against the same month's percent change in the index, and beta is the slope of the fitted line. That slope describes the size and direction of deviations around average gains, not whether prices themselves track the index.
A gain-on-gain slope is not a level path
On twelve monthly gains from February 2001 through early January 2002, that gain-on-gain slope for one gold fund versus the S&P 500 was +0.227. The construction treats that figure as lower gain volatility than the index.
The price-regression-line on levels
The price-regression-line is a different slope. It is the best-fit straight line that relates an instrument's price level to the contemporaneous index level. A change in the index is scaled by this slope to form an expected price change. The slope can be positive, for the same direction as the index, or negative, for the opposite direction.
With only two dated observations, the price-regression-line idea reduces to the ratio of price change to index change. For that gold fund the two-point ratio was negative, implying opposite-direction level moves.
With more than two observations the slope is the ordinary least-squares construction. If X is the index series and Y is the instrument price series, the price-regression-line is the covariance-variance-ratio of those series: the covariance of X and Y divided by the variance of X.
The coefficient of determination of the price fit
The same fit yields a coefficient of determination, the R-squared of the price-on-index regression. It measures how much of the price variation is captured by the straight-line fit and therefore how usable the slope is as a co-movement forecast. In the gold-fund versus S&P 500 example that value was 0.30, which the source treats as a reasonably usable linear indicator of price response to index changes.
A high coefficient of determination with a positive price-regression-line slope is presented as close same-direction tracking. A high coefficient of determination with a negative slope is presented as opposite-direction tracking. A low coefficient of determination is presented as movement that is largely independent of the index.
Price regression of RYURX on the S&P 500
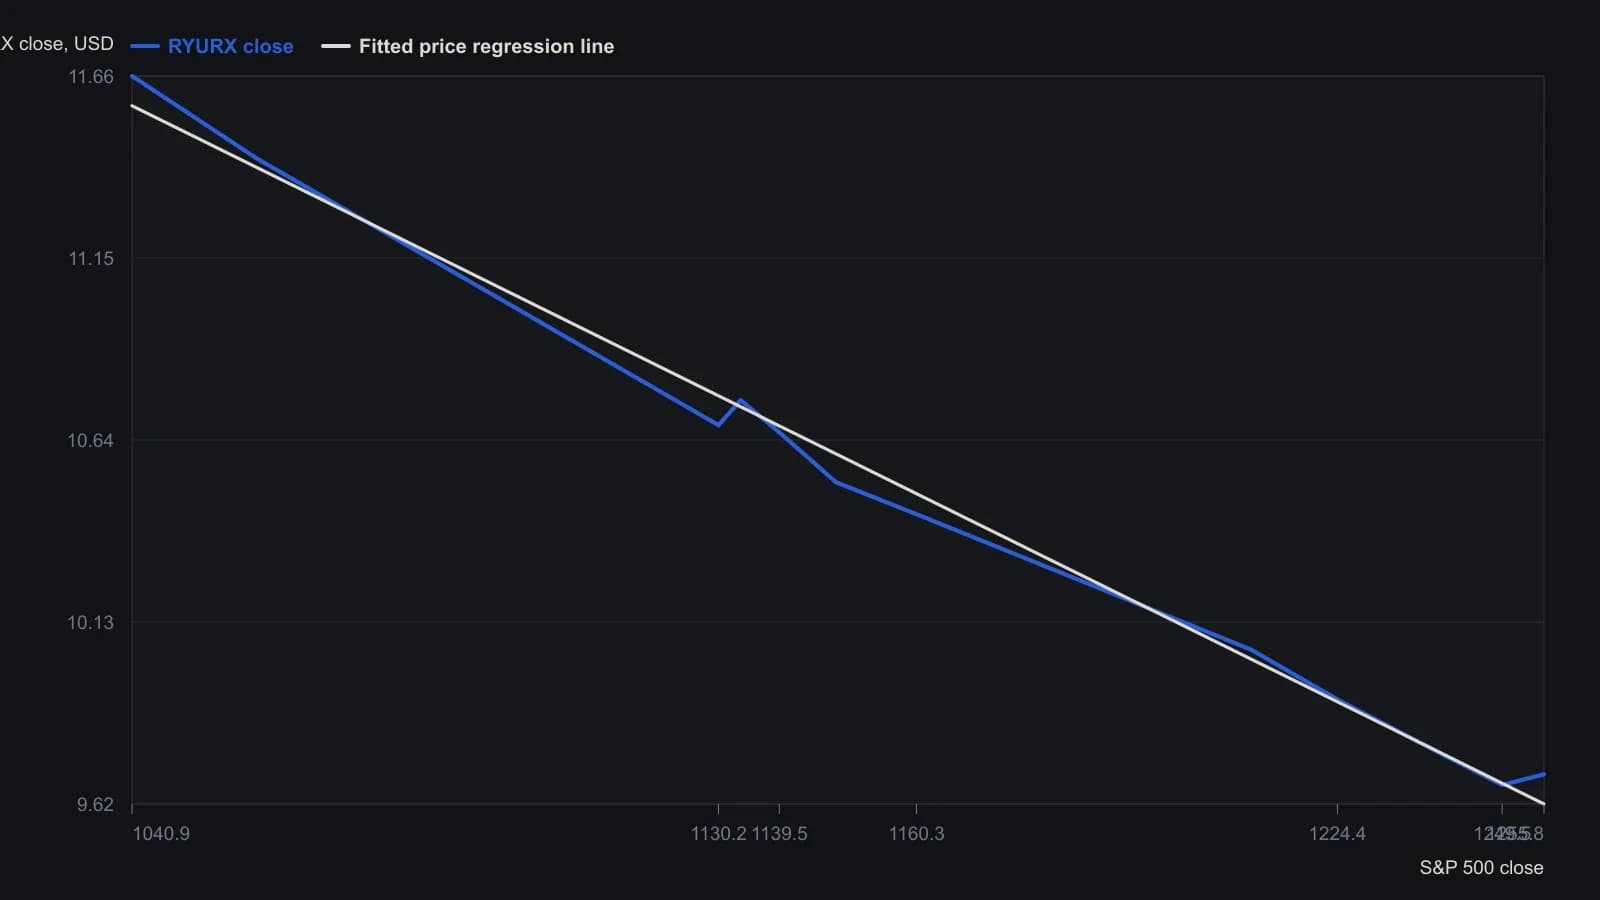
Workbook fit on 12 monthly closes, February 2001–January 2002: PRL = COVAR(X,Y)/VARP(X) = −0.00912, intercept B = 21.07013, R² = 0.993125. Points are ordered by rising S&P 500 close, not by calendar date.
The two constructions answer different questions
Sampling funds by beta near 1.0 can still produce series whose price paths are linearly predictable versus the index. Funds with beta near 0.0 can also show high price-path predictability. The two constructions answer different questions.
A spreadsheet implementation of the price-on-index line reports, for one inverse-oriented fund, a slope of about -0.00912 and a coefficient of determination of about 0.993. That pair illustrates a tight negative linear mapping from index level to price.
All readings on this track · 43 readings
- 1990Constructing dollar baselines from rates, inflation, and residuals
- 1990Constructing a nominal index value from forward earnings and fitted yield
- 1990Constructing a nominal index price from earnings and a fitted yield
- 1990Endpoint-pinned price paths are not forecasts
- 1990Constructing least-squares polynomial smoothers
- 1991Endpoint growth rates versus linear-regression consistency
- 1991Out-of-sample checks for linear growth fits
- 1991Trend as persistence, not a straight line
- 1991Quadratic trend, residual oscillator, and a secondary cycle calendar
- 1991Time-origin offset and residual-price divergence on a quadratic least-squares fit
- 1991A least-squares trendline from ordered prices
- 1992Constructing log-linear growth and reliability screens
- 1992Constructing log-linear growth-rate baselines
- 1992Next-session high, low, and close from rolling linear regression
- 1993Auditing an index price-earnings multiple with short-rate regression
- 1994Regression-seeded nested exponential price filter
- 1994Constructing the double exponential average from lag cancellation
- 1994Evaluating money supply as a linear leading-index baseline
- 1995Constructing least-squares trend channels
- 1995Linear baseline holdout checks for annual bill-rate forecasts
- 1995Projection bands from high and low regression slopes
- 1995Evaluating a least-squares end-point moving average on a known test series
- 1996Constructing an endpoint moving average from a least-squares line
- 1996Scoring equity path consistency with a k-ratio overlay
- 1996Evaluating month-end yield gaps for equity regimes
- 1996Constructing session-indexed standard error bands
- 1998Evaluating linear regression baselines for index valuation
- 1998R-squared as a two-state trend filter from a price-time fit
- 2000Second-order moving-average lag correction
- 2002Price regression line versus beta for index tracking
- 2003Regression slope with an r-squared trend confidence gate
- 2003Constructing finite-volume-element divergence with slope comparison
- 2004Building a daily score from regression, retracement, and volume
- 2004Constructing least-squares trendlines from ordered prices
- 2007Rectangle breakout targets beyond height
- 2007Confirming a price trend with regression slope and r-squared
- 2008A linear-regression angle assembled as one trend filter
- 2010A two-state swing machine from four running extremes
- 2016Score oil-complex tightness before divergence or regression
- 2017Nikkei-yen intermarket divergence as a regime case study
- 2017Constructing Calmar ratio and linear regression baselines
- 2019Pair-trade layer construction versus average-spread management
- 2020A convolution slope built from nested linear regression