1992issue C031-10
Constructing log-linear growth and reliability screens
A two-gate ranking model takes both its growth forecast and its consistency filter from one log-linear least-squares fit. Only names that pass those regression gates are then ordered by market value into a five-name annual book.
- Both earnings and dividends must show a 10% log-linear growth rate estimated from six observations covering five years.
- The same fit supplies growth reliability, and only series with an r-squared of at least 90% pass the second gate.
- Market-value rank is applied after both gates, and each concentrated annual book holds five names on a March 31 window.
- A partial-year earnings point receives a fractional time index, such as 4.25 or 4.50, so the least-squares slope matches the available quarter.
Three series and two gates
The screening construction analyzes three annual series: dividends, reported earnings, and the market value of outstanding shares.
The first gate requires both earnings and dividends to show a 10% compound growth rate estimated from six observations covering five years.
A second gate keeps only series whose growth-rate regression has at least 90% reliability, measured as the r-squared of that fit. Names that pass both regression gates are then ordered by total market value.
The log-linear growth rate
Percentage growth is constructed as the slope of a least-squares line fitted to the logarithm of the series. That quantity is the log-linear growth rate.
The least-squares slope is the estimated rate of change of the fitted line Y equals a plus bX, where X is time and Y is the logged observation.
After the series is logged, the fitted slope is converted back with an antilog, then one is subtracted and the result is scaled by 100 to recover the growth rate. Both earnings and dividends must clear the 10% test on that recovered rate.
Growth reliability as a pass-fail filter
Growth reliability is the coefficient of determination of that same log-linear fit. It is used as a pass-fail test of how steadily the series follows a constant-percentage path.
Consistency is read from that same statistic: how closely the series follows an exponential, constant-percentage path. Only fits with at least 90% reliability are kept.
Market-value rank and the annual book
Names that pass both regression gates are then ordered by total market value, defined as price times shares outstanding. That ordering is the market-value rank. It is applied only after the growth and reliability gates.
Each constructed book holds five names, the annual window is dated to March 31, and the first constructible year in the study is 1967. That holding set is the concentrated annual book.
A merger rolls into the successor name, and a going-private cash-out is placed in the highest-ranked name not already held.
Five-stock model compound return versus the index fund
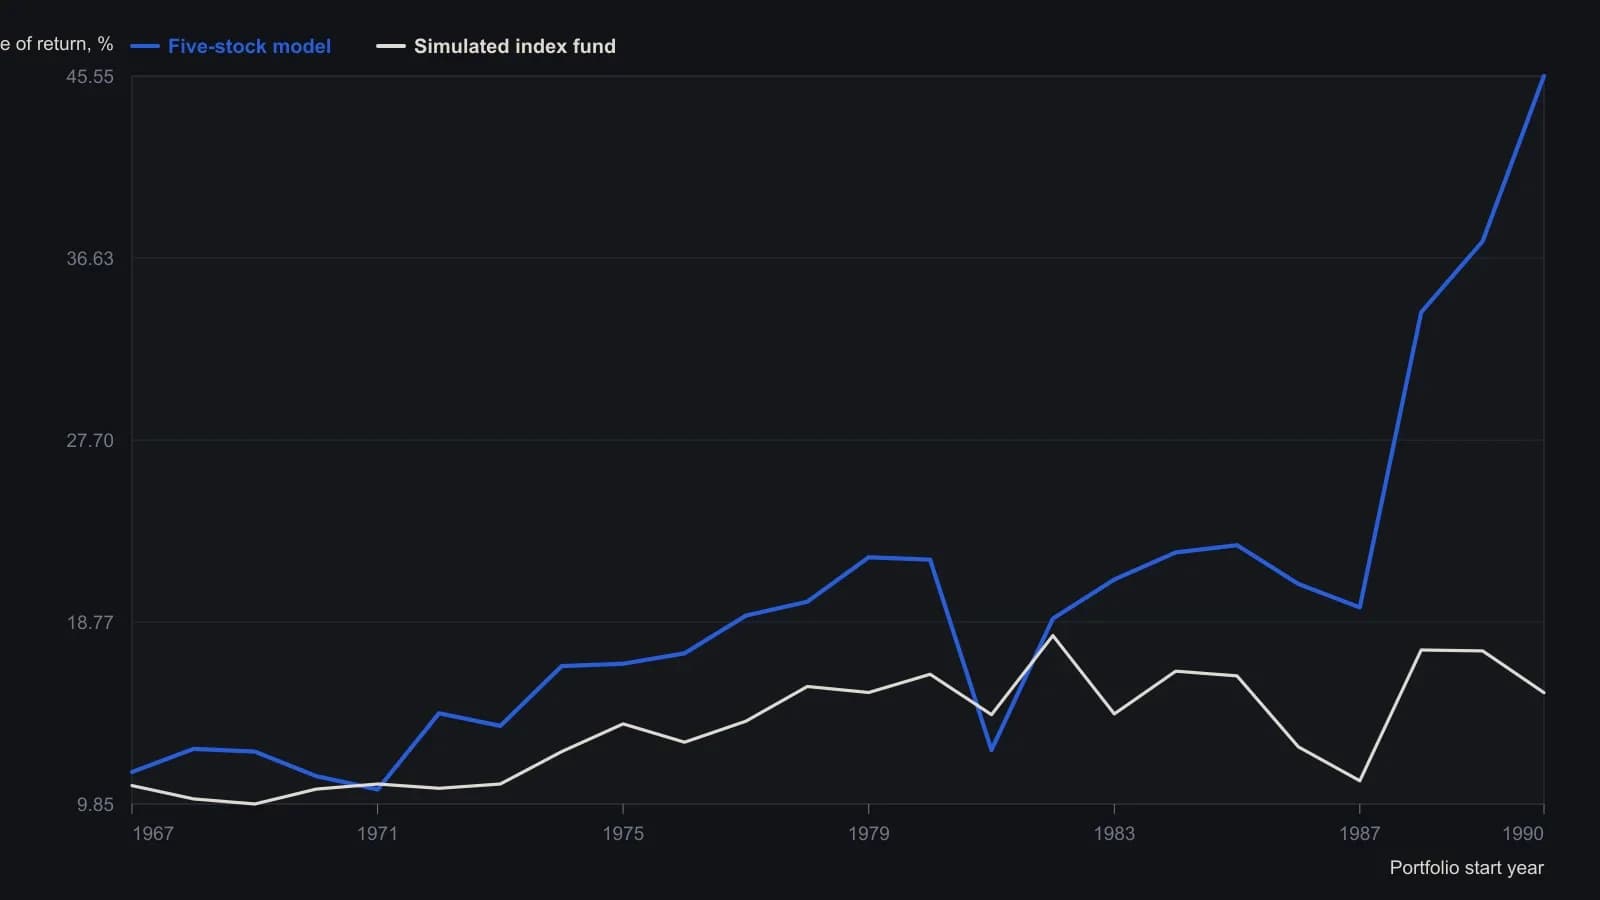
Each row is a what-if compound rate from that start year through March 1991, not a sequence of single-year returns. Mergers were rolled into the successor; private takeouts were reinvested in the next-ranked name.
A fractional time index for partial years
When the latest earnings point is a partial year, assign a fractional time index. Set its time coordinate to a non-integer year value such as 4.25 or 4.50 so the least-squares slope remains aligned with the available quarter.
All readings on this track · 43 readings
- 1990Constructing dollar baselines from rates, inflation, and residuals
- 1990Constructing a nominal index value from forward earnings and fitted yield
- 1990Constructing a nominal index price from earnings and a fitted yield
- 1990Endpoint-pinned price paths are not forecasts
- 1990Constructing least-squares polynomial smoothers
- 1991Endpoint growth rates versus linear-regression consistency
- 1991Out-of-sample checks for linear growth fits
- 1991Trend as persistence, not a straight line
- 1991Quadratic trend, residual oscillator, and a secondary cycle calendar
- 1991Time-origin offset and residual-price divergence on a quadratic least-squares fit
- 1991A least-squares trendline from ordered prices
- 1992Constructing log-linear growth and reliability screens
- 1992Constructing log-linear growth-rate baselines
- 1992Next-session high, low, and close from rolling linear regression
- 1993Auditing an index price-earnings multiple with short-rate regression
- 1994Regression-seeded nested exponential price filter
- 1994Constructing the double exponential average from lag cancellation
- 1994Evaluating money supply as a linear leading-index baseline
- 1995Constructing least-squares trend channels
- 1995Linear baseline holdout checks for annual bill-rate forecasts
- 1995Projection bands from high and low regression slopes
- 1995Evaluating a least-squares end-point moving average on a known test series
- 1996Constructing an endpoint moving average from a least-squares line
- 1996Scoring equity path consistency with a k-ratio overlay
- 1996Evaluating month-end yield gaps for equity regimes
- 1996Constructing session-indexed standard error bands
- 1998Evaluating linear regression baselines for index valuation
- 1998R-squared as a two-state trend filter from a price-time fit
- 2000Second-order moving-average lag correction
- 2002Price regression line versus beta for index tracking
- 2003Regression slope with an r-squared trend confidence gate
- 2003Constructing finite-volume-element divergence with slope comparison
- 2004Building a daily score from regression, retracement, and volume
- 2004Constructing least-squares trendlines from ordered prices
- 2007Rectangle breakout targets beyond height
- 2007Confirming a price trend with regression slope and r-squared
- 2008A linear-regression angle assembled as one trend filter
- 2010A two-state swing machine from four running extremes
- 2016Score oil-complex tightness before divergence or regression
- 2017Nikkei-yen intermarket divergence as a regime case study
- 2017Constructing Calmar ratio and linear regression baselines
- 2019Pair-trade layer construction versus average-spread management
- 2020A convolution slope built from nested linear regression