1992issue C051-11
Next-session high, low, and close from rolling linear regression
A short linear-regression on ordered session prices returns slope-and-intercept values that project the next high, low, and close. r-squared and the forecast-oscillator then record whether that line still describes the print.
- A five-session-lookback is the short-horizon default for estimating slope-and-intercept. When the next-session index is 6, the next close is written as 6m + c.
- Separate linear-regression fits on high, low, and close form a forecast-band that can serve as a range scale and as action levels a few ticks beyond the projected high or low.
- Keep the projections in use only while r-squared exceeds 0.1. A forecast-oscillator zero crossing, confirmed by a drop in r-squared and a change in slope, is read as an early trend-change warning.
- A point-versus-interval-forecast choice can replace the single next-session value with an interval that widens with residual variation and the chosen confidence level.
A line written from ordered sessions
A linear fit of the form Y = mX + c is estimated from known paired observations. The fit returns slope-and-intercept values m and c, while r-squared from 0 to 1 is the share of Y variation explained by that line.
The independent index X is an ordered session count, and Y is the dependent price series being projected.
The five-session default
A rolling five-session-lookback is the short-horizon default. At least 10 days of history is preferred, and any lookback is allowed.
When the independent index for the next session is 6, the next close is written as 6m + c.
High, low, and close as a forecast-band
Separate regressions on high, low, and close produce a next-session forecast-band. That trio can serve as a range scale and as action levels a few ticks beyond the projected high or low.
r-squared gates on the forecast
Interpretive thresholds keep the forecasts in use only when r-squared exceeds 0.1. r-squared below 0.1 is treated as a warning that a trend change is near. r-squared above 0.6 is treated as a trend in place.
The forecast-oscillator
The forecast-oscillator %F equals 100 times (realized value minus the one-step forecast) divided by the realized value. Its sign records whether the market printed above or below the projection.
A zero crossing of %F is read as an early trend-change warning and is confirmed with a drop in r-squared and a change in regression slope. Subsequent direction is described as usually following the sign of %F.
Illustrated equity-index and cash wheat series
On the illustrated equity-index series, the forecast lagged price during trends. Close-versus-forecast crossings appeared several sessions before direction changes. Near-zero r-squared marked trendless stretches, and strong trends coincided with high r-squared and slope.
The same high-low-close construction is applied to a cash wheat series, where %F zero crossings and r-squared readings below 0.1 are used as the same trend-change diagnostics.
Spreadsheet steps and an interval form
A spreadsheet implementation estimates c, m, and r-squared from five closes against fixed sequential X values. It writes the next close as c + 6m and computes %F as (actual close minus forecast) divided by actual close times 100.
A point forecast can be replaced by an interval that widens with residual variation and the chosen confidence level. The construction is described as more applicable in trending or range-bound markets than in volatile, choppy action.
OEX close versus the five-session regression forecast
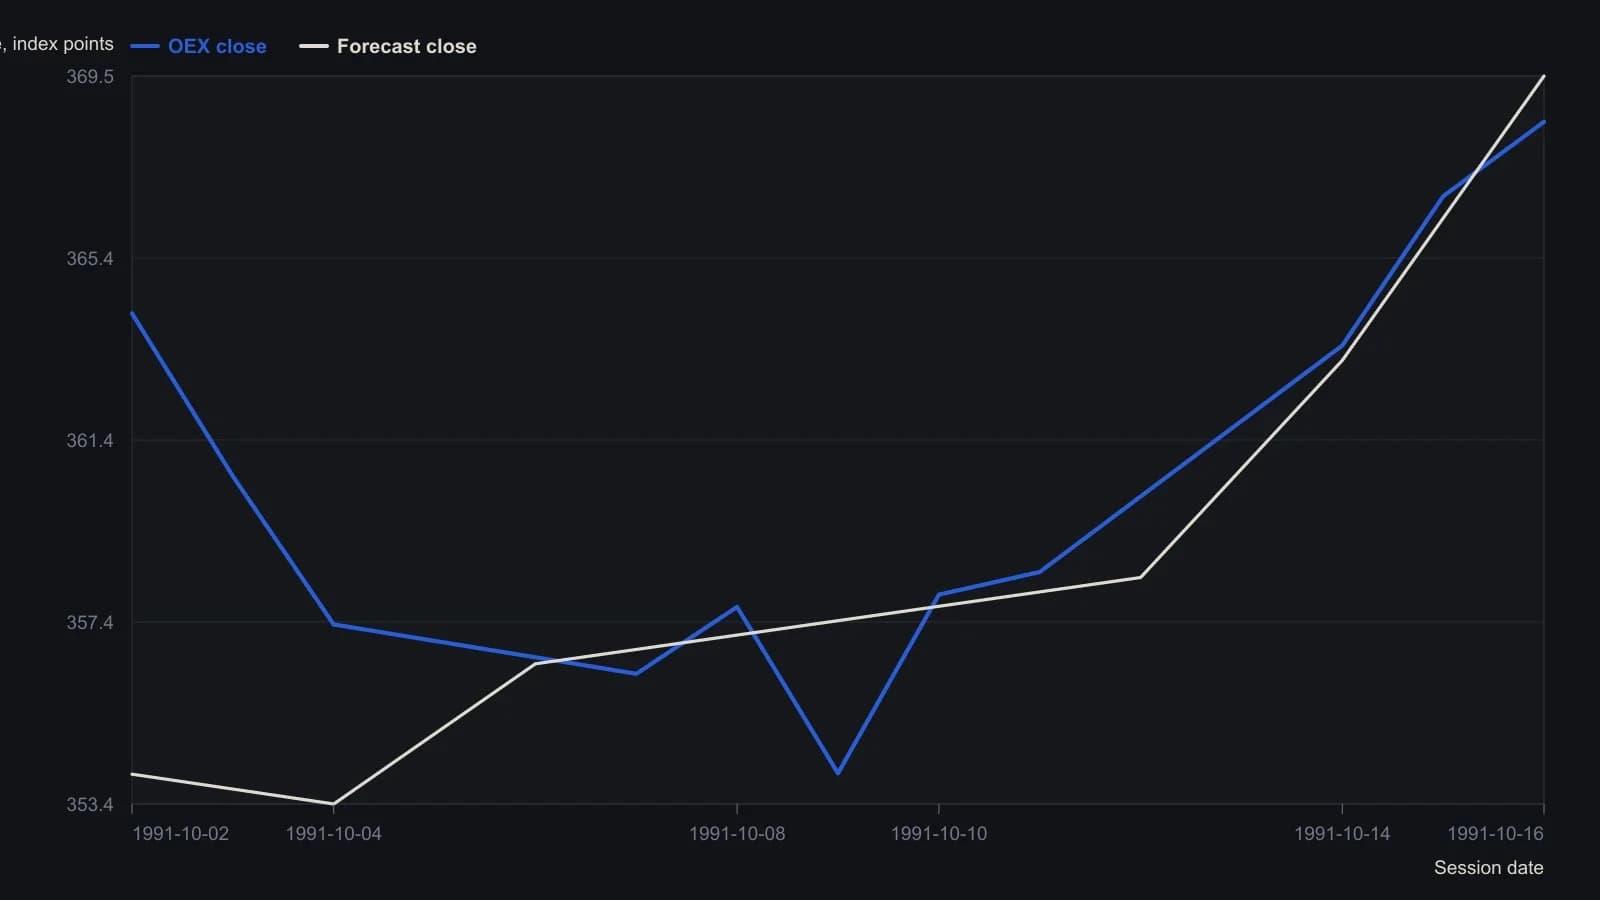
Each window is five sessions with X numbered 1 through 5; the next close is always written as 6m + c on the following row. The first forecast therefore lands on 9 October.
All readings on this track · 43 readings
- 1990Constructing dollar baselines from rates, inflation, and residuals
- 1990Constructing a nominal index value from forward earnings and fitted yield
- 1990Constructing a nominal index price from earnings and a fitted yield
- 1990Endpoint-pinned price paths are not forecasts
- 1990Constructing least-squares polynomial smoothers
- 1991Endpoint growth rates versus linear-regression consistency
- 1991Out-of-sample checks for linear growth fits
- 1991Trend as persistence, not a straight line
- 1991Quadratic trend, residual oscillator, and a secondary cycle calendar
- 1991Time-origin offset and residual-price divergence on a quadratic least-squares fit
- 1991A least-squares trendline from ordered prices
- 1992Constructing log-linear growth and reliability screens
- 1992Constructing log-linear growth-rate baselines
- 1992Next-session high, low, and close from rolling linear regression
- 1993Auditing an index price-earnings multiple with short-rate regression
- 1994Regression-seeded nested exponential price filter
- 1994Constructing the double exponential average from lag cancellation
- 1994Evaluating money supply as a linear leading-index baseline
- 1995Constructing least-squares trend channels
- 1995Linear baseline holdout checks for annual bill-rate forecasts
- 1995Projection bands from high and low regression slopes
- 1995Evaluating a least-squares end-point moving average on a known test series
- 1996Constructing an endpoint moving average from a least-squares line
- 1996Scoring equity path consistency with a k-ratio overlay
- 1996Evaluating month-end yield gaps for equity regimes
- 1996Constructing session-indexed standard error bands
- 1998Evaluating linear regression baselines for index valuation
- 1998R-squared as a two-state trend filter from a price-time fit
- 2000Second-order moving-average lag correction
- 2002Price regression line versus beta for index tracking
- 2003Regression slope with an r-squared trend confidence gate
- 2003Constructing finite-volume-element divergence with slope comparison
- 2004Building a daily score from regression, retracement, and volume
- 2004Constructing least-squares trendlines from ordered prices
- 2007Rectangle breakout targets beyond height
- 2007Confirming a price trend with regression slope and r-squared
- 2008A linear-regression angle assembled as one trend filter
- 2010A two-state swing machine from four running extremes
- 2016Score oil-complex tightness before divergence or regression
- 2017Nikkei-yen intermarket divergence as a regime case study
- 2017Constructing Calmar ratio and linear regression baselines
- 2019Pair-trade layer construction versus average-spread management
- 2020A convolution slope built from nested linear regression