2017issue C1147
Constructing Calmar ratio and linear regression baselines
Assemble a monthly Calmar ratio over a 36-month window and a least-squares linear forecast from the same ordered market series. Editorial guidance is to hold both specifications fixed when an in-sample baseline is compared with a later out-of-sample result.
- The Calmar ratio is constructed on a monthly sampling interval by dividing average return over the most recent 36 months by maximum drawdown over that same window.
- A negative constructed Calmar ratio indicates that the evaluated system or trader recorded a negative result over the last three years.
- Linear regression relates an independent variable to a dependent variable so the fitted equation can forecast later values, with the least-squares method placing the curve to minimize the sum of squared deviations.
- Editorial guidance is to keep both specifications unchanged when the in-sample baseline is compared with a later out-of-sample result.
Two constructions from one series
Editorial framing: assemble two complementary quantitative constructions from the same ordered market series, then hold those specifications fixed when an in-sample baseline is compared with a later out-of-sample result.
The first construction is the Calmar ratio, a monthly risk-adjusted score formed by dividing average return over the last 36 months by maximum drawdown over that same window. The second is linear regression, a fitted mapping from an independent series onto a dependent series that yields a forecast of later values.
SPY 217-222 call debit spread: quote-type returns on May 1
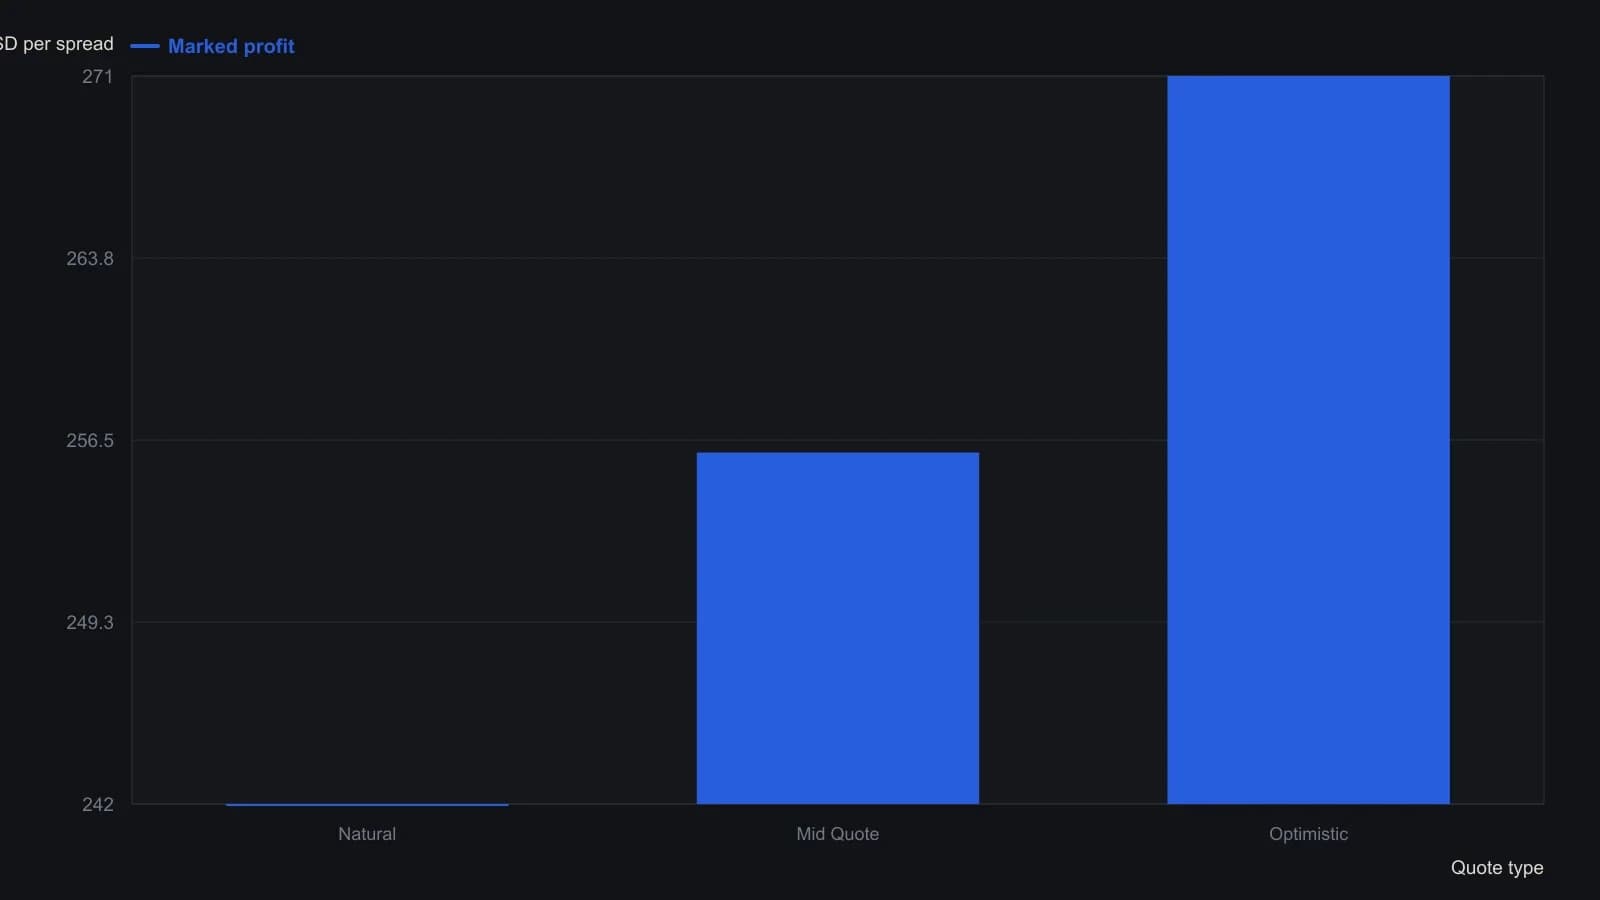
Entry debit, max profit and max risk are identical across quote types; only the marked profit and the greeks change. Downside and upside breakevens are both 219.30.
Constructing the Calmar ratio
The Calmar ratio is constructed by dividing the average rate of return over the most recent 36 months by the maximum drawdown recorded over that same period. Construction of the Calmar ratio is usually carried out on a monthly sampling interval.
Maximum drawdown is the drawdown figure that appears in the Calmar denominator over the same 36-month window used for average return. Where a mean is needed, it is the sum of observed values divided by the number of observations in the sample.
Constructing the linear forecast
Linear regression is constructed by relating an independent variable to a dependent variable so the fitted equation can be used as a forecast of later values.
A least-squares construction places the fitted curve so that the sum of squared deviations from the observed points is minimized.
After a regression is fitted, R-squared reports the share of variation in the dependent series accounted for by the fitted equation and serves as a relative measure of fit.
Pearson's correlation measures linear association between two series and takes values between +1 and -1, from total negative association to total positive association.
Keeping the specifications fixed
Editorial guidance: once the Calmar window, the monthly sampling interval, the independent and dependent series, and the least-squares fitting rule are chosen, keep those specifications unchanged when the in-sample baseline is compared with a later out-of-sample result.
Editorial reading: the Calmar ratio and the linear forecast are complementary views of the same ordered series. One is a 36-month risk-adjusted score. The other is a fitted forecast whose relative fit is described by R-squared and whose linear association can be described by Pearson's correlation.
All readings on this track · 43 readings
- 1990Constructing dollar baselines from rates, inflation, and residuals
- 1990Constructing a nominal index value from forward earnings and fitted yield
- 1990Constructing a nominal index price from earnings and a fitted yield
- 1990Endpoint-pinned price paths are not forecasts
- 1990Constructing least-squares polynomial smoothers
- 1991Endpoint growth rates versus linear-regression consistency
- 1991Out-of-sample checks for linear growth fits
- 1991Trend as persistence, not a straight line
- 1991Quadratic trend, residual oscillator, and a secondary cycle calendar
- 1991Time-origin offset and residual-price divergence on a quadratic least-squares fit
- 1991A least-squares trendline from ordered prices
- 1992Constructing log-linear growth and reliability screens
- 1992Constructing log-linear growth-rate baselines
- 1992Next-session high, low, and close from rolling linear regression
- 1993Auditing an index price-earnings multiple with short-rate regression
- 1994Regression-seeded nested exponential price filter
- 1994Constructing the double exponential average from lag cancellation
- 1994Evaluating money supply as a linear leading-index baseline
- 1995Constructing least-squares trend channels
- 1995Linear baseline holdout checks for annual bill-rate forecasts
- 1995Projection bands from high and low regression slopes
- 1995Evaluating a least-squares end-point moving average on a known test series
- 1996Constructing an endpoint moving average from a least-squares line
- 1996Scoring equity path consistency with a k-ratio overlay
- 1996Evaluating month-end yield gaps for equity regimes
- 1996Constructing session-indexed standard error bands
- 1998Evaluating linear regression baselines for index valuation
- 1998R-squared as a two-state trend filter from a price-time fit
- 2000Second-order moving-average lag correction
- 2002Price regression line versus beta for index tracking
- 2003Regression slope with an r-squared trend confidence gate
- 2003Constructing finite-volume-element divergence with slope comparison
- 2004Building a daily score from regression, retracement, and volume
- 2004Constructing least-squares trendlines from ordered prices
- 2007Rectangle breakout targets beyond height
- 2007Confirming a price trend with regression slope and r-squared
- 2008A linear-regression angle assembled as one trend filter
- 2010A two-state swing machine from four running extremes
- 2016Score oil-complex tightness before divergence or regression
- 2017Nikkei-yen intermarket divergence as a regime case study
- 2017Constructing Calmar ratio and linear regression baselines
- 2019Pair-trade layer construction versus average-spread management
- 2020A convolution slope built from nested linear regression