1984issue C031-6
Constructing the slow stochastic from a five-session range
The stochastic oscillator places the close inside a five-session high-low window and plots the result as K and %D. Regular and slow readings can be rebuilt from a sixteen-column worksheet, after which %D-price divergences and higher-horizon trendlines become written rules for which daily crosses are allowed to stand.
- K and %D locate the close inside a five-session high-low window so the two series can mark stretched versus depleted conditions.
- Regular K and regular %D are taken from that window. The slow construction sets slow K equal to regular %D and sets slow %D equal to a three-session average of regular %D.
- A K cross of %D is the operational cue. Price-%D divergences and weekly or monthly trendlines decide which daily crosses are allowed to stand.
- Because five-session extremes dominate the arithmetic, a confirmed reading can appear after a large share of a move, so the oscillator is treated as coincidental.
What the two series mark
The oscillator is built from the observation that closes cluster toward the session high during advances and toward the session low during declines. It is plotted as two series, K and %D, to mark stretched versus depleted conditions.
Those series are a pair of plotted ratios that locate the close inside a lookback high-low window. The readings can be left raw or smoothed.
A sixteen-column worksheet
Regular and smoothed readings can be produced from closed-form formulas or from a sixteen-column worksheet. The worksheet stores date, high, low, close, the five-session extreme high and low, eighths-converted differences, three-session totals, and percentage ratios.
Regular K, regular %D, and the slow construction
Regular K equals 100 times the current close minus the five-session low, divided by the five-session high minus that low. Regular %D equals 100 times the three-session sum of those close-to-low distances, divided by the three-session sum of the ranges.
In the slow construction, slow K is regular %D. Slow %D is the arithmetic mean of regular %D over the current session and the prior two sessions.
Regular K and slow %D from the five-session worksheet
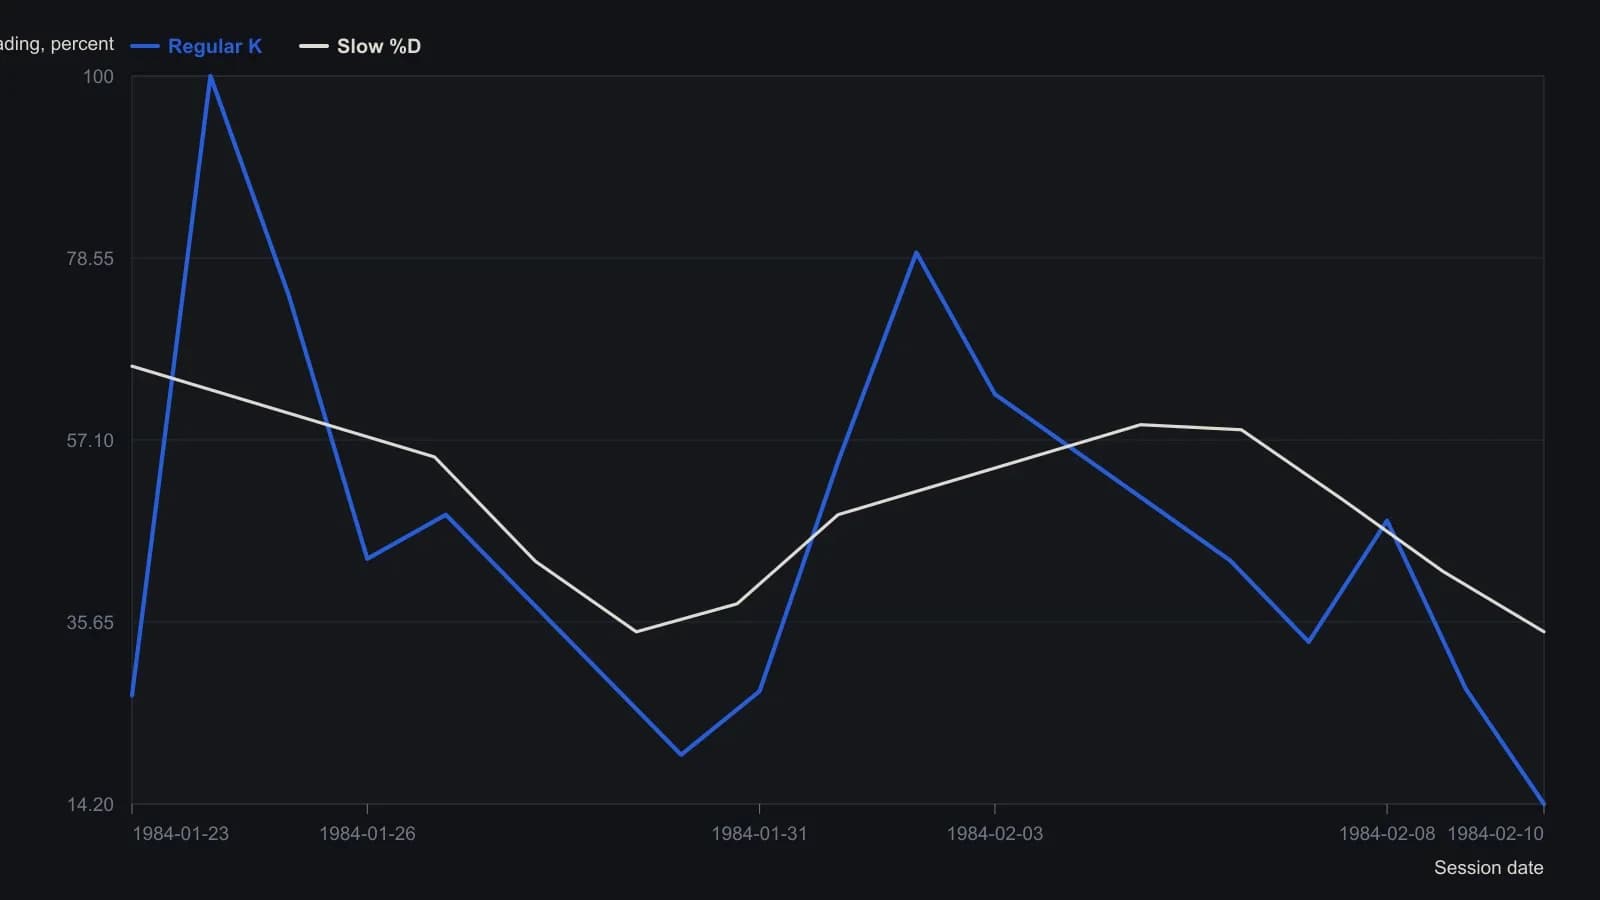
Slow %D in the source worksheet is stored as a three-digit integer (column 16 = 10 × percent). Dates skip weekends. The first four rows lack a complete five-session window, so the series starts on January 23 for K and on January 27 for slow %D. George Lane’s five-session high-low window is the period used throughout.
Crosses, divergences, warnings, and failures
A K cross of %D is the operational cue. A higher price peak against a lower %D peak is treated as a bearish divergence. A lower price trough against a higher %D trough is treated as a bullish divergence. The later cross is used as the attached action trigger.
A sharp K reversal that does not cross %D the same session is a warning that a cross may arrive within two sessions. A few-percent pullback after a cross that does not recross before K continues is a failure. That failure is described as typically followed by higher highs in both price and %D.
Which daily crosses are allowed to stand
Weekly or monthly price and oscillator charts, including drawn trendlines, are used to accept or ignore daily crosses. A weekly downtrend is treated as intact until price breaks its trendline.
An oscillator trendline with no high-side divergence is read as confirmation. Higher oscillator troughs against lower price troughs flag a possible approaching low that still needs a high-side mismatch and a break of the oscillator trendline.
Readings near 0 and 100
The method emphasizes readings above 85 percent and below 15 percent. After K reaches 0, a two-to-five session bounce and a second visit to 0 is described as raising the chance of at least a minor advance. The mirror sequence is described near 100.
Trendlines drawn on the oscillator can mark support or resistance for %D.
A coincidental reading needs a different companion signal
Because the five-session extremes dominate the arithmetic, a confirmed reading can appear after a large share of a move. The oscillator is therefore described as coincidental and is to be paired with a signal that is not built the same way.
All readings on this track · 53 readings
- 1984Constructing the slow stochastic from a five-session range
- 1985Gold-proxy trendlines and a January support base
- 1988Construct a five-week new-highs total as a breadth chart
- 1988Stacked channel, trendline, and moving-average warnings in 1987
- 1989Auditing fifth-wave counts with equality, Fibonacci, and trendlines
- 1990Money-fund maturity as a companion Eurodollar chart
- 1990Constructing wave targets from ratios, triangles and trendlines
- 1992Nested time frames for trend and channel signals
- 1992A pre-trade checklist for trendline breaks and loss limits
- 1992Bond-fund timing inside trendlines, retracements, and dual averages
- 1992Two-point trendline construction from rise over run
- 1993Disposable chart ratings from confirmed level tests
- 1993When trend channels define fair value after dislocations
- 1993Valid trendline anchors for three-part reversals
- 1994Pairing stochastic divergence with trendline invalidation
- 1995Constructing measured targets after trendline breaks
- 1997A three-part pullback plan with RSI, Fibonacci retracements, and a tight trendline
- 1998Rule-based Trendline construction for testable entries
- 2000Constructing trendlines, breaks, and role reversal
- 2000Constructing speed resistance lines from trend extremes
- 2000Nasdaq tech cycle stages with a 15-day average and trendlines
- 2002Two-session candlesticks that test support, resistance, and trendlines
- 2002Constructing Fibonacci ratio grids from a peak and a trough
- 2002Evaluate trendline geometry before trusting a breakout
- 2002Trendline, volume, and breakout hypotheses versus cycle-end stories
- 2003Writing the long S&P 500 trendline and cycle junction as one hypothesis
- 2003A three-event trendline reversal checklist
- 2003Reverse-engineered Relative Strength Index price curves
- 2003Two-anchor trendline construction without cut-through
- 2004Treat a 15-minute e-mini stair-step as congestion under a daily lid
- 2005A 50-day average, a trendline break, and an open barrier flip
- 2005Matching a forty-day average to a crude trendline
- 2006Constructing a relative spread-strength oscillator for staged cycle confirmation
- 2006Constructing a log-change probability line for trend and range rules
- 2007Linked cross breaks as dollar-pair filters
- 2007A case study in support, resistance, and trendline role reversal on currency charts
- 2007Reading trendline breaks in a housing-sector case
- 2007Constructing replaceable trendlines for break signals
- 2007Reading trendline breaks before the mechanical signal
- 2007Trading choppy forex trends with channels and Fibonacci breaks
- 2007A stacked hypothesis from wave, trendline, ratio, and candle
- 2008Exit rules before entry: trendline, support, and stops
- 2008Capitulation headlines need trend confirmation
- 2008RSI divergence classes, ratio thresholds, and trendline tests
- 2010Support and resistance as falsifiable chart hypotheses
- 2012Reading a 2012 software directory as a breakout and channel case study
- 2013Treat a currency position as a regime, then map shared levels
- 2014Evaluating trendline swing size per market
- 2018Intermarket regime stress and the January 2018 trendline break
- 2018Weekly and daily Stochastic oscillator construction on a single daily chart
- 2018Constructing trendlines, support, and breakout targets from crowd exits
- 2019Trendline break and Fibonacci retracement as a falsifiable outlook check
- 2019Monthly S&P 500 false-break versus the decade trendline