2019issue C0218-23
Volume-volatility parabola and signed-volume momentum
A 10-year SPY window ending September 29, 2017 is described as a parabola of 25-day mean return against 25-day mean volume, with a vertex volume of 148 million. The archive treats market momentum as the signed product of volume and price change, the construction brief used here for on-balance volume and volume-price analysis.
- A 25-day mean-return versus 25-day mean-volume plot for SPY over a 10-year window ending September 29, 2017 is described as a parabola rather than a straight line, with a vertex volume of 148 million.
- Below that vertex, 25-day mean return is described as oscillating near zero between -0.5% and +0.5%, and the series median volume of about 142 million sits close to the vertex.
- In that same window, average volume on up days is about 4% below average and average volume on down days is 4% above average, while mean price change is +0.77% on up days versus -0.87% on down days.
- The source treats market momentum as the signed product of volume and price change and states that an unfilled order has no momentum because no trade is completed.
Mean return against mean volume
A 25-day mean-return versus 25-day mean-volume plot for SPY over a 10-year window ending September 29, 2017 is described as a parabola rather than a straight line, with a vertex volume of 148 million.
Below that vertex, 25-day mean return is described as oscillating near zero between -0.5% and +0.5%. The series median volume of about 142 million sits close to the vertex.
SPY 25-day mean volume versus 25-day mean return
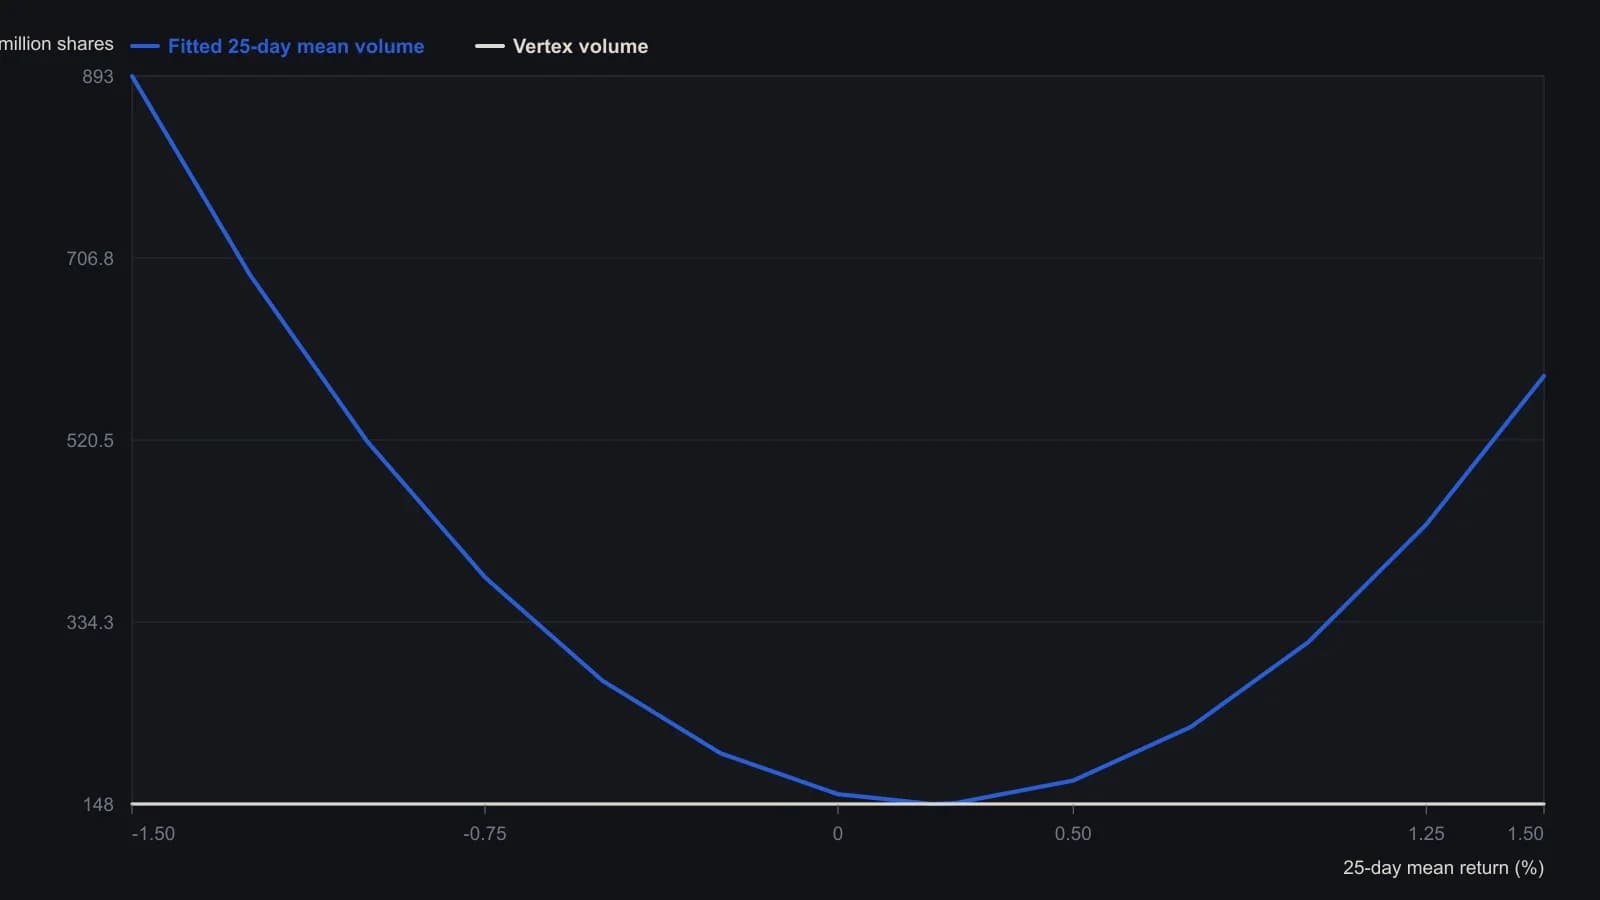
Least-squares fit reported as y = 258,415,324x² − 102,208,800x + 158,194,769 on 25-day means for SPY through 29 September 2017 (R² = 0.3140). Volume is shown in millions of shares. The author notes the skew can flip with the window or the symbol; this is the printed parabola, not the underlying scatter.
Volume on gaining and declining days
In that same SPY window, average volume on up days is about 4% below average and average volume on down days is 4% above average. Mean price change is +0.77% on up days versus -0.87% on down days.
When volume is split by gaining versus declining days and scaled as a multiple of median volume, absolute price change rises with volume on both sides below about three times the median. Declining days move more than gaining days above that threshold.
A 10-year SPY window ending September 29, 2017 associates negative volume with a mean daily price decline of 0.15%.
Competing accounts of volume and volatility
The source frames four competing accounts of volume and volatility. Mixture of distributions treats information as near-simultaneous, with little lag. Sequential information arrival has informed traders act first. Dispersion of belief is a third account. Noise trading can keep a volume spike clustered for days.
Momentum only after a trade
The source treats market momentum as the signed product of volume and price change. An unfilled order has no momentum because no trade is completed.
Editorial reading for filter construction
TradersWeek reads the parabola as a reason not to treat volume as a yes-or-no stamp on price. Near the vertex, and near the nearby median of about 142 million, 25-day mean return sits close to zero, so a volume reading in that region is a weak construction input.
The signed product of volume and price change is the archive definition of momentum. That definition can replace the slogan that volume precedes price when on-balance volume or volume-price analysis is rebuilt as a filter.
The four accounts remain competing. Mixture of distributions implies little lag. Sequential information arrival has informed traders act first. Dispersion of belief and noise trading that clusters a volume spike for days are alternative constructions. The archive does not choose among them.
All readings on this track · 61 readings
- 1988Cumulative volume trend and 200-session polarity
- 1988Three clocks when cumulative volume led price
- 1988Payoff index checkpoints for open interest and divergence
- 1988Relative strength, stochastics, and on-balance volume as a turning-point stack
- 1988Signing volume by open interest change
- 1988Case study: weekly on-balance volume with trendlines and a 21-period average
- 1988Combining weekly and daily MACD divergences with on-balance volume
- 1988Restoring the original tests for market breadth, on-balance volume, and trendlines
- 1989Evaluating volume-weighted breadth extremes
- 1989Demand oscillator construction with a momentum overlay
- 1989Constructing a volume percentage ratio from advance-decline flow
- 1990Constructing net positive volume as On-balance volume
- 1990Buying-share scale with on-balance volume
- 1990Friday-filtered on-balance confirmation lines
- 1991Constructing rate-market volume breadth from on-balance volume
- 1991Building a breadth composite from on-balance volume breakouts
- 1992Constructing a rate-complex volume-breadth index
- 1992Constructing a breadth index from on-balance volume
- 1992Constructing signed market thrust from issue volume
- 1992Constructing indicator phase across averages, volume and bands
- 1993Force on-balance volume to agree with itself at slower horizons
- 1993Three transforms of market thrust from breadth and volume
- 1994Constructing a tick-line momentum oscillator
- 1994Constructing a smoothed on-balance tick momentum oscillator
- 1994Histogram confirmation and a second-series veto for MACD-family alerts
- 1994Constructing a 40-period envelope on on-balance volume
- 1996Constructing a matched percent-B volume disparity
- 1997Constructing calendar regime overlays and volume-weighted rules
- 1997Constructing market thrust from breadth and volume
- 1997Constructing on-balance volume as a signed running total
- 1997A three-layer construction for a signed volume-force oscillator
- 1997Constructing a range-sum volume-force oscillator
- 1999On-balance volume confirmation, price-indicator divergence, and bounded exits
- 2000A daily long-only confirmation stack on the tether line
- 2000A three-filter tether and volume trend system
- 2003Constructing finite volume elements as a finite-period money-flow filter
- 2003Constructing on-balance volume from signed session volume
- 2003On-balance volume as a market-breadth participation ledger
- 2003Construct a volatility-adjusted on-balance volume filter before confirming a breakout
- 2004Opening and midday ranges as an on-balance-volume breakout case
- 2004Constructing a volatility-gated volume-flow measure
- 2004Constructing a volume-flow series from on-balance volume
- 2004Volume-flow indicator construction from on-balance volume
- 2004Volume-flow slope divergence, then separate on-balance-volume and crossover rules
- 2004Volume flow and band construction as one inspectable problem
- 2004Auditing advance-decline confirmation for scale, horizon, and composition
- 2005Bounded market breadth from the Arms index to BRIN
- 2006Overnight-hold entry and exit construction
- 2007Evaluating Volume-price confirmation versus On-balance volume and MACD
- 2009Volume confirmation versus a price advance
- 2010Typeahead retrieval of a moving average, on-balance volume, and a stochastic oscillator
- 2010Modified volume-price trend and log-price scale alignment
- 2010Constructing liquidity accelerometers from advance-decline averages
- 2012Failed short cycles as breadth and volume tests
- 2016Earnings straddles, implied volatility, and money-flow filters
- 2017A volume residual filter and a price projection matrix
- 2019Volume-volatility parabola and signed-volume momentum
- 2019Separating on-balance volume into breadth and volume
- 2020Constructing the obvm signal line
- 2020Constructing smoothed on-balance volume with a signal line
- 2020Keep neutrality as a first-class input in three-state market data