1994issue C021-12
Histogram confirmation and a second-series veto for MACD-family alerts
A faster MACD momentum reading only warns. The histogram must cross zero in the same direction, and a non-MACD series then classifies a weekly-to-daily handoff as a trend change or a rebound.
- The macdMomentumOscillator only warns. A defined alert waits for zeroLineConfirmation, when the macdHistogram crosses zero in the same direction.
- weeklyToDailyHandoff reads daily events in the direction of the weekly histogram and momentum state. An unmatched daily zero-line event is a countertrend rebound.
- Use histogramPriority when weekly momentum is falling while the weekly histogram remains above zero and still rising.
- A secondSeriesVeto is required because the momentum oscillator is described as producing false alerts. On-balance volume, Bollinger Bands, or regular MACD must agree before a trend change is accepted.
The archive treats the macdMomentumOscillator as a leading warning, the macdHistogram as confirmation, and a defined alert as occurring only when the histogram crosses zero in the same direction already indicated by the oscillator. Daily zero-line events are then read against the weekly histogram and momentum state, and at least one additional series is required before a trend change is accepted.
Weekly Swiss franc: MACD momentum warns, histogram confirms at zero
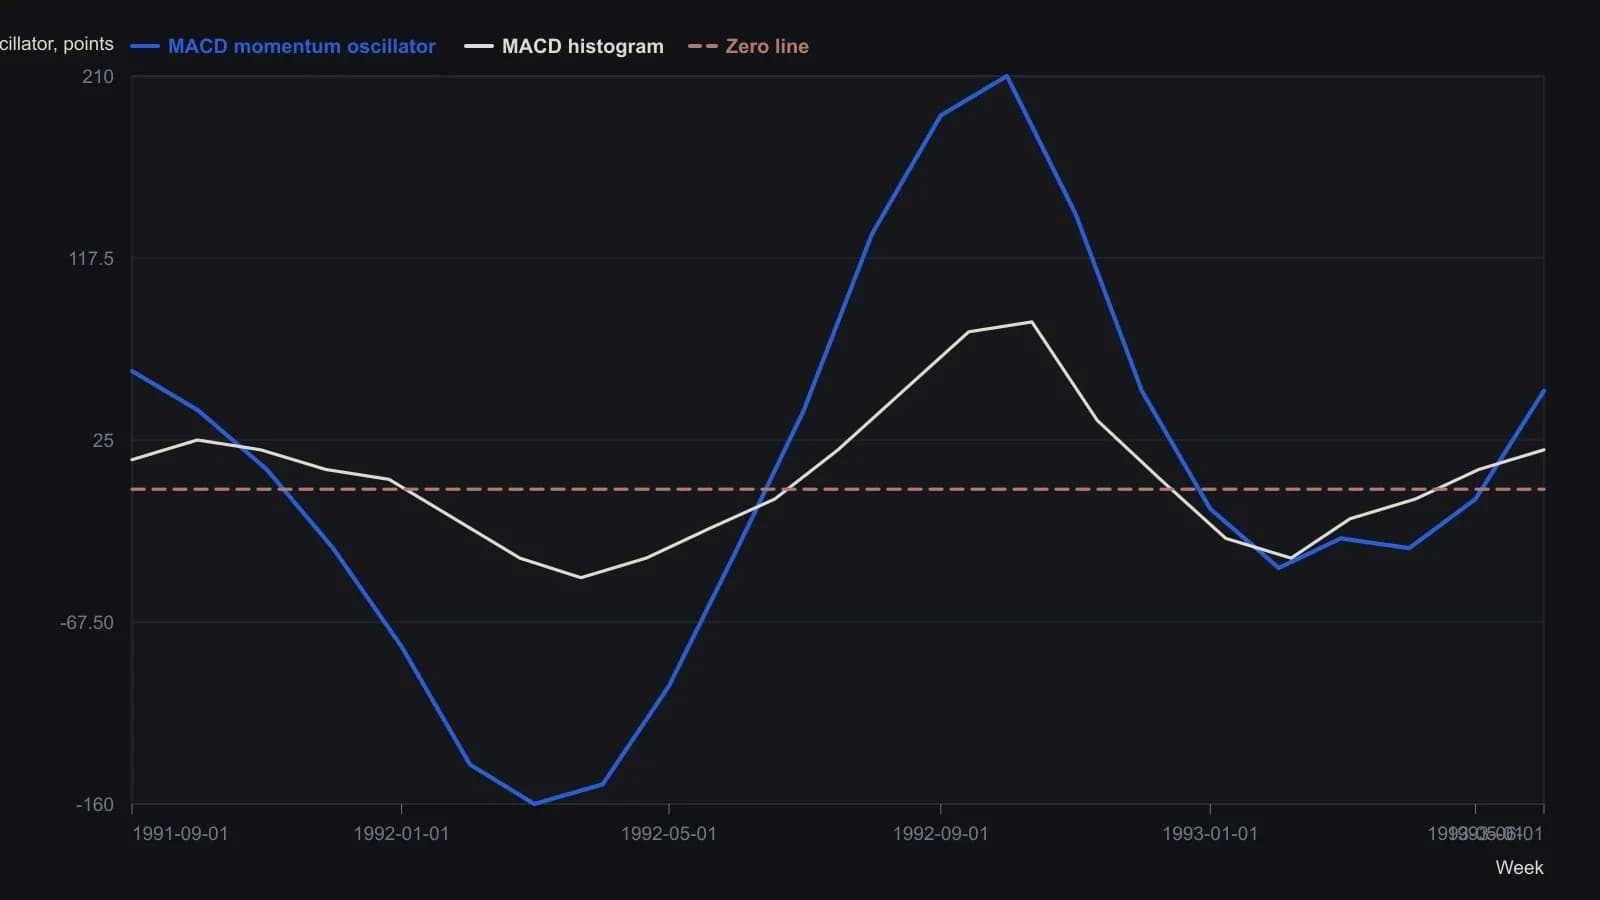
Aspray construction in the source: MACD line as the 10-period EMA minus the 20-period EMA, histogram as that line minus a 10-period EMA trigger, momentum as a 3-period average of the 10-period change in the histogram. Digitized from a raster plot of weekly bars. Momentum rounded to 10 points; histogram to 5 points.
Three MACD-family series
The classic macdLine is the difference between two exponential moving averages of price, commonly a 12-period and a 26-period pair. The triggerLine is commonly a 9-period exponential average of that line. A cross of the two lines is treated as a potential trend-change alert.
One macdHistogram construction uses a 10-period versus 20-period exponential pair for the macdLine, then plots the difference between that line and a 10-period exponential triggerLine.
The macdMomentumOscillator is formed by subtracting the current histogram value from its value 10 periods earlier and smoothing that difference with a three-period simple moving average. Both series are read above and below their own zero lines.
When a warning becomes an alert
The macdMomentumOscillator is treated as a leading warning and the macdHistogram as confirmation. A defined alert occurs only as zeroLineConfirmation: the histogram crosses its zero line in the same direction already indicated by the momentum oscillator.
Weekly reading order
On weekly charts, reading order is oscillator direction first, then zero-line crosses, then overbought or oversold extremes versus the histogram. A four-to-six-month oscillator divergence is treated as a possible major trend-change warning, with histogram confirmation expected within two to five weeks.
Weekly-to-daily handoff
On daily charts, weeklyToDailyHandoff comes first. The weekly histogram and momentum state classify the intermediate trend, and daily events are read in that direction. A daily momentum zero-line cross is expected to be confirmed by the histogram within two to five days. Four-to-eight-week daily divergences are treated as possible trend-change warnings.
histogramPriority applies when weekly momentum is falling while the weekly histogram remains above zero and still rising. In that case the histogram is given more weight.
A daily zero-line event that is not matched by weekly histogram and momentum positions on the same side of zero is classified as a countertrend rebound rather than an intermediate trend change.
The second-series veto
The macdMomentumOscillator is described as producing false alerts. At least one additional series is required before a trend change is accepted. That secondSeriesVeto can be a suggested retest of the entry area, or confirmation from on-balance volume, Bollinger Bands, or the regular MACD.
Regular MACD and Bollinger Bands were used as a second confirmation layer so that repeated histogram and momentum zero-line flips could be set aside while regular MACD stayed above zero and price remained above the lower and middle bands.
On-balance volume was used as an independent confirmation series. Momentum-oscillator long alerts while on-balance volume stayed below its zero line were treated as countertrend rallies. A potential reversal was flagged only when both the oscillator and on-balance volume showed matching bullish divergence.
All readings on this track · 61 readings
- 1988Cumulative volume trend and 200-session polarity
- 1988Three clocks when cumulative volume led price
- 1988Payoff index checkpoints for open interest and divergence
- 1988Relative strength, stochastics, and on-balance volume as a turning-point stack
- 1988Signing volume by open interest change
- 1988Case study: weekly on-balance volume with trendlines and a 21-period average
- 1988Combining weekly and daily MACD divergences with on-balance volume
- 1988Restoring the original tests for market breadth, on-balance volume, and trendlines
- 1989Evaluating volume-weighted breadth extremes
- 1989Demand oscillator construction with a momentum overlay
- 1989Constructing a volume percentage ratio from advance-decline flow
- 1990Constructing net positive volume as On-balance volume
- 1990Buying-share scale with on-balance volume
- 1990Friday-filtered on-balance confirmation lines
- 1991Constructing rate-market volume breadth from on-balance volume
- 1991Building a breadth composite from on-balance volume breakouts
- 1992Constructing a rate-complex volume-breadth index
- 1992Constructing a breadth index from on-balance volume
- 1992Constructing signed market thrust from issue volume
- 1992Constructing indicator phase across averages, volume and bands
- 1993Force on-balance volume to agree with itself at slower horizons
- 1993Three transforms of market thrust from breadth and volume
- 1994Constructing a tick-line momentum oscillator
- 1994Constructing a smoothed on-balance tick momentum oscillator
- 1994Histogram confirmation and a second-series veto for MACD-family alerts
- 1994Constructing a 40-period envelope on on-balance volume
- 1996Constructing a matched percent-B volume disparity
- 1997Constructing calendar regime overlays and volume-weighted rules
- 1997Constructing market thrust from breadth and volume
- 1997Constructing on-balance volume as a signed running total
- 1997A three-layer construction for a signed volume-force oscillator
- 1997Constructing a range-sum volume-force oscillator
- 1999On-balance volume confirmation, price-indicator divergence, and bounded exits
- 2000A daily long-only confirmation stack on the tether line
- 2000A three-filter tether and volume trend system
- 2003Constructing finite volume elements as a finite-period money-flow filter
- 2003Constructing on-balance volume from signed session volume
- 2003On-balance volume as a market-breadth participation ledger
- 2003Construct a volatility-adjusted on-balance volume filter before confirming a breakout
- 2004Opening and midday ranges as an on-balance-volume breakout case
- 2004Constructing a volatility-gated volume-flow measure
- 2004Constructing a volume-flow series from on-balance volume
- 2004Volume-flow indicator construction from on-balance volume
- 2004Volume-flow slope divergence, then separate on-balance-volume and crossover rules
- 2004Volume flow and band construction as one inspectable problem
- 2004Auditing advance-decline confirmation for scale, horizon, and composition
- 2005Bounded market breadth from the Arms index to BRIN
- 2006Overnight-hold entry and exit construction
- 2007Evaluating Volume-price confirmation versus On-balance volume and MACD
- 2009Volume confirmation versus a price advance
- 2010Typeahead retrieval of a moving average, on-balance volume, and a stochastic oscillator
- 2010Modified volume-price trend and log-price scale alignment
- 2010Constructing liquidity accelerometers from advance-decline averages
- 2012Failed short cycles as breadth and volume tests
- 2016Earnings straddles, implied volatility, and money-flow filters
- 2017A volume residual filter and a price projection matrix
- 2019Volume-volatility parabola and signed-volume momentum
- 2019Separating on-balance volume into breadth and volume
- 2020Constructing the obvm signal line
- 2020Constructing smoothed on-balance volume with a signal line
- 2020Keep neutrality as a first-class input in three-state market data