2006issue C091-11
Assembling an adaptive price zone from double-smoothed averages
The adaptive price zone is a price channel centered on a double-smoothed exponential average of price, with a half-width set by band-percent times a double-smoothed exponential average of range. A 14-period average directional index then decides whether a band touch is a buy or sell-short condition or a cue to close open exposure.
- The adaptive price zone is a price channel whose center is a double-smoothed exponential average of price and whose half-width is band-percent times a double-smoothed exponential average of range.
- Double smoothing is chosen so the channel can follow short-horizon price and range with less lag than a simple moving average of the same lookback.
- A 14-period average directional index at or below 30 allows buy and sell-short conditions on band touches; a reading above 30 closes open exposure instead of taking new entries.
- Lookback-period and band-percent stay fixed once chosen and must be tuned by market and chart interval; only the band width moves with double-smoothed range.
A price channel with a volatility-scaled width
The adaptive price zone is a price channel: a pair of bands around a smoothed center line that frames a zone of typical price travel. The center is a double-smoothed exponential average of price. The half-width is a chosen multiple of a double-smoothed exponential average of range. A close or excursion beyond a band is treated as a chart condition, not a guaranteed reversal.
Band width expands and contracts with recent volatility because that half-width is a multiple of double-smoothed range. The scalar applied to the double-smoothed range is band-percent, a user setting rather than an automatically learned parameter. The lookback-period is the sampling length supplied to the inner exponential smoothers for price and range.
Why the averages are smoothed twice
Exponential smoothing is a recursive average that weights recent observations more heavily than older ones. Applying it twice further damps noise while still tracking short-horizon price and range. Double-smoothed exponential averaging is chosen so the channel can track short-horizon price and range with less lag than an equally weighted simple moving average of the same lookback.
The designer developed the construction for short lookbacks around five bars because conventional band indicators can become jagged at those lengths.
A trend-strength gate on band touches
A supplied implementation computes upper and lower bands as the double-smoothed price plus or minus band-percent times the double-smoothed range. It then reads a 14-period average directional index against a threshold of 30 before assigning buy or sell-short actions on band touches.
The average directional index is a bounded trend-strength reading computed from directional movement. It is used here as a gate that allows band-touch signals only when the reading stays at or below a chosen threshold.
When the average directional index is at or below the threshold, a low at or below the lower band is treated as a buy condition and a high at or above the upper band as a sell-short condition. When the reading exceeds the threshold, open long or short exposure is closed rather than new band-touch entries being taken.
Fixed settings, variable width
The designer states that lookback and band-percent settings are not adaptive and must be tuned to each market or chart interval, while only the band width itself varies with double-smoothed absolute range. The lookback-period is not adapted bar by bar.
Chart illustrations use custom settings rather than code defaults, including period 30 and band percent 1.8 on one daily index-futures window, period 50 and band percent 2.2 on a daily equity-proxy window, and period 30 and band percent 2.1 on a 610-tick intraday window.
A narrowed daily illustration used period 20, band percent 1.2, and an average-directional-index threshold of 30. The designer describes that application as a basic use of the indicator rather than a fully developed system.
A stated limit in trending markets
The designer states that the same construction does not perform well in trending markets.
Adaptive price zone strategy P&L on the e-mini S&P
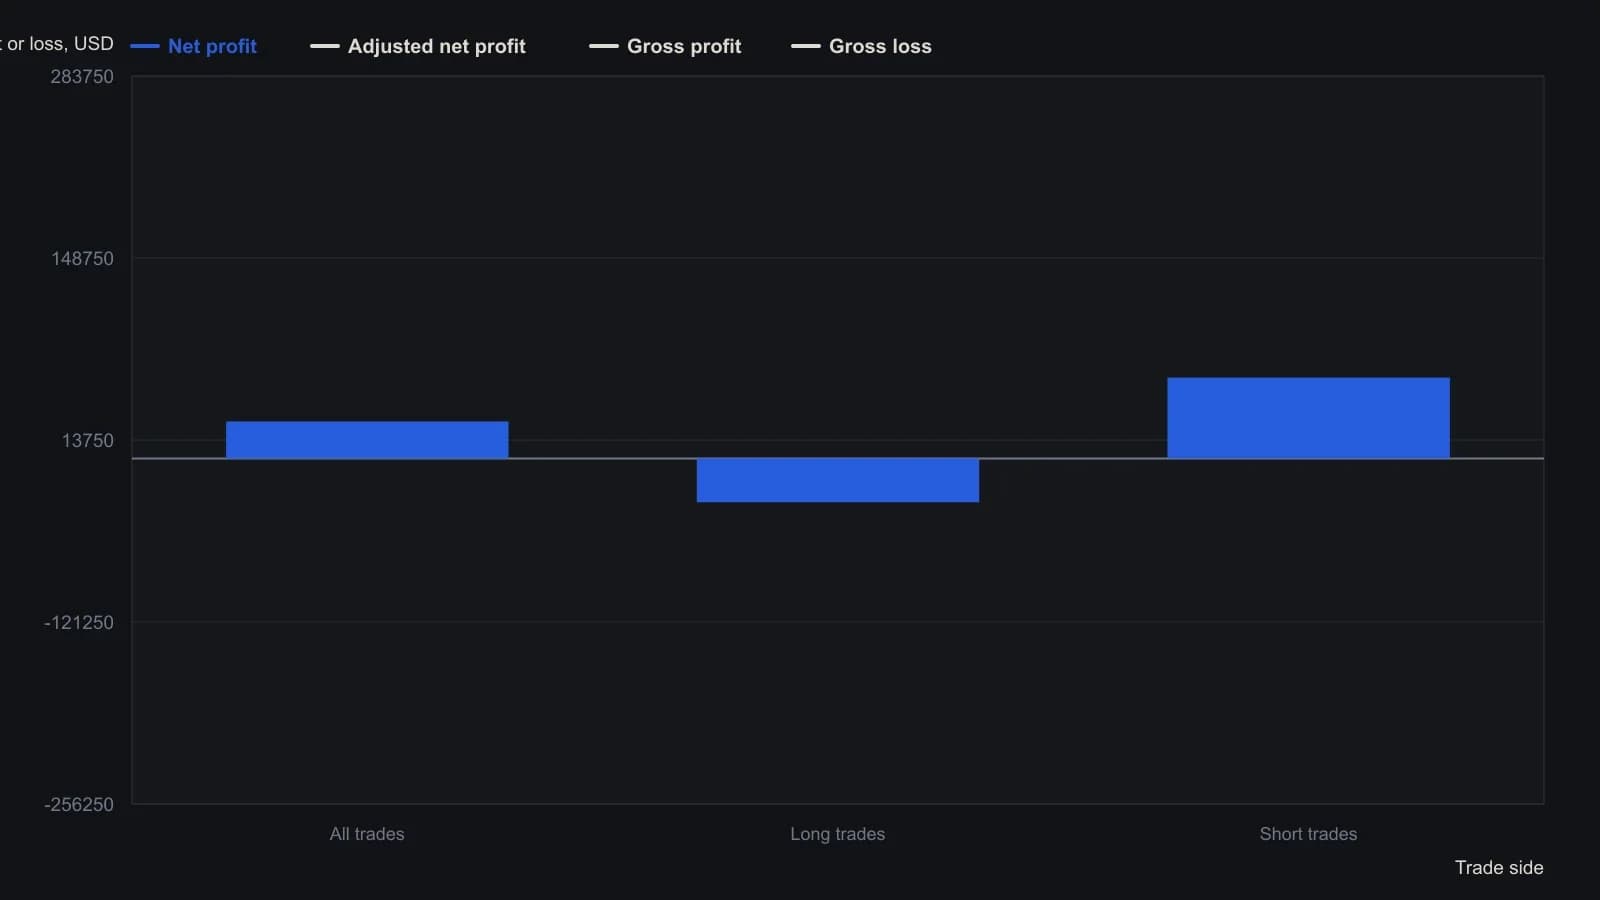
MultiCharts accepted the article’s EasyLanguage. The hourly ES #F pane is only a visible slice of July price action; the table is the platform’s full-sample summary. Adjusted P&L is MultiCharts’ haircut, not a statistic defined in the article. The author treats the rules as a basic illustration, not a finished system.
All readings on this track · 56 readings
- 1986Cycle-aligned directional trend indicator
- 1987What crossover and directional entry rules actually compare
- 1988A directional-line cross needs a trend filter, an extreme-point rule, and a dollar stop
- 1988Constructing true range by offset addressing
- 1988Constructing directional movement from bar range
- 1988Average directional index construction: recursive smoothing and lookback offset
- 1988Staged Average Directional Index construction with Relative Strength Index confirmation and stop alerts
- 1988Average Directional Index construction with frozen true range and directional rules
- 1991Constructing the average directional index from range expansion and true range
- 1991Constructing five-session forecasts from stochastic, ADX, and MACD inputs
- 1993Constructing the average directional index from directional movement and true range
- 1993Confirming n-bar breakouts with ADX and DX filters
- 1994Constructing a Bollinger band-width trend filter
- 1994A pre-trade checklist that can refuse a long three ways
- 1997An ADX threshold and a moving average as a trend filter
- 1998Regime filters for mutated indicators
- 1999Building the average directional index from range extension and true range
- 2000Evaluating ADX, RSI, and moving averages in a multi-stock warehouse
- 2000Stochastic pop as a filtered continuation setup
- 2000Onset and exit from one average directional index
- 2002Joint ADX and MACD readout for trend strength and direction
- 2003Adaptive Donchian breakout with implied volatility and volume
- 2004The average directional index as a regime gate for the relative strength index and the stochastic oscillator
- 2004Constructing true-range-specified volume as a directional filter
- 2005Constructing a multi-filter penny stock breakout procedure
- 2005Construct one playbook that flips with session regime
- 2005Combining Bollinger Bands, the average directional index, and Fibonacci retracement on currency pairs
- 2006Assembling an adaptive price zone from double-smoothed averages
- 2006An ADX strength gate for MACD and the stochastic oscillator
- 2007Directional movement as a filter plus trigger
- 2007Constructing a veto-first trend permission stack
- 2007ADX gates for trend end, range, and reversal
- 2008Constructing a nine-cell directional-ratio grid
- 2008Average directional index and directional trend indicator lookbacks as trend-filter parameters
- 2008A holding-matched market lens from averages and directional-line crosses
- 2008A nine-cell directional scoreboard for multi-horizon entries
- 2010Building a Vortex Indicator from high-low distances
- 2010Constructing ADX, RSI, and MACD price filters
- 2011Constructing a volume zone oscillator with a moving-average and Average Directional Index regime filter
- 2011A volume zone oscillator conditioned by an Average Directional Index filter
- 2011Candlestick names need volume-price, ADX, and moving-average checks
- 2012Clustered average-directional-index traces as a trend-start filter
- 2012Average Directional Index cluster filters for trend-start signals
- 2012Confirming a trend start or turn with a triple ADX cluster
- 2013Constructing a late-entry stack from a signed DMI oscillator
- 2013A directional oscillator and its stochastic as a stacked timing filter
- 2013ADX cluster lookbacks are a locked specification, not a chart label
- 2013Combining moving averages, stochastics, and ADX in a daily scan
- 2015Assembling the Average Directional Index from directional movement
- 2016How an Average Directional Index filter and a breakout entry form one procedure
- 2016Score RSI and stochastic crossings only when ADX confirms the trend
- 2018Constructing an ADX filter for intraday breakouts
- 2018An ADX volatility gate for prior-day breakouts
- 2019Exponential deviation bands with a moving average, RSI and ADX
- 2020A normalized-slope trend filter from linear regression
- 2020Gating volatility-momentum divergences with a Trend filter