1993issue C041-15
Confirming n-bar breakouts with ADX and DX filters
A long-side n-bar high is taken only when a coincident ADX or DX high confirms it, and the trade is closed on a seven-bar low. After that three-part rule is fixed, market-specific lengths are trimmed into one shared set and judged against the same breakout run without the filter.
- A long-side n-bar high is a mechanical clearance of recent resistance, and failed breakouts are the usual case a filter is meant to reduce.
- The long entry is a dual-breakout: an x-bar price high is valid only when a y-bar ADX or DX is also making a z-bar high on the same decision bar, then the trade is closed on a seven-bar-low exit.
- ADX is a smoothed, lagging transform of DX that is easier to inspect visually; DX turns earlier but fluctuates enough that individual turns are hard to judge.
- Universalization ranks market-specific optimized lengths, drops the extremes, and averages the middle values; the shared-parameter result, not each market's optimum, is the basis for comparison with unfiltered three-bar and five-bar breakouts.
An n-bar high as a mechanical breakout
A long-side breakout can be recognized mechanically as an n-bar high: the latest close or high exceeds the highest high of the prior n bars and is treated as a clearance of recent resistance. Failed breakouts are treated as the usual case a filter is meant to reduce.
Entry, confirmation, and exit as one procedure
The tested long entry required two coincident breakouts: an x-bar price high and a y-bar average directional index or directional index making a z-bar high on the same decision bar. That dual-breakout entry is the trend filter. The indicator-side high must accompany the price high before a long is taken, so range conditions can force abstention.
Trades were long only and were closed on a seven-bar-low exit. The close is a new seven-bar low, used so an opposite-side entry would not interrupt the exit rule.
How ADX and DX differ
The average directional index is a smoothed transform of the directional index. The smoother series is easier to inspect visually but lags. The directional index turns earlier, yet it fluctuates enough that individual turns are hard to judge. A trend filter can use either series.
ADX can be read by its level or by its direction of change. A falling line is associated with range conditions. A rising line is associated with movement beyond a range.
One shared set, not six optima
The same rule set was applied to six futures markets: gold, soybeans, Treasury bonds, crude oil, the Deutschemark, and the S&P 500. Each series covered one thousand bars from late 1987 to 1991, omitting commissions and interest.
Universalization ranks market-specific optimized lengths, drops the extremes, and averages the remaining middle values to produce one shared parameter set. The shared ADX combination was a 5-bar price high with a 17-bar ADX making a 6-bar high. The shared DX combination was a 3-bar price high with a 17-bar DX making a 7-bar high.
Short price-breakout windows were justified as keeping the entry responsive after the filter reduced trade frequency. Longer indicator-breakout windows were justified as ignoring minor DX fluctuations and remaining usable on a flattened ADX after a range.
Judge the shared set against the unfiltered breakout
The filtered procedures were compared with unfiltered three-bar and five-bar breakouts. The shared-parameter result, not each market's optimum, was treated as the proper basis for judging the combined entry-and-exit rule.
17-bar ADX on crude oil, October 1989–January 1990
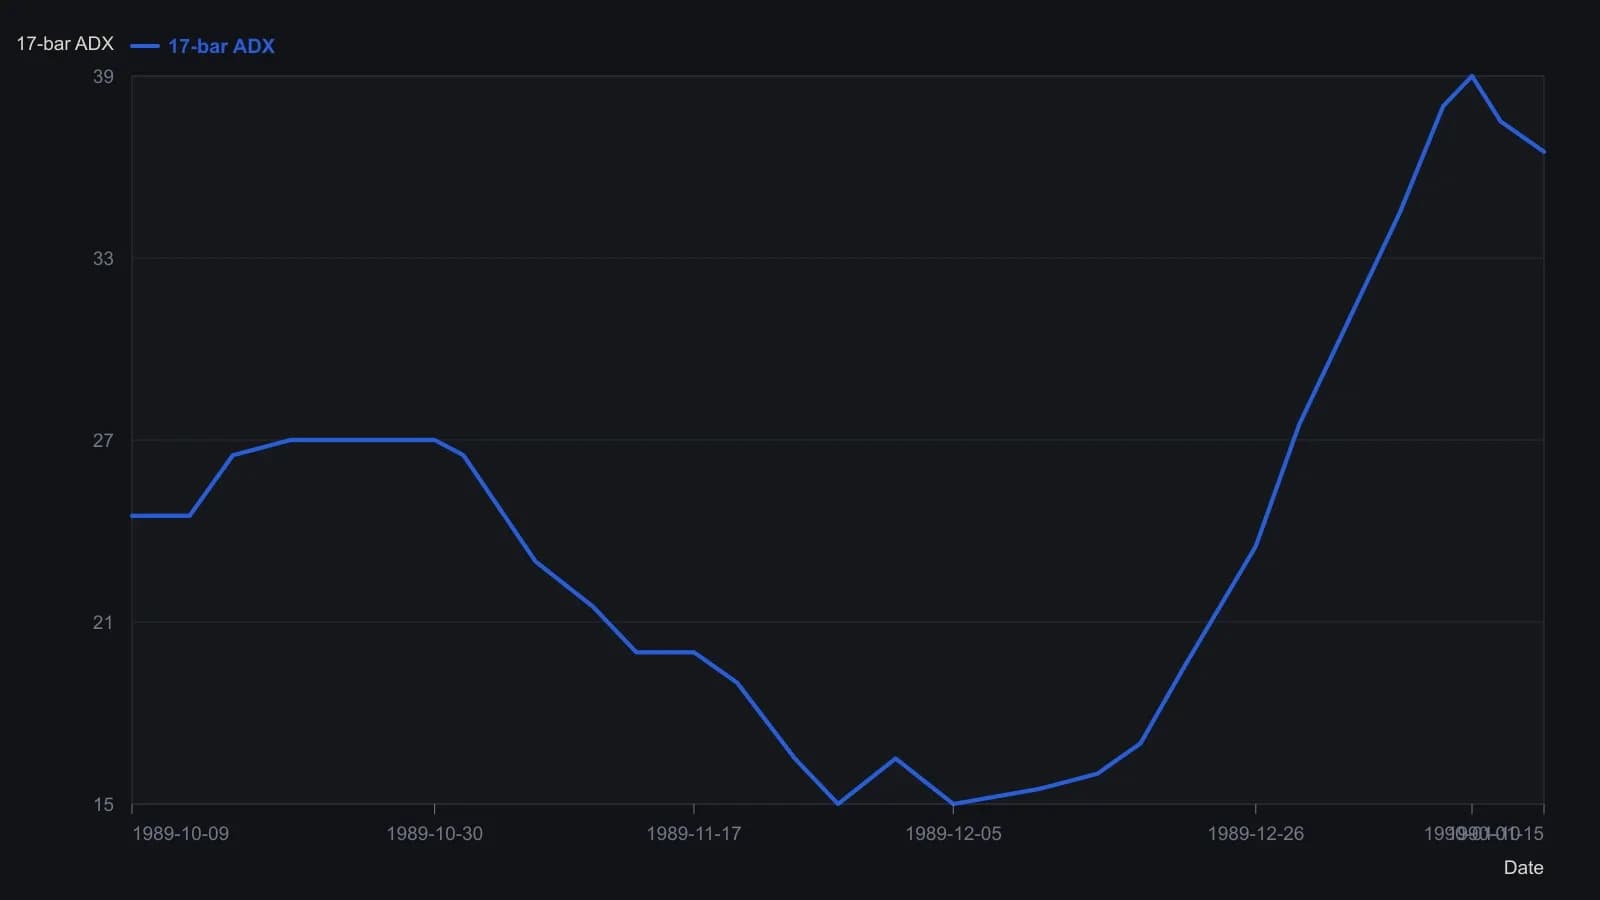
Daily 17-unit ADX digitized from the published upper pane; companion crude-oil bars use another scale and are not plotted. Approximate to about half an ADX point. Shared rule in the source: 5-bar price high, 6-bar high of this 17-bar ADX, exit on a 7-bar low.
All readings on this track · 56 readings
- 1986Cycle-aligned directional trend indicator
- 1987What crossover and directional entry rules actually compare
- 1988A directional-line cross needs a trend filter, an extreme-point rule, and a dollar stop
- 1988Constructing true range by offset addressing
- 1988Constructing directional movement from bar range
- 1988Average directional index construction: recursive smoothing and lookback offset
- 1988Staged Average Directional Index construction with Relative Strength Index confirmation and stop alerts
- 1988Average Directional Index construction with frozen true range and directional rules
- 1991Constructing the average directional index from range expansion and true range
- 1991Constructing five-session forecasts from stochastic, ADX, and MACD inputs
- 1993Constructing the average directional index from directional movement and true range
- 1993Confirming n-bar breakouts with ADX and DX filters
- 1994Constructing a Bollinger band-width trend filter
- 1994A pre-trade checklist that can refuse a long three ways
- 1997An ADX threshold and a moving average as a trend filter
- 1998Regime filters for mutated indicators
- 1999Building the average directional index from range extension and true range
- 2000Evaluating ADX, RSI, and moving averages in a multi-stock warehouse
- 2000Stochastic pop as a filtered continuation setup
- 2000Onset and exit from one average directional index
- 2002Joint ADX and MACD readout for trend strength and direction
- 2003Adaptive Donchian breakout with implied volatility and volume
- 2004The average directional index as a regime gate for the relative strength index and the stochastic oscillator
- 2004Constructing true-range-specified volume as a directional filter
- 2005Constructing a multi-filter penny stock breakout procedure
- 2005Construct one playbook that flips with session regime
- 2005Combining Bollinger Bands, the average directional index, and Fibonacci retracement on currency pairs
- 2006Assembling an adaptive price zone from double-smoothed averages
- 2006An ADX strength gate for MACD and the stochastic oscillator
- 2007Directional movement as a filter plus trigger
- 2007Constructing a veto-first trend permission stack
- 2007ADX gates for trend end, range, and reversal
- 2008Constructing a nine-cell directional-ratio grid
- 2008Average directional index and directional trend indicator lookbacks as trend-filter parameters
- 2008A holding-matched market lens from averages and directional-line crosses
- 2008A nine-cell directional scoreboard for multi-horizon entries
- 2010Building a Vortex Indicator from high-low distances
- 2010Constructing ADX, RSI, and MACD price filters
- 2011Constructing a volume zone oscillator with a moving-average and Average Directional Index regime filter
- 2011A volume zone oscillator conditioned by an Average Directional Index filter
- 2011Candlestick names need volume-price, ADX, and moving-average checks
- 2012Clustered average-directional-index traces as a trend-start filter
- 2012Average Directional Index cluster filters for trend-start signals
- 2012Confirming a trend start or turn with a triple ADX cluster
- 2013Constructing a late-entry stack from a signed DMI oscillator
- 2013A directional oscillator and its stochastic as a stacked timing filter
- 2013ADX cluster lookbacks are a locked specification, not a chart label
- 2013Combining moving averages, stochastics, and ADX in a daily scan
- 2015Assembling the Average Directional Index from directional movement
- 2016How an Average Directional Index filter and a breakout entry form one procedure
- 2016Score RSI and stochastic crossings only when ADX confirms the trend
- 2018Constructing an ADX filter for intraday breakouts
- 2018An ADX volatility gate for prior-day breakouts
- 2019Exponential deviation bands with a moving average, RSI and ADX
- 2020A normalized-slope trend filter from linear regression
- 2020Gating volatility-momentum divergences with a Trend filter