2020issue C0626-29
A normalized-slope trend filter from linear regression
A raw linear-regression slope inherits the price scale of the series, so it cannot rank securities that trade at different prices. Dividing that slope by the standard error of the slope produces a normalized slope, identical to the t-statistic of the fit. The finished reading is a trend filter that keeps signed direction, reports strength, and carries a probability-style quality mark on one common scale.
- A raw least-squares slope inherits the price scale of the series, so a higher-priced path can post a larger number than a lower-priced path with the same relative shape.
- Dividing the slope by the standard error of the slope yields a normalized slope identical to the t-statistic of the fit, which can be ranked across securities and gated as on or noise.
- Windows smaller than about 30 observations need a higher absolute t-threshold than the large-sample values 1.96, 1.65, and 1.28 used for 95, 90, and 80 percent coverage.
- Unlike an average directional index construction, the normalized slope keeps the sign of the move and attaches an explicit significance threshold.
A slope is not a rank
Linear regression is a least-squares fit through every observation in a chosen window. It produces a signed slope that depends on the whole path rather than only the first and last prints.
That raw slope inherits the price scale of the series, so a higher-priced series can post a larger numerical slope than a lower-priced series with the same relative path. The raw number therefore cannot be used to rank securities against one another.
Why correlation is not the filter
A Pearson correlation is a dimensionless two-series association between minus one and plus one. It is a two-series statistic and does not, by itself, classify the trend of a single ordered price path.
The slope equals the correlation of the paired series multiplied by the ratio of the population standard deviation of the dependent series to that of the independent series. Equal volatilities make the slope coincide with the correlation and stay inside plus or minus 1. That identity scales the slope. It does not turn correlation into a single-series trend classifier.
The whole path, not the end points
Because a fitted line uses every point in the window, two 10-observation paths that both finish with a 10% end-to-end change can still produce opposite slopes, shown as 0.0032 versus -0.0483.
A rate of change is an end-point slope that uses only the first and last observations and can therefore disagree with a path-sensitive regression slope.
Same 10% rate of change, opposite regression slopes
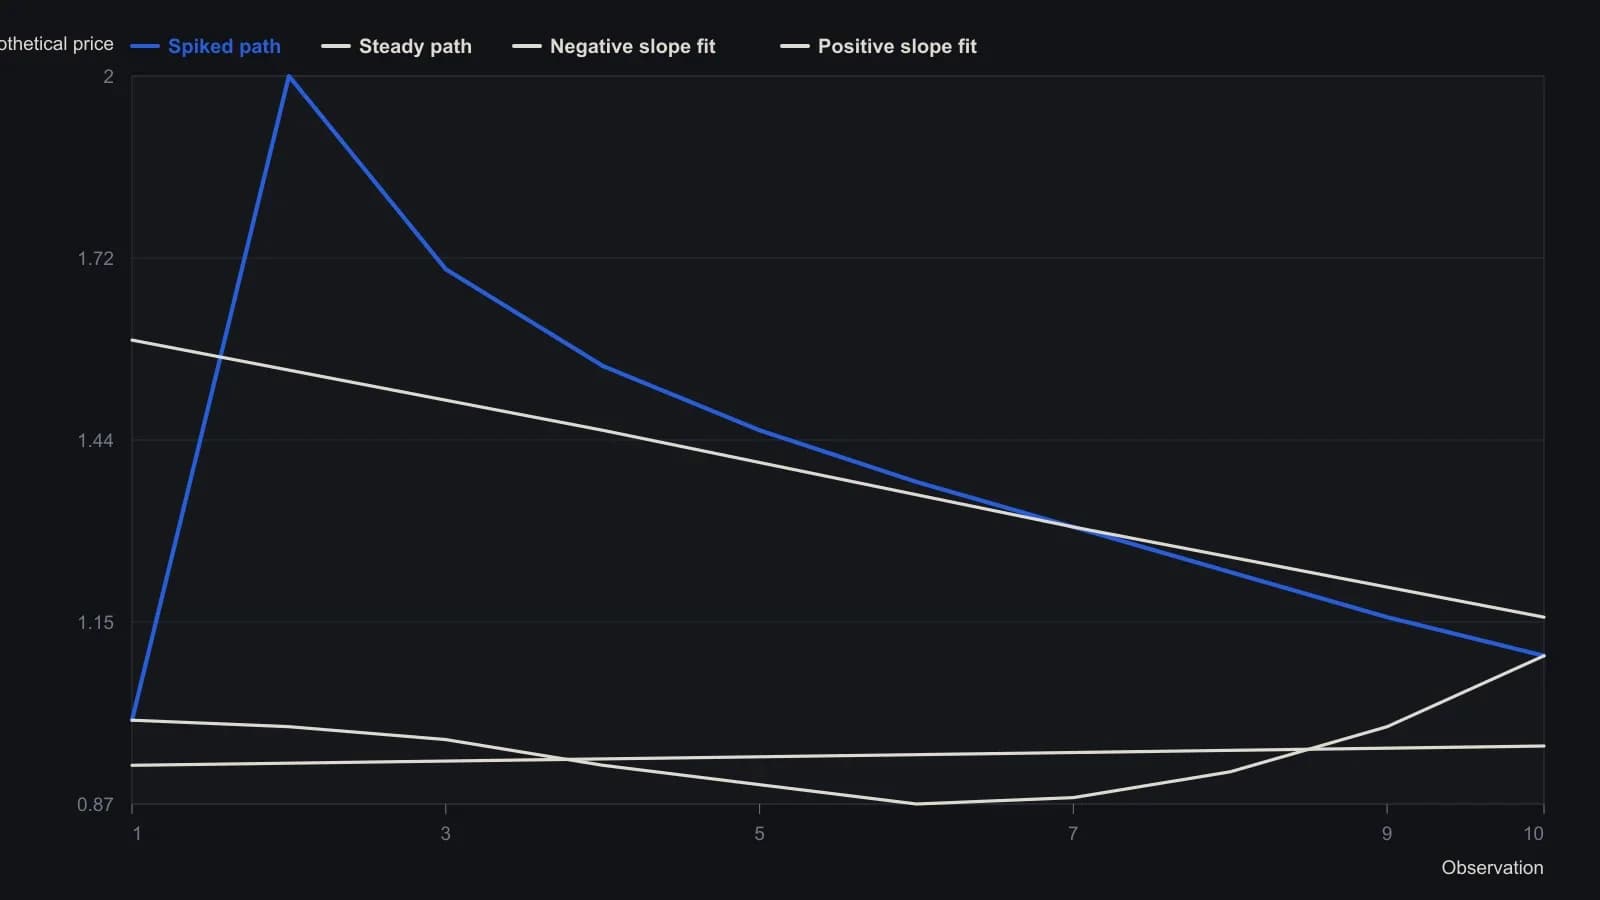
Hypothetical n=10 series. Y-values digitized from the plotted curves to about 0.05; the source did not print a data table. Fitted slopes -0.0483 and 0.0032 are the values given in the article and agree with the trendlines drawn on the figure.
From raw slope to normalized slope
The standard error of the regression is the root-mean residual distance of the observations from the fitted line, measured in the units of the dependent series. The standard error of the slope is the residual standard error of the fit divided by the product of the square root of sample size minus one and the sample standard deviation of the independent variable.
Dividing the raw slope by that standard error yields a normalized slope identical to the t-statistic of the slope.
How large a reading counts as on
Absolute readings beyond about 2 correspond to a conventional two-sided significance level near 0.025. Degrees of freedom equal sample size minus one, so windows smaller than about 30 need a higher absolute t-threshold than the large-sample normal values 1.96, 1.65, and 1.28 for 95%, 90%, and 80% coverage. A 16-observation window needs about 2.13 for 95%.
A trend filter is a gate on whether a fitted slope is strong enough, relative to the uncertainty of the fit, to treat the window as directionally on rather than as noise.
What the finished reading reports
The finished series is a trend filter that reports signed direction, strength, and a probability-style quality mark in one reading. Multiple securities can be ranked on that common scale.
Unlike an average directional index construction, which summarizes unsigned trend strength, the normalized slope keeps the sign of the move and attaches an explicit significance threshold. An average directional index does not report the sign of the slope or a t-style significance mark.
A 26-observation construction check
In a 26-observation construction check, the normalized-slope series and a MACD built with lengths 12, 26, and 1 shared the same general shape and crossed zero at the same observations. The normalized series could move against price when the MACD continued with price.
All readings on this track · 56 readings
- 1986Cycle-aligned directional trend indicator
- 1987What crossover and directional entry rules actually compare
- 1988A directional-line cross needs a trend filter, an extreme-point rule, and a dollar stop
- 1988Constructing true range by offset addressing
- 1988Constructing directional movement from bar range
- 1988Average directional index construction: recursive smoothing and lookback offset
- 1988Staged Average Directional Index construction with Relative Strength Index confirmation and stop alerts
- 1988Average Directional Index construction with frozen true range and directional rules
- 1991Constructing the average directional index from range expansion and true range
- 1991Constructing five-session forecasts from stochastic, ADX, and MACD inputs
- 1993Constructing the average directional index from directional movement and true range
- 1993Confirming n-bar breakouts with ADX and DX filters
- 1994Constructing a Bollinger band-width trend filter
- 1994A pre-trade checklist that can refuse a long three ways
- 1997An ADX threshold and a moving average as a trend filter
- 1998Regime filters for mutated indicators
- 1999Building the average directional index from range extension and true range
- 2000Evaluating ADX, RSI, and moving averages in a multi-stock warehouse
- 2000Stochastic pop as a filtered continuation setup
- 2000Onset and exit from one average directional index
- 2002Joint ADX and MACD readout for trend strength and direction
- 2003Adaptive Donchian breakout with implied volatility and volume
- 2004The average directional index as a regime gate for the relative strength index and the stochastic oscillator
- 2004Constructing true-range-specified volume as a directional filter
- 2005Constructing a multi-filter penny stock breakout procedure
- 2005Construct one playbook that flips with session regime
- 2005Combining Bollinger Bands, the average directional index, and Fibonacci retracement on currency pairs
- 2006Assembling an adaptive price zone from double-smoothed averages
- 2006An ADX strength gate for MACD and the stochastic oscillator
- 2007Directional movement as a filter plus trigger
- 2007Constructing a veto-first trend permission stack
- 2007ADX gates for trend end, range, and reversal
- 2008Constructing a nine-cell directional-ratio grid
- 2008Average directional index and directional trend indicator lookbacks as trend-filter parameters
- 2008A holding-matched market lens from averages and directional-line crosses
- 2008A nine-cell directional scoreboard for multi-horizon entries
- 2010Building a Vortex Indicator from high-low distances
- 2010Constructing ADX, RSI, and MACD price filters
- 2011Constructing a volume zone oscillator with a moving-average and Average Directional Index regime filter
- 2011A volume zone oscillator conditioned by an Average Directional Index filter
- 2011Candlestick names need volume-price, ADX, and moving-average checks
- 2012Clustered average-directional-index traces as a trend-start filter
- 2012Average Directional Index cluster filters for trend-start signals
- 2012Confirming a trend start or turn with a triple ADX cluster
- 2013Constructing a late-entry stack from a signed DMI oscillator
- 2013A directional oscillator and its stochastic as a stacked timing filter
- 2013ADX cluster lookbacks are a locked specification, not a chart label
- 2013Combining moving averages, stochastics, and ADX in a daily scan
- 2015Assembling the Average Directional Index from directional movement
- 2016How an Average Directional Index filter and a breakout entry form one procedure
- 2016Score RSI and stochastic crossings only when ADX confirms the trend
- 2018Constructing an ADX filter for intraday breakouts
- 2018An ADX volatility gate for prior-day breakouts
- 2019Exponential deviation bands with a moving average, RSI and ADX
- 2020A normalized-slope trend filter from linear regression
- 2020Gating volatility-momentum divergences with a Trend filter