2019issue C0758
Futures liquidity as an execution filter
A futures liquidity ranking combined contract point value, a three-year maximum price excursion, open interest, and a volume adjustment. Markets with more activity marks were treated as easier to trade, and each figure was read against other markets in the same column.
- A liquidity filter ranks futures by how readily size can be bought or sold, using activity, cost, and book-depth inputs rather than a directional forecast.
- Open-interest analysis weights the score by outstanding contracts, and volume confirmation adjusts it with recent turnover so quieter markets rank as harder to enter and exit.
- An equal-dollar column uses contracts to trade so each market is scaled to a comparable multi-year dollar move.
- Figures in a liquidity column are comparative only and are meaningful when read against other markets in the same column.
What the ranking combined
A futures liquidity ranking can be formed by combining contract point value, a three-year maximum price excursion, open interest, and a volume adjustment. That combination is a liquidity filter: a pre-trade screen that ranks markets by how readily size can be bought or sold, using activity, cost, and book-depth inputs rather than a directional forecast.
Relative activity marks are used so markets with the most marks are treated as easier to trade and markets with one mark or none as thinner.
Activity, open interest, and volume
Open-interest analysis weights a liquidity score by outstanding contracts so deeper books rank above thin ones when judging whether an order is executable. Volume confirmation then adjusts that score with recent turnover so high-activity markets are treated as easier to enter and exit than quiet ones.
Relative contract liquidity can be expressed as contracts to trade times total open interest times a volume factor. That volume factor is the greater of 1 and an exponential transform of volume relative to a 5,000-contract baseline.
Equal-dollar size
An equal-dollar column scales each market by how many contracts would be needed to match another market's three-year dollar excursion. Contracts to trade is that count: the number of contracts needed so each market is scaled to a comparable multi-year dollar move.
Margin intensity
Effective percent margin is obtained by dividing posted dollar margin by the contract's three-year dollar range and multiplying by 100. It is posted margin expressed as a share of a multi-year contract dollar range, used to compare capital intensity across markets.
Posted and effective margin by ranked futures contract
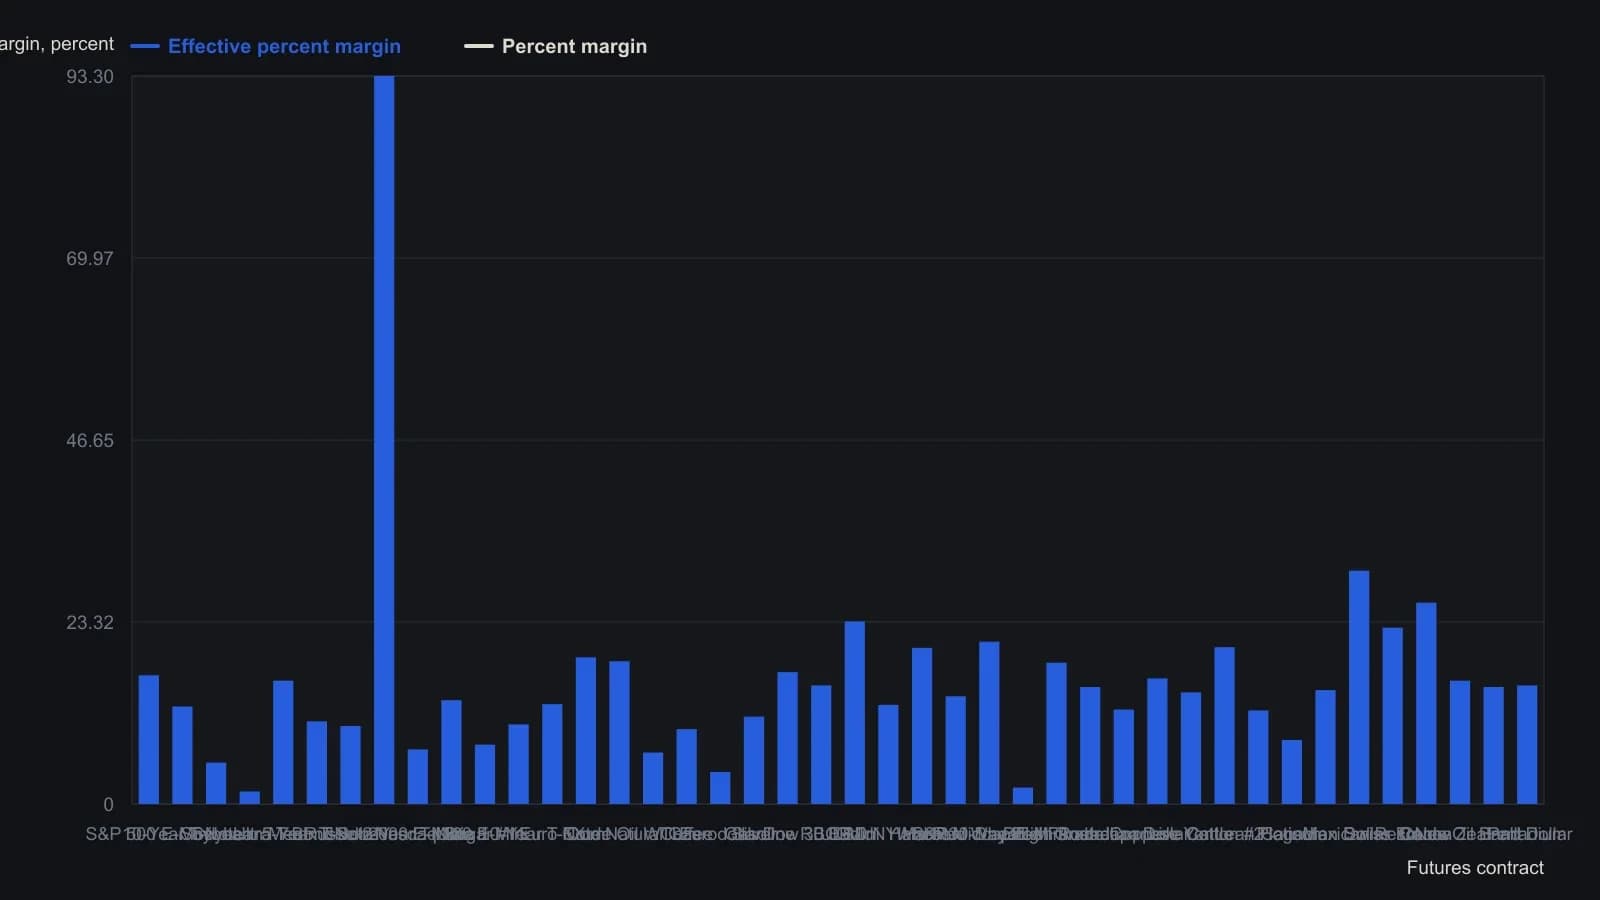
Effective percent margin is the source’s ratio of dollar margin to the three-year dollar price range of the contract, times 100. Relative-liquidity dots are a rank display, not a number, and are omitted. Contract months are the 2019 expiries printed in that table.
How the column is read
Figures in a liquidity column are comparative only and are meaningful when read against other markets in the same column. Relative contract liquidity is a same-column ranking of how easily a futures market's contracts can be traded versus other listed markets.
For listed shares, period volume as a percentage of shares outstanding is presented as share turnover, a turnover-rate proxy for trading liquidity.
All readings on this track · 40 readings
- 1988Constructing volume-confirmation overlays on OHLC spreadsheet charts
- 1989Commodity advance-decline from delivery months
- 1989The most-active list as a three-layer breadth lab
- 1989Constructing a yield-curve volume-breadth composite
- 1989A bond-futures case study in support, volume, and confirmation
- 1989Volume-scaled price boxes and volume cycles
- 1990Futures-signed on-balance volume construction
- 1990Self-relative volume boxes for news-free breakouts
- 1990Broadening swings, demand tests, and volume filters
- 1991A same-session pressure test of breadth and volume share
- 1991Tick extremes that confirm double tops and bottoms
- 1991Constructing auction fuel from volume and open interest
- 1994Constructing On-balance volume with smoothing and timeframe confirmation
- 1996A volume-gated moving-average trend combination
- 1996Constructing four-state range-volume bars
- 1997Failed trade review of a descending-triangle breakdown
- 1997Construct a head-and-shoulders before the neckline break
- 2004Volume confirmation is not optional for a head-and-shoulders reversal
- 2007Constructing a three-factor volume-price confirmation filter
- 2007Constructing a three-condition moving-average entry with a volume filter
- 2008Breakout rules that wait for volume and liquidity
- 2011Screen futures liquidity with open interest and volume
- 2011Filter executable futures with liquidity and open interest
- 2012Rank listed futures by liquidity before a forecast chooses the name
- 2012Filter futures liquidity using open interest and volume
- 2013Pre-trade futures liquidity as an execution filter
- 2014A futures liquidity screen from range, open interest and volume
- 2014Evaluating futures contract liquidity before execution
- 2014Constructing defended price lines from volume clusters
- 2014Filter futures by equal-dollar size, open interest, and volume
- 2015Filter futures ideas by ranked contract liquidity
- 2017Screen listed futures for execution liquidity first
- 2017Filter futures orders by liquidity, open interest, and volume
- 2018Using open interest and volume to rank futures liquidity
- 2018Score listed futures as an execution menu before the setup
- 2019Filtering futures orders with liquidity, open interest and volume
- 2019Futures liquidity as an execution filter
- 2020A futures liquidity board as a pre-trade execution filter
- 2020Sequenced volume and golden-cross breakout rules
- 2020Use a listed-futures liquidity filter before execution