2011issue C0677
Filter executable futures with liquidity and open interest
A futures chart is not a trade until the contract passes a tradability exam. Rank markets by how easily size can be transacted, confirm that rank with open interest and a volume factor, then compare only same-column figures for equal-dollar size and effective percent margin so implementation cost is priced before any setup reaches the order pad.
- Treat a futures chart as a candidate only after a liquidity filter ranks how readily size can be bought or sold.
- Confirm the rank with open interest analysis so the score reflects the stock of outstanding contracts, not only one session of prints.
- Apply volume confirmation so unusually quiet or unusually heavy trading does not distort relative contract liquidity.
- Read equal-dollar contract counts and effective percent margin only against other entries in the same column before any setup reaches the order pad.
A pre-ticket tradability exam
Editorial view: a futures chart is not a trade until the contract passes a tradability exam. The historical workflow treats liquidity as a screen that sits in front of the order pad, so thin markets are set aside before an order is sized.
A liquidity filter is a pre-trade screen that ranks contracts by how readily they can be bought or sold. Implementation cost is priced in that screen before any setup is allowed onto the order pad.
How the liquidity rank is built
A futures liquidity rank can be built by multiplying contract point value by a three-year maximum price-motion estimate, then by open interest, then by a volume factor usually between 1 and 4.
Relative contract liquidity is the comparative score that results. It is built from a contracts-to-trade count, total open interest, and a volume factor, and it is read only against other contracts in the same ranking.
The contracts-to-trade figure equals tick dollar value times the three-year maximum price excursion. Relative contract liquidity equals that contracts-to-trade figure times total open interest times the volume factor.
Open interest and volume confirmation
Open interest analysis uses the stock of outstanding contracts as a scale input so a ranking reflects how much size the market can absorb, not only a single session of prints.
Volume confirmation adjusts the liquidity score with a volume factor so unusually quiet or unusually heavy trading does not distort the ranking. The volume factor is a multiplier, usually between 1 and 4, taken as the greater of 1 and an exponential transform of volume relative to a 5000-contract reference.
In the historical workflow that transform is the greater of 1 and exp of (natural log of volume divided by natural log of 5000, minus 2).
Equal-dollar size and effective percent margin
An equal-dollar contract count, called an equal-dollar-profit contract count in the archive workflow, scales each listed future by contract value times the largest price change observed over the prior three years, so those entries share one dollar unit. It states how many contracts of one market are needed to match the same three-year dollar excursion as another market.
Effective percent margin equals dollar margin divided by the three-year price range of the contract’s dollar value, then multiplied by one hundred. Margin dollars are scaled by that three-year dollar price range and expressed as a percentage so capital lock-up can be compared across markets.
Editorial reading: once contracts share one dollar unit and a common margin language, implementation cost can be compared before a setup is treated as executable.
Posted and effective percent margin in the June 2011 futures liquidity ranking
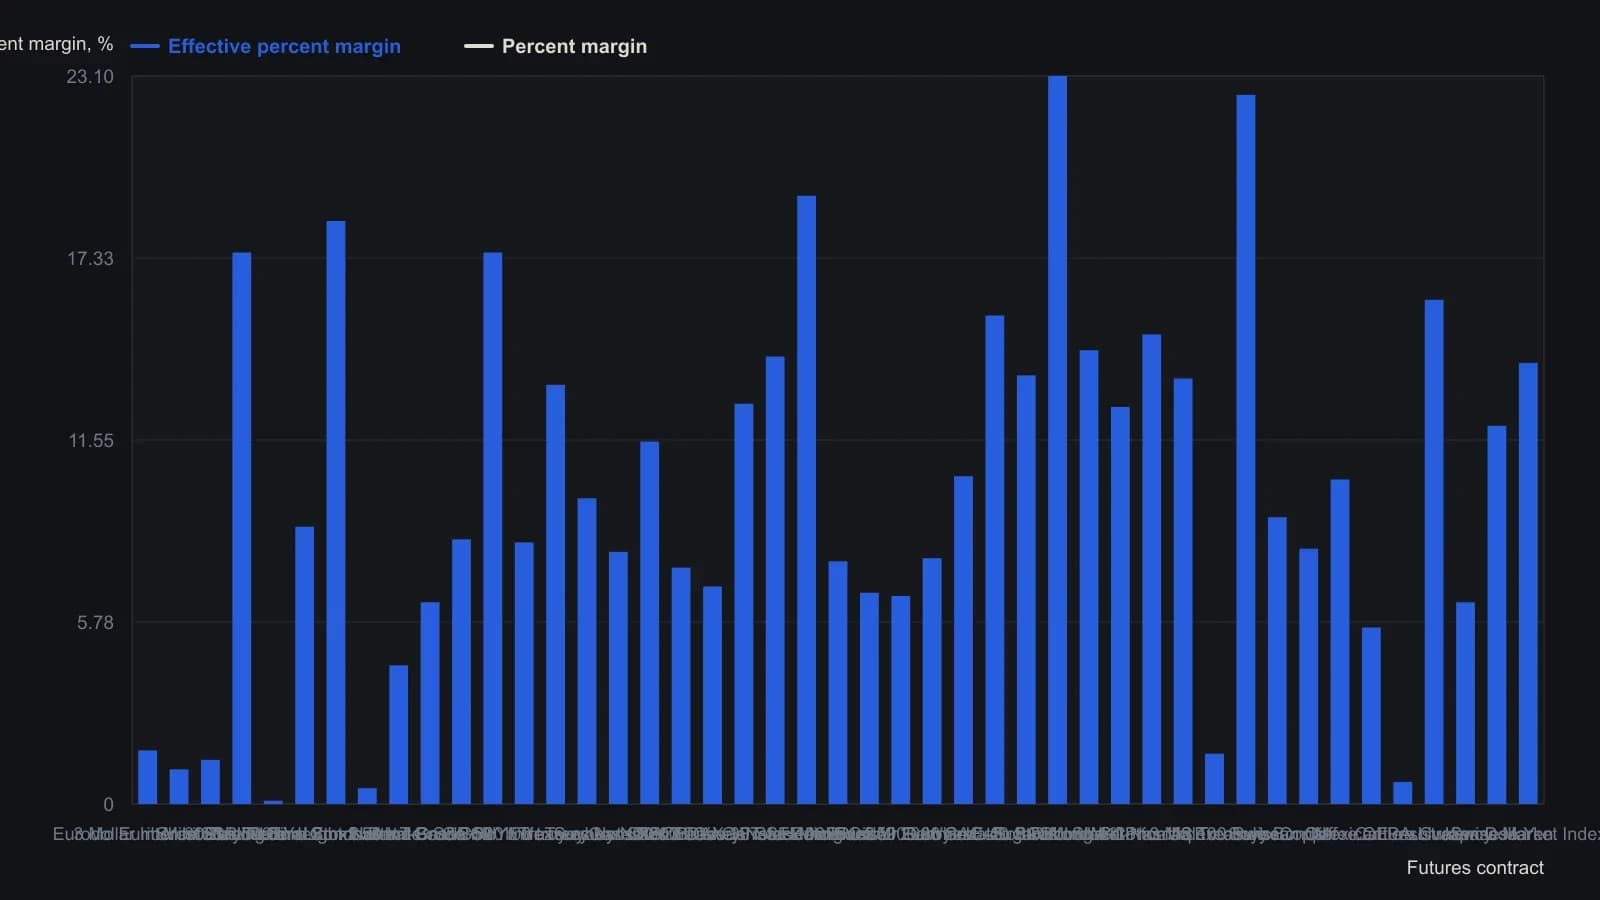
Rows follow the source’s descending relative-liquidity order, not a sort on margin. Relative liquidity itself was printed as a overflowing dot scale and is not recovered as a numeric series. Effective percent margin equals margin dollars divided by the three-year price range of contract dollar value, times 100.
How to read the ranking display
Relative activity on the ranking display is marked by a right-hand dot count. The densest mark identifies the most active contracts. One dot or none identifies little activity.
Equal-dollar contract counts, effective percent margin, and relative contract liquidity are each read only against other entries in the same column.
An equity-market analogue
In equities, period volume expressed as a percentage of shares outstanding is treated as a turnover-rate proxy for trading liquidity. Share turnover is that period volume divided by shares outstanding.
All readings on this track · 40 readings
- 1988Constructing volume-confirmation overlays on OHLC spreadsheet charts
- 1989Commodity advance-decline from delivery months
- 1989The most-active list as a three-layer breadth lab
- 1989Constructing a yield-curve volume-breadth composite
- 1989A bond-futures case study in support, volume, and confirmation
- 1989Volume-scaled price boxes and volume cycles
- 1990Futures-signed on-balance volume construction
- 1990Self-relative volume boxes for news-free breakouts
- 1990Broadening swings, demand tests, and volume filters
- 1991A same-session pressure test of breadth and volume share
- 1991Tick extremes that confirm double tops and bottoms
- 1991Constructing auction fuel from volume and open interest
- 1994Constructing On-balance volume with smoothing and timeframe confirmation
- 1996A volume-gated moving-average trend combination
- 1996Constructing four-state range-volume bars
- 1997Failed trade review of a descending-triangle breakdown
- 1997Construct a head-and-shoulders before the neckline break
- 2004Volume confirmation is not optional for a head-and-shoulders reversal
- 2007Constructing a three-factor volume-price confirmation filter
- 2007Constructing a three-condition moving-average entry with a volume filter
- 2008Breakout rules that wait for volume and liquidity
- 2011Screen futures liquidity with open interest and volume
- 2011Filter executable futures with liquidity and open interest
- 2012Rank listed futures by liquidity before a forecast chooses the name
- 2012Filter futures liquidity using open interest and volume
- 2013Pre-trade futures liquidity as an execution filter
- 2014A futures liquidity screen from range, open interest and volume
- 2014Evaluating futures contract liquidity before execution
- 2014Constructing defended price lines from volume clusters
- 2014Filter futures by equal-dollar size, open interest, and volume
- 2015Filter futures ideas by ranked contract liquidity
- 2017Screen listed futures for execution liquidity first
- 2017Filter futures orders by liquidity, open interest, and volume
- 2018Using open interest and volume to rank futures liquidity
- 2018Score listed futures as an execution menu before the setup
- 2019Filtering futures orders with liquidity, open interest and volume
- 2019Futures liquidity as an execution filter
- 2020A futures liquidity board as a pre-trade execution filter
- 2020Sequenced volume and golden-cross breakout rules
- 2020Use a listed-futures liquidity filter before execution