1997issue C081-7
A range-expansion oscillator that can refuse its own stretch
Editorial reading: treat a stretch on this oscillator as unfinished arithmetic. Each session skips a day when it forms the increment, zeros a bar that fails the overlap tests, and lets a short stay plus the next open veto the signal so the same ratio cannot fire on every extreme.
- Each session increment compares that session's high and low with the high and low two sessions earlier, not with consecutive closes.
- A signed increment is set to zero when neither overlap test holds, so a non-overlapping bar does not feed the ratio.
- Horizontal lines at 43 and -43 classify the five-session reading, and a stay of six or more sessions beyond either line cancels the current stretch until the reading recycles.
- After a short stay, the next-session open-inside and exceed-the-reference-extreme test can refuse the setup, so a stretch reading alone is not an entry.
Construction as an allow-or-refuse score
This archive note reconstructs how a numeric score is built from highs, lows and overlap tests, then turned into an allow-or-refuse signal. The construction assembles a skip-a-day ratio, a zero-on-trend rule, zone lines, a duration count and a next-open gate so the procedure can be rebuilt as one sequence.
Editorial interpretation: a stretch reading is unfinished arithmetic. Skip a day, zero a non-overlapping bar, and let a short stay plus the next open veto the signal so the same ratio cannot fire on every extreme.
Skip a day when the increment is formed
Each session's increment compares that session's high and low with the high and low two sessions earlier, not with consecutive closes. That signed two-session high and low expansion is the pressure measure used by the momentum strategy over the system holding period.
The numerator sums those two signed differences. The denominator sums their absolute sizes. The ratio is multiplied by 100 and can move between 100 and -100.
Zero the increment when overlap fails
A session's signed increment is set to zero when neither overlap test holds. One test compares the current high and low with the range five or six sessions back. The other compares the high and low two sessions back with the close seven or eight sessions back.
The overlap filter is the requirement that the current bar or the bar two sessions back still intersects an older range before a nonzero increment is recorded. Editorial note: zeroing a non-overlapping bar is how a running move is kept from feeding the ratio as if it were a fresh expansion.
The five-session range-expansion index
The five-session form plots 100 times the sum of the last five signed increments divided by the sum of the last five absolute increments. That plot is the range-expansion index, scaled from 100 to -100.
Position lines and the duration count
Horizontal position lines at 43 and -43 are the stated overbought and oversold thresholds used to classify the reading. Those overbought and oversold position lines turn a stretched expansion reading into a chart condition that can later be confirmed or refused.
A stay of six or more sessions beyond either line is treated as extreme. The duration count then cancels the current stretch until the reading returns to the middle and a new stay shorter than six sessions appears. Only after that recycle is a setup considered.
The price-oscillator qualifier
After a short oversold stay, the first higher close sets a reference high. The next session must open at or below that high and then print a higher high before an upside candidate is recognized.
After a short overbought stay, the first lower close sets a reference low. The next session must open at or above that low and then print a lower low before a downside candidate is recognized.
An open that gaps through the reference extreme fails the qualifier and is marked as a refused setup rather than a candidate. That next-session open-inside and exceed-the-reference-extreme test is the price-oscillator qualifier.
Rebuilding the full sequence
To rebuild the construction, form the skip-a-day increment, apply the overlap filter before a bar can contribute, plot the five-session range-expansion index, classify it with the 43 and -43 lines, apply the duration count, and only then run the price-oscillator qualifier. The rule-based entry is that fixed sequence of zone, duration, close and next-open checks. All of those checks must pass before a candidate is allowed. Any break in the chain refuses it.
IBM five-day TD REI, 15 January–5 February 1997
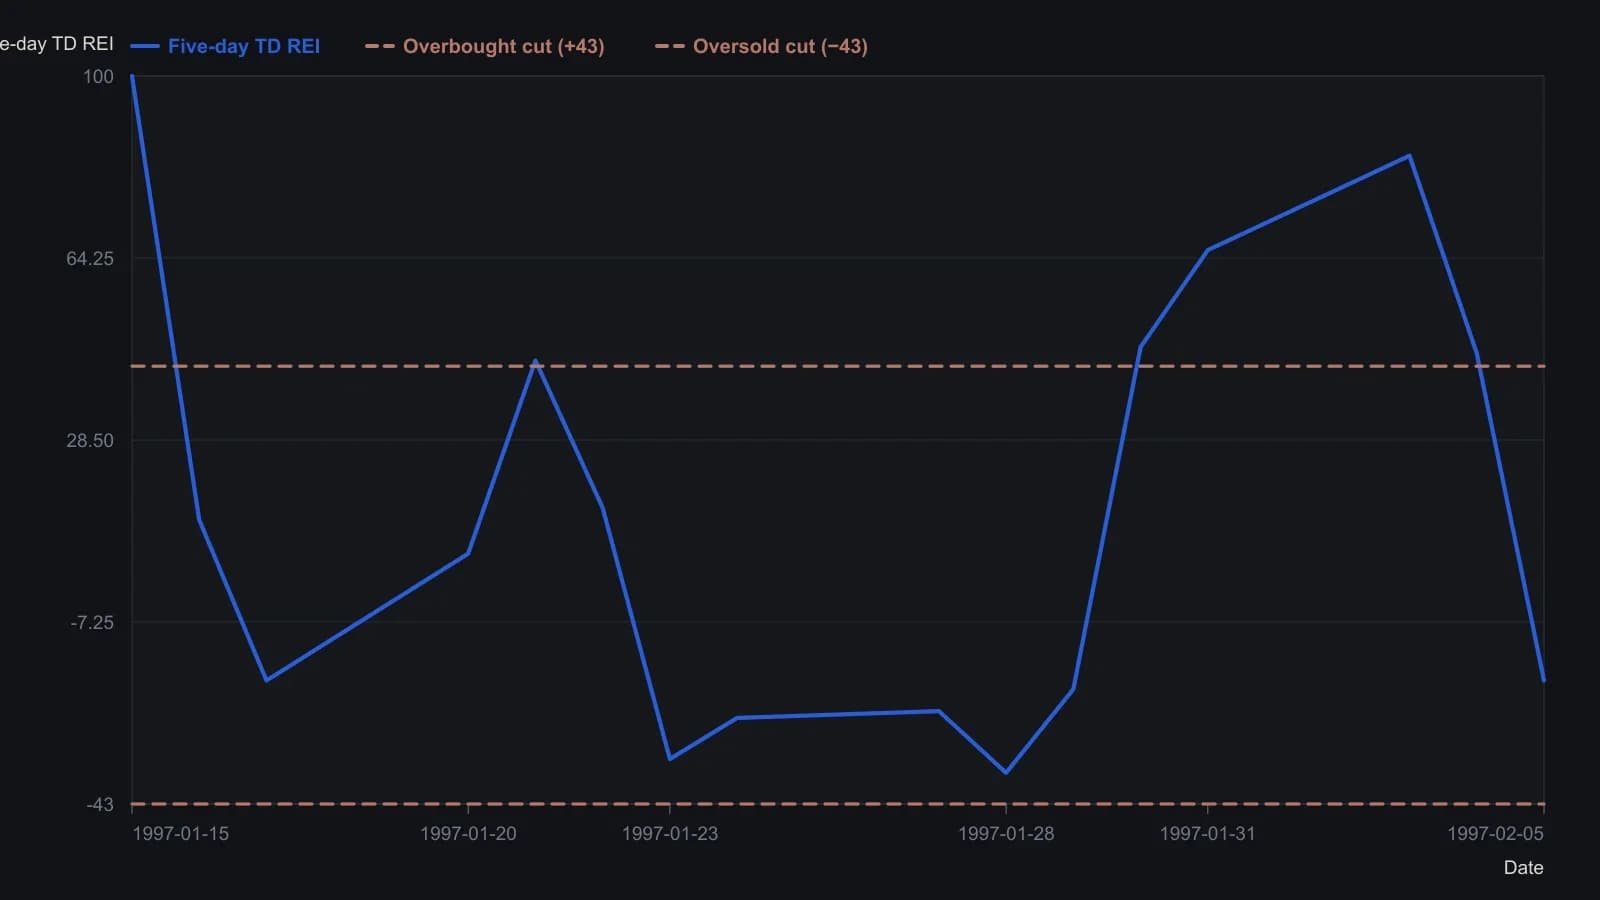
Five-session lookback: 100 times the sum of signed two-day high/low increments over the sum of their absolute values. A bar that fails both overlap tests contributes 0 to the numerator. Calculations begin on 15 January 1997 because of the lookback. Overbought and oversold cuts at +43 and −43 are the article’s stated bands, not columns on the sheet.
All readings on this track · 51 readings
- 1984Half-cycle differencing for momentum signals
- 1987Relative strength evaluation under competing optimization criteria
- 1988Weekly MACD as a two-clock momentum confirmation stack
- 1989Equal-weight zero-cross from smoothed spreads
- 1989Testing relative-strength-index reversal rules against trend continuation
- 1989Smoothed three-day futures filter for index option bounces
- 1989Cycle-length windows for momentum, Relative Strength Index, and stochastic construction
- 1991Filtered rally magnitude as a bull-regime breakout
- 1992Constructing true strength from double-smoothed momentum
- 1992Constructing a double-smoothed true strength index
- 1993When momentum structure and breadth break together
- 1993Constructing double-smoothed range and momentum oscillators
- 1993Constructing a two-parameter relative momentum index
- 1993Building a bounded momentum oscillator with RSI smoothing
- 1993Two-speed oscillators with divergence and trendline gates
- 1993Constructing a relative momentum index from the relative strength index
- 1994Constructing daily advance-decline breadth tools
- 1994Building a composite regime score from monetary climate and weekly trend
- 1994Averaging Relative Strength Index and the stochastic oscillator into one reversal oscillator
- 1995Dividend-yield regression as a hold versus momentum gate
- 1996Jump and hold filters for long-term Treasury yield direction
- 1997Constructing extendedness from a 10 percent swing filter
- 1997A range-expansion oscillator that can refuse its own stretch
- 1997RSI trend permission and Fibonacci pullback rules
- 1998Nested midpoint construction for a range-normalized oscillator
- 1999Evaluating Relative Strength Index momentum with zero-line and threshold rules
- 1999Treat RSI and momentum as three mechanical procedures
- 2000Thrust strength figure from moving-average swings
- 2001Constructing a non-range-bound balance of market power score
- 2004Cleaned breadth oscillator and new-high divergence: a swing-market case file
- 2004Evaluating advance-issues-momentum on a fixed-symbol-basket
- 2004Constructing a trend filter from two adjacent high-low windows
- 2006A dollar-versus-commodity extreme as a regime case
- 2008Zero-centered stochastic bands and bracket stops
- 2012Evaluating engulfing momentum across hold windows
- 2012Staged stops as one mechanical entry and exit procedure
- 2012Stacking a relative-strength-index forecast, a trend filter, and long-only momentum
- 2013Constructing fair-value filters from averages and momentum
- 2014Constructing a multi-window slope divergence entry
- 2015Bandedge trend filter construction with inverse crossover rules
- 2017Opposite rules for index price and volatility momentum
- 2018A three-state overlay that colors a trend only after the line clears the bar
- 2018Half-cycle relative-strength index with a Fisher map for cyclic reversals
- 2018Emotion as a rule input when momentum breaks
- 2018Two-bar body expansion as a momentum breakout construction
- 2019Pair a two-day high breakout with a volume-weighted exit on the same chart
- 2020Building reflex and trendflex cross and extreme entry rules
- 2020Construct a dual-series price momentum oscillator overlay
- 2020A multi-timeframe stochastic as a panel of weekly voters
- 2020Centerline crossovers that compare index momentums
- 2020Multi-timeframe stochastic voting as one mechanical rule