2019issue C0122-25
Volume, acceleration, and candle filters on a completed double bottom
A programmed double-bottom scan of S&P 500 and Russell 3000 constituents, from 2001 through the start of 2018, was then stacked with volume-price, acceleration, and breakout-candle filters. Editorial view: keep the finished pattern only when those rules change the tape and shrink the sample.
- A double bottom is complete only on the breakout that first clears the mid-pattern peak. Volume-price, acceleration, and breakout-candle rules were then stacked on that finished structure as independent combination tests.
- A volume-price filter requires an extreme-volume session, at least twice the prior 14-session average and the highest volume of the prior 60 sessions, either anywhere inside the pattern or only between the right trough and the breakout.
- Acceleration keeps the setup when the final ascent lasts fewer sessions than the drop from the mid-pattern peak into the right trough. Candle overlays add three higher closes, a long-body candle, a near-full-range bullish breakout candle, or a short upper shadow.
- Added filters cut the large-cap sample from 943 events to 75 under the tightest bullish-candle breakout rule. The smaller samples were treated as statistically less reliable.
The finished double bottom is the starting sample
A programmed double-bottom scan was applied to S&P 500 and Russell 3000 constituents from 2001 through the start of 2018. A double bottom is a two-trough reversal whose completion is marked by a break above the intervening peak. The breakout is the session that first clears that mid-pattern peak and thereby completes the structure.
High volume, a shorter final ascent, and bullish breakout-day candle structure were examined as independent combination tests stacked onto the same completed double bottom. The two-trough picture was the shared starting sample, not the last word on the tape.
Volume-price filters locate participation
A volume-price filter is a participation test that requires unusually heavy volume either somewhere inside the whole pattern or only on the late advance into the breakout. One version requires some session inside the entire pattern to print at least twice the prior 14-session average volume and also the highest volume of the prior 60 sessions.
A narrower volume-price filter confines that extreme-volume session to the interval between the right trough and the breakout. That version ties volume to the late advance rather than to either trough.
Acceleration requires a shorter final ascent
The final ascent is the rally from the right trough to the breakout. An acceleration filter requires that rise to last fewer sessions than the preceding drop from the mid-pattern peak to that right trough. The comparison is a session count, not a redrawing of the same two-trough outline.
Breakout-candle filters test acceptance
A three-higher-closes overlay requires three consecutive higher closes ending on the breakout session. A long-body candle filter flags a session whose real body exceeds the bodies of the three prior sessions, applied either between the right trough and the breakout or on the breakout session itself.
A bullish breakout candle was defined as a session whose close is nearly equal to the high, whose open is nearly equal to the low, and whose upper and lower shadows are each no longer than $0.05, with no constraint on total candle length. A second breakout-candle filter requires the upper shadow to be shorter than the real body so the session does not resemble a shooting-star rejection.
Tighter stacks leave fewer events
Added filters reduced event counts relative to the unfiltered pattern. The large-cap sample fell from 943 events to 75 under the tightest bullish-candle breakout rule, and the smaller samples were treated as statistically less reliable.
Profit factor of double-bottom filters
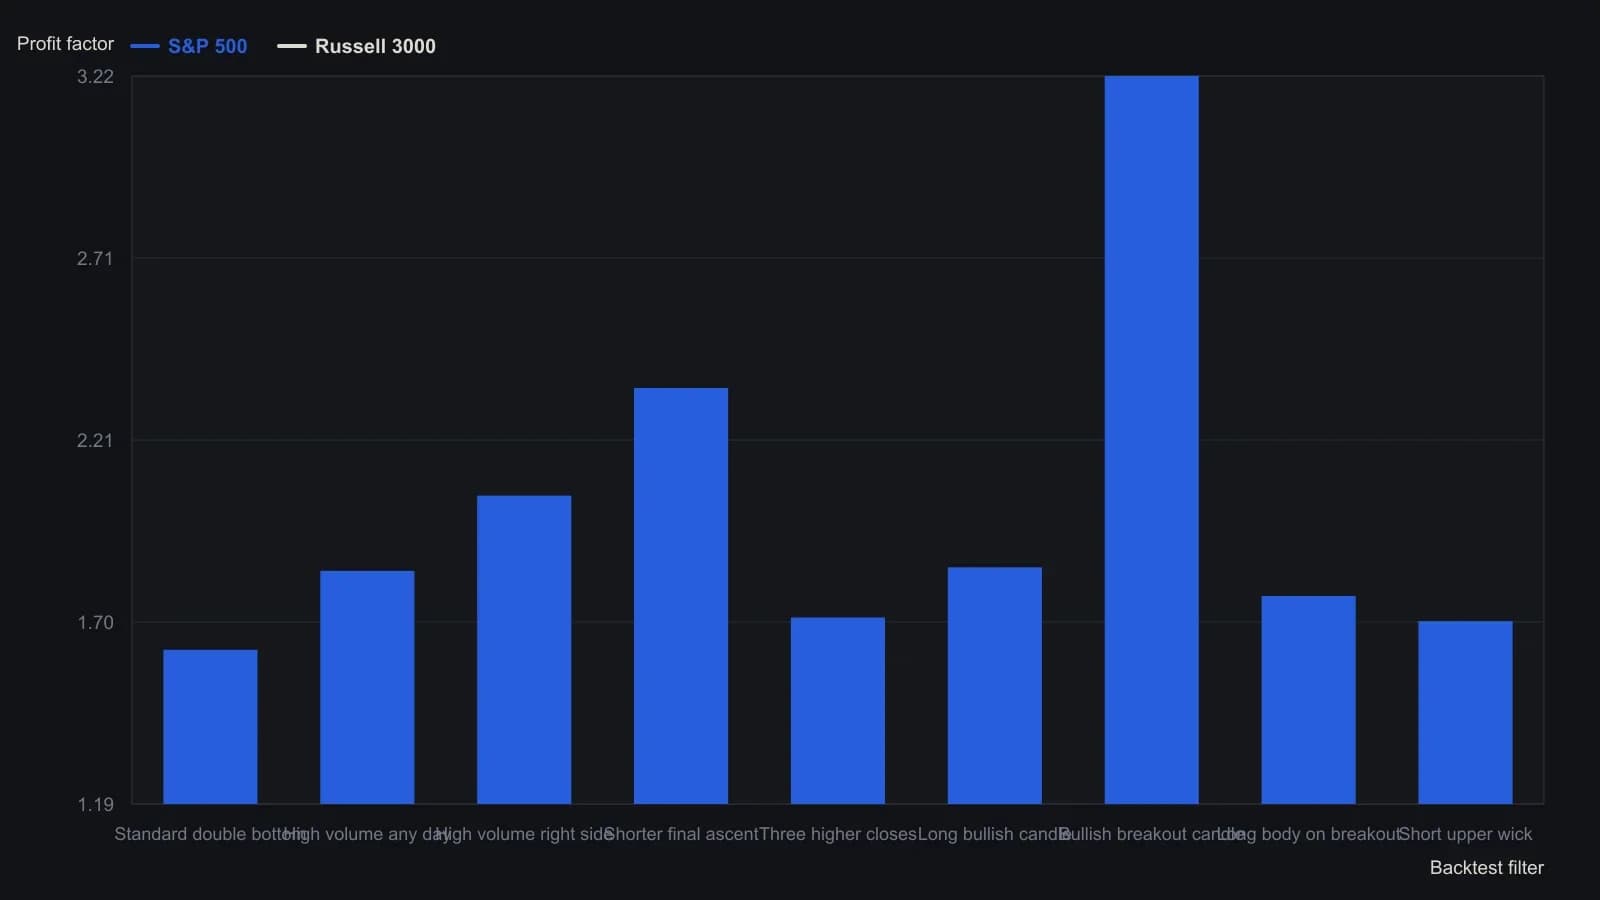
High volume meant at least twice the prior 14-day average and the highest print of the past 60 sessions. Acceleration required the rise from the right bottom to breakout to be shorter than the drop from the midpoint high to the right bottom. Bullish breakout candles allowed upper and lower shadows of at most $0.05. The author flags the 75-trade S&P 500 bullish-candle result as statistically less reliable.
All readings on this track · 54 readings
- 1990Constructing three-session rally and reaction volume signals
- 1991Constructing candlestick real bodies and multi-session patterns
- 1991Treat a candlestick reversal as incomplete until %D confirms it
- 1991Filtering candlestick signals with stochastic percent-D
- 1991Constructing compressed candlestick summaries
- 1993Intraday candlestick confirmation with oscillators
- 1993Candlestick hypotheses from a 1993 reading list
- 1994License candlestick signals with oscillators and weekly vetoes
- 1995Real-body support, resistance, and close-through breakouts
- 1997Weekly reversal as a three-part hypothesis
- 1998Turning fear levels into testable rules with a psychological matrix
- 2000Evaluating three-bar reversal reliability
- 2000Prior-day candles, open confirmation, and same-session stops
- 2000Intraday candlestick volume confirmation for daytrading
- 2001Count the key reversal up before coding a mechanical exit
- 2001Rising and falling three continuation candle construction
- 2002Treat a moving average as a contested fence
- 2003Candlestick signals need support and a risk-reward screen
- 2003Constructing one-day reversal tops and bottoms
- 2003Chart sentiment as a regime filter for hourly stochastic entries
- 2004Confirming index reversals with candlesticks, stochastics and averages
- 2004The harami inner close as a reversal barometer
- 2004Constructing a true-range volume power-shift filter
- 2005Weighing reversal clusters against moving-average support
- 2005Candlestick exits confirmed by overbought stochastics
- 2005Confirming piercing patterns with stochastics and moving averages
- 2006Candlestick cluster exits confirmed by overbought stochastics
- 2007Three black crows become a trade hypothesis only after regime, trend and nearby levels
- 2008Asymmetrical RSI lookbacks for divergence and candle confirmation
- 2008A permission checklist for the end of a trend
- 2010Mechanical entries still need confirmation gates
- 2010Crude oil as a case study in candlestick session reading
- 2010Gold weekly candles and the thousand resistance breakout
- 2010A three-layer gold chart drill from waves to candle confirmation
- 2011Why entry scans fail without trend filters
- 2011Price-zone oscillator trend-regime rules
- 2011A candlestick checklist before commodity entries
- 2013Step candle construction at price turning points
- 2013Two-bar step-candle construction
- 2014Small-range bars as a timed volume-climax hypothesis
- 2014Constructing volume-scaled candlestick charts
- 2015Weekly range midpoints as support and resistance
- 2015Constructing weekly body-midpoint pattern codes
- 2015Evaluating encoded candlestick sequence hypotheses
- 2015Constructing a breakout relative-strength index from two-day range candles
- 2016A three-gate classroom on hourly sterling
- 2016Fibonacci retracement as a pre-commitment stop map
- 2017Nine-zone filter for decade-level breakouts
- 2017Constructing pin-bar and inside-bar setups
- 2017Two-bar soldier and crow rules become a system only after filters and exits
- 2017Confirm a one-white-soldier or one-black-crow before entry
- 2018Session control from marubozu and engulfing geometry
- 2019Volume, acceleration, and candle filters on a completed double bottom
- 2019Sector-filtered candlestick scans and predrawn stops