2005issue C091-2
Weekly regime maps for production-weighted commodity subgroups
A production-weighted commodity benchmark can be split into subgroups that serve as parallel price measures. Weekly charts in the historical case share a moving-average overlay and show precious metals, agriculture, energies, and livestock sitting in different regimes.
- A production-weighted index lets each subgroup stand in as a parallel price measure for the commodities inside that group.
- The same weekly moving-average stack is the shared quantitative baseline across precious metals, agriculture, energies, and livestock.
- Support, a range boundary, and sideways consolidation describe how price sits around that stack.
- Intermarket context means judging one contract by how its subgroup sits on the map, not by its own chart alone.
A production-weighted book
A production-weighted index is a commodity benchmark whose component weights follow recent multi-year average output rather than equal or liquidity weights. In the historical workflow, that benchmark was built from average output over the most recent five years of available data. Its subgroups then served as parallel price measures for the commodities inside each group.
The same weekly overlay
Weekly subgroup charts in the case carried both 20-period and 50-period moving averages as a shared quantitative overlay. Where a 200-week simple moving average was also shown, it completed the weekly moving-average stack used as a common baseline across groups.
Precious metals and sideways consolidation
The precious-metals subgroup, limited to gold and silver, strengthened after a 2004 pullback from early-spring highs and printed higher highs by that fall. It then moved into a sideways consolidation. That later range was unlike the post-correction rebound after the 2003 decline.
Agriculture after the 2004 decline
The agriculture subgroup covers grains and several softs: wheat, red wheat, corn, soybeans, cotton, sugar, coffee, cocoa, and orange juice. After falling from summer 2004 into a fall 2004 low, the subgroup recovered more than one-third of that decline, with its 20-, 50-, and 200-week simple moving averages sitting below the index.
Energies and the 50-week average
The energies subgroup covers crude oil, Brent crude, unleaded gasoline, heating oil, and natural gas. The fall 2004 and spring 2005 corrections held at the 50-week simple moving average. Later prices moved above the March and April 2005 highs.
Livestock in a support and resistance test
The livestock subgroup covers live cattle, feeder cattle, and lean hogs. It went from an early-2004 advance into a horizontal range from summer 2004 into late spring 2005, then in May 2005 traded below both its 20-week and 50-week moving averages. After that break, livestock prices sat between the 20- and 50-week averages overhead and the 200-week average underneath, framing a support and resistance test of whether the decline would stabilize or continue.
GSCI Energies weekly closes versus the 20-, 50- and 200-week averages
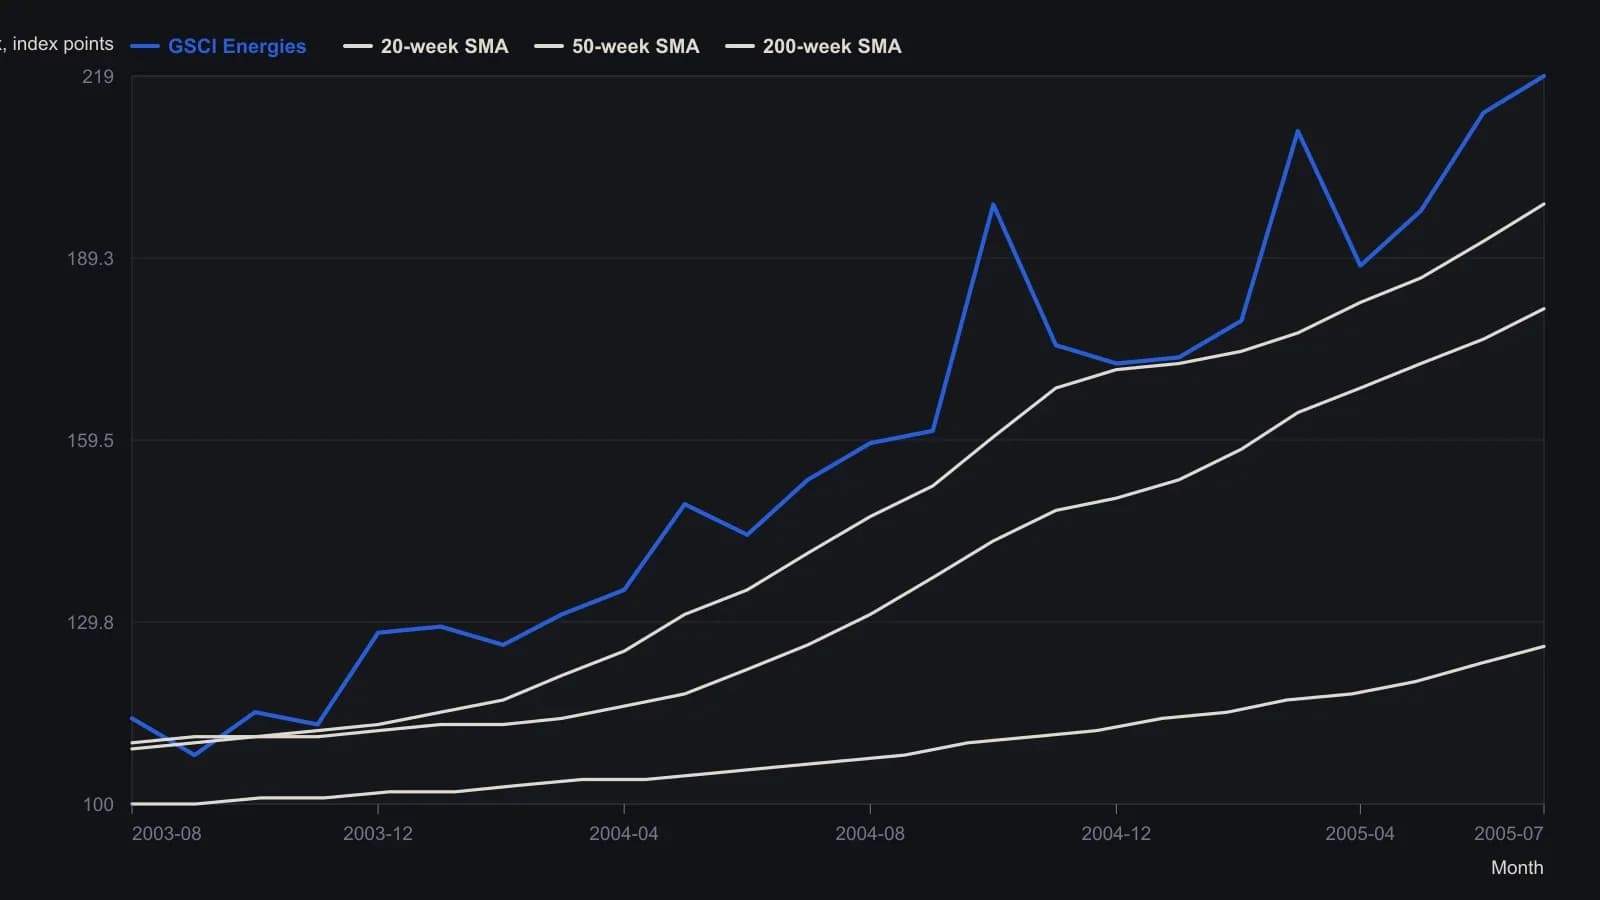
About one digitized point per month from the weekly plot; raster resolution does not support exact weekly OHLC. Legend prints on the source chart fix the last moving-average values at 198.07 (20-week), 180.96 (50-week) and 125.76 (200-week).
One contract inside the complex
Editorial reading: a weekly regime map scores each production-weighted subgroup against the same moving-average stack and the nearest support or range boundary. Precious metals in sideways consolidation, agriculture above its full stack, energies holding then clearing the 50-week average, and livestock testing support after a range break are different settings for contracts that live in those groups. The single idea is then read in intermarket context, not from its own chart alone.
All readings on this track · 33 readings
- 1990Policy-auction spread as a weekly equity regime filter
- 1992Electric utilities as bond-regime context
- 1992Reading the dollar as a rates-regime check
- 1992Evaluating weekly intermarket context for equity regimes
- 1993Specifying the stock-bond yield gap as a hold-or-abstain regime
- 1996Constructing dual-gate bond-fund entries from gold-silver jumps
- 1996Name the regime before the sector breakout
- 2002Falling prices flip stock-bond confirmation
- 2003Four sleeves on one regime board: gold miners, REITs, bills, and equities
- 2003Four currency regimes for the yen, loonie, pound and Australian dollar
- 2003Read gold through the dollar regime, the hedge spread, and a stop
- 2003When deflation flips the stock-bond map
- 2003Commodity subgroup regime boards and dual averages
- 2003Reading a liquidity regime when gold, bonds, and stocks rise together
- 2003A shared weekly checklist for four country funds
- 2004Size-and-style sleeves as a weekly regime map
- 2004Country closed-end funds shared one average checklist and four regimes
- 2004A 2004 four-pair snapshot of a dollar-bloc FX regime
- 2005Country closed-end funds as a weekly regime comparison
- 2005Weekly regime maps for production-weighted commodity subgroups
- 2005Four technology sleeves on one weekly regime map
- 2006The Australian dollar as a commodity regime and timing filter
- 2008Dual-listing moving averages as a crowd-regime test
- 2008Cross-market regime context for a single trade
- 2010Dollar index, cross rates, and commodity context for forex targets
- 2010Gold and silver forex session candles as metals-regime context
- 2012Yield curve regime and equity timing
- 2013Yield curve shapes as stock market regime context
- 2013Yield spreads as country-specific equity regime context
- 2016Credit spreads as an equity cash regime filter
- 2016The summer lull is a context error
- 2019Financial sector spreads as regime tells around a global stablecoin
- 2019The negative-yield regime as an equity intermarket filter