2019issue C0748-56
Constructing exponential-deviation-bands from a midline-average
Exponential-deviation-bands center on a midline-average of close and set width from a recursively smoothed absolute deviation. After the lookback elapses, the three series can be rebuilt from that lookback, a deviation-multiplier, and a choice of simple or exponential midline.
- The envelope is centered on a midline-average of close, simple or exponential, over a chosen lookback, and the first width measure is the absolute distance from that midline to the latest close.
- That absolute distance is recursively smoothed with the smoothing-multiplier, which is 2 divided by one plus the lookback length, so recent deviations receive more weight than older ones.
- Upper and lower envelopes add and subtract the smoothed deviation scaled by a deviation-multiplier, commonly set to 2, from the same midline-average.
- Relative to a standard-deviation envelope of the Bollinger type, the construction is described as more recent-weighted and as producing a lower breakout-count.
Center the band on a midline-average
The construction centers a band on a midline-average of close over a chosen lookback. That midline-average may be a simple moving average or an exponential moving average.
The first width measure is the absolute distance from this midline-average to the latest close.
Apply the smoothing-multiplier
That absolute distance is recursively smoothed with the same multiplier used in exponential averaging. The smoothing-multiplier is 2 divided by one plus the lookback length, so recent deviations receive more weight than older ones.
Form the outer envelopes
Upper and lower envelopes are formed by adding and subtracting the smoothed deviation, scaled by an explicit deviation-multiplier, from the same midline-average. The deviation-multiplier is commonly set to 2.
Exponential-deviation bands on daily NYSE Composite
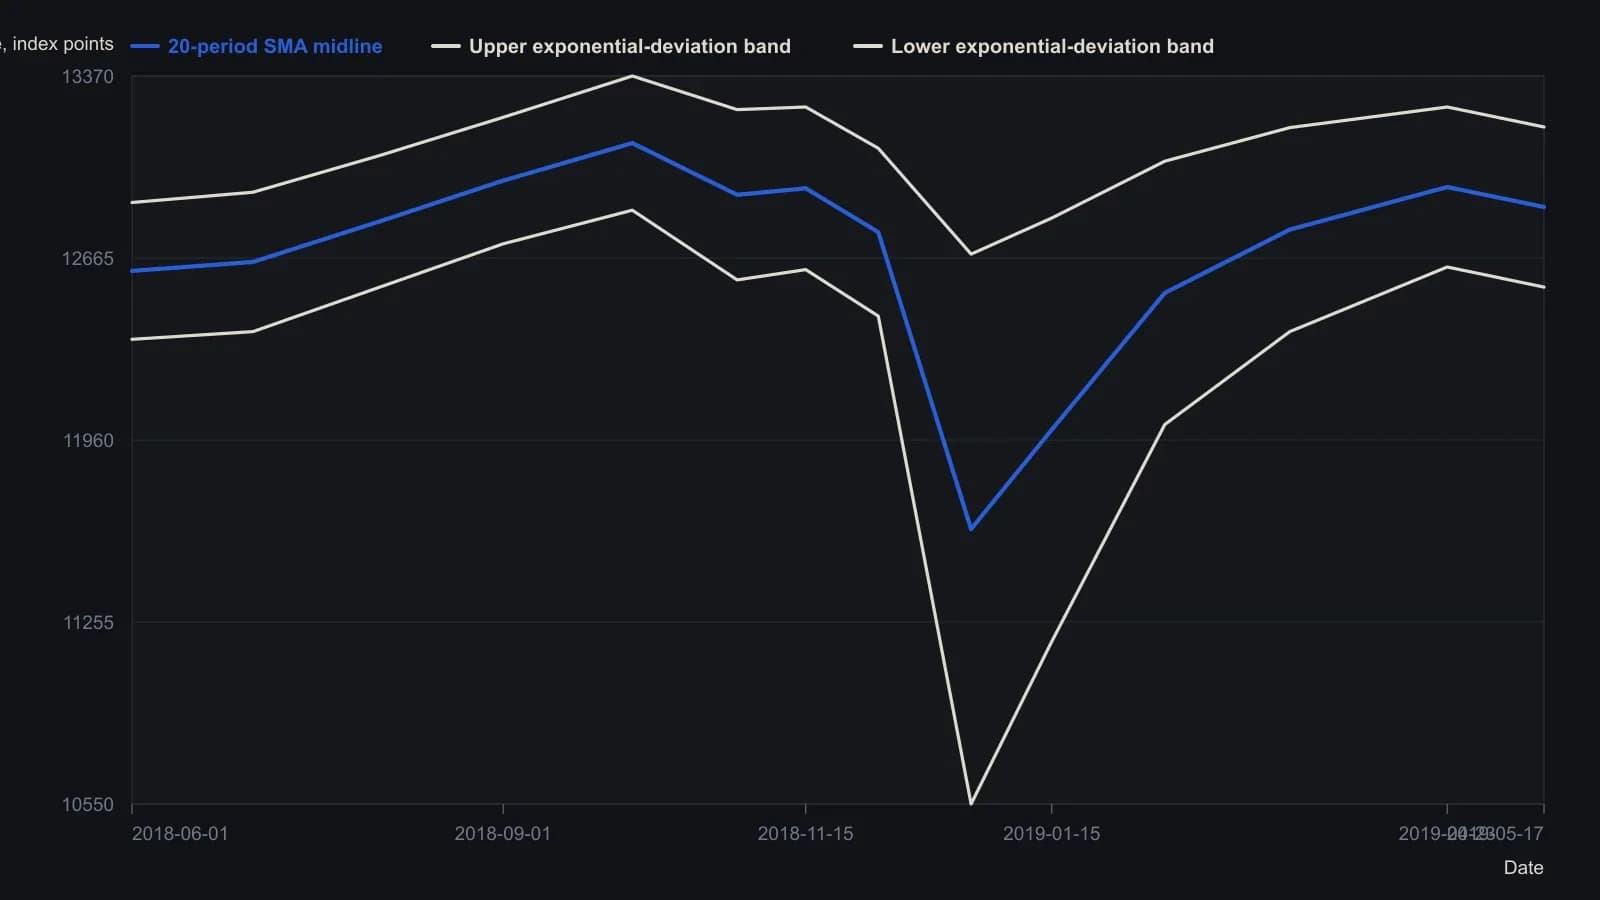
Chart header prints TASC Jul 2019 inputs Periods=20, DevMult=2, UseSMA=true, with last-bar readout midline 12862.47, upper 13172.57, lower 12552.38, last 12738.36 on 17 May 2019. A second, faster overlay is visible on the source chart and was not digitized. Midline points other than the last bar are the midpoint of the two envelopes, which is the indicator identity Upper/Lower = midline ± 2×ED. Raster precision is tens of index points, not the readout’s hundredths.
Contrast with a Bollinger-type envelope
Relative to a standard-deviation envelope of the Bollinger type, this exponential-deviation construction is described as weighting recent data more heavily and producing fewer outer-band crossings. That comparison is a breakout-count contrast, not a claim about use in a market.
Inputs needed to plot the three series
Reference implementations expose the lookback, the deviation-multiplier, and a switch between simple and exponential midlines as the only construction inputs needed to plot the three series after the lookback has elapsed.
All readings on this track · 45 readings
- 1992Constructing volatility-scaled bands with relative strength index confirmation
- 1994Implied volatility as a band-defined regime filter for index options
- 1995Constructing projection bands from least-squares slopes
- 1995Constructing regression projection bands and range oscillators
- 1996Constructing Bollinger bands, percent-b, and stochastics
- 1996Constructing mechanical rules from Bollinger Bands and stochastics
- 1996Constructing a standard-error envelope around a linear regression
- 1996Dual-horizon ratio envelopes and regression error channels
- 1997Rational group structure with a trend screen, RSI, and bands
- 1997Asymmetric volatility band construction
- 1998Constructing three-state filters from Bollinger band envelopes
- 1999Combination filters with Bollinger Bands and the relative strength index
- 1999Constructing stochastic timed exits and band-RSI reversals
- 1999Evaluating Bollinger Bands against fixed-width and range-based envelopes
- 2000Constructing a Bollinger Band target as a forward price
- 2001Numeric candlestick encoding with local size bands
- 2001Ranked candlestick sentiment to band-cross entries
- 2002Combining Bollinger Bands, RSI, and a stop-loss
- 2002Bollinger Bands remain filters, not forecasts
- 2002Constructing a stochastic RSI with Bollinger bands
- 2002Constructing a StochRSI and Bollinger mechanical system
- 2003Constructing volatility-scaled Bollinger envelopes
- 2003Why tick breadth fails as a market personality
- 2005Constructing Bollinger bands versus fixed trading bands
- 2006Squared versus absolute deviation in envelope construction
- 2006Confirming yen crossovers with implied volatility and bands
- 2006A daily candle reversal is a hypothesis until shorter sessions fail at the same zone
- 2008Rebuild the Relative Strength Index as price-scale bands
- 2008Reading Relative Strength Index extremes on one price axis with Bollinger Bands and moving averages
- 2011Three-filter confirmation for short-swing futures
- 2011Constructing an inverse Fisher stochastic with bands and averages
- 2012Constructing a Bollinger Band indicator suite
- 2012Stacking price extremes, crossovers, bands, and MACD
- 2012Adaptive Bollinger band impulse, trend, and momentum filters
- 2013Rescaling stochastic, percent-B, and wave-count parameters
- 2014Industry-group quartile pivots as a Bollinger Bands case study
- 2014Bollinger Bands as adaptive price envelopes: a 2014 classroom case
- 2016Trend-channel entry rules from stacked moving averages
- 2016A permission stack for Bollinger, RSI, and the 50-period average
- 2017Constructing weighted Bollinger bands and volume averages
- 2017Four swing-entry rules that share a timed exit
- 2017Two-wave monthly cycles as a regime filter
- 2019Constructing exponential-deviation-bands from a midline-average
- 2020Critiquing exponential variants of Bollinger Bands
- 2020Constructing selectable volatility and moving-average bands