2003issue C101
Constructing volatility-scaled Bollinger envelopes
The envelope is three lines: a middle moving average and outer lines placed two standard deviations away from that path. Width can change with volatility, and the relative strength index is specified only to confirm what the finished bands show.
- Build the envelope as a middle moving average with a customary 20-day lookback, then place the upper and lower lines two standard deviations from that path.
- Use a standard-deviation offset instead of a fixed-percentage offset so the envelope can change width with market volatility.
- Read price at or beyond the outer lines as a possible overbought-oversold condition, then apply the stated tightening, continuation, and reversal rules.
- Leave the relative strength index out of the band arithmetic; it is specified only to confirm what the finished envelope shows.
A three-line envelope
The envelope is drawn as three lines: a middle moving average, an upper line, and a lower line. That sandwich is meant to frame a range of price movement. The outer lines sit a stated number of standard deviations away from the central moving average so the width can change with volatility.
Daily EBH with a 20-day two-sigma envelope
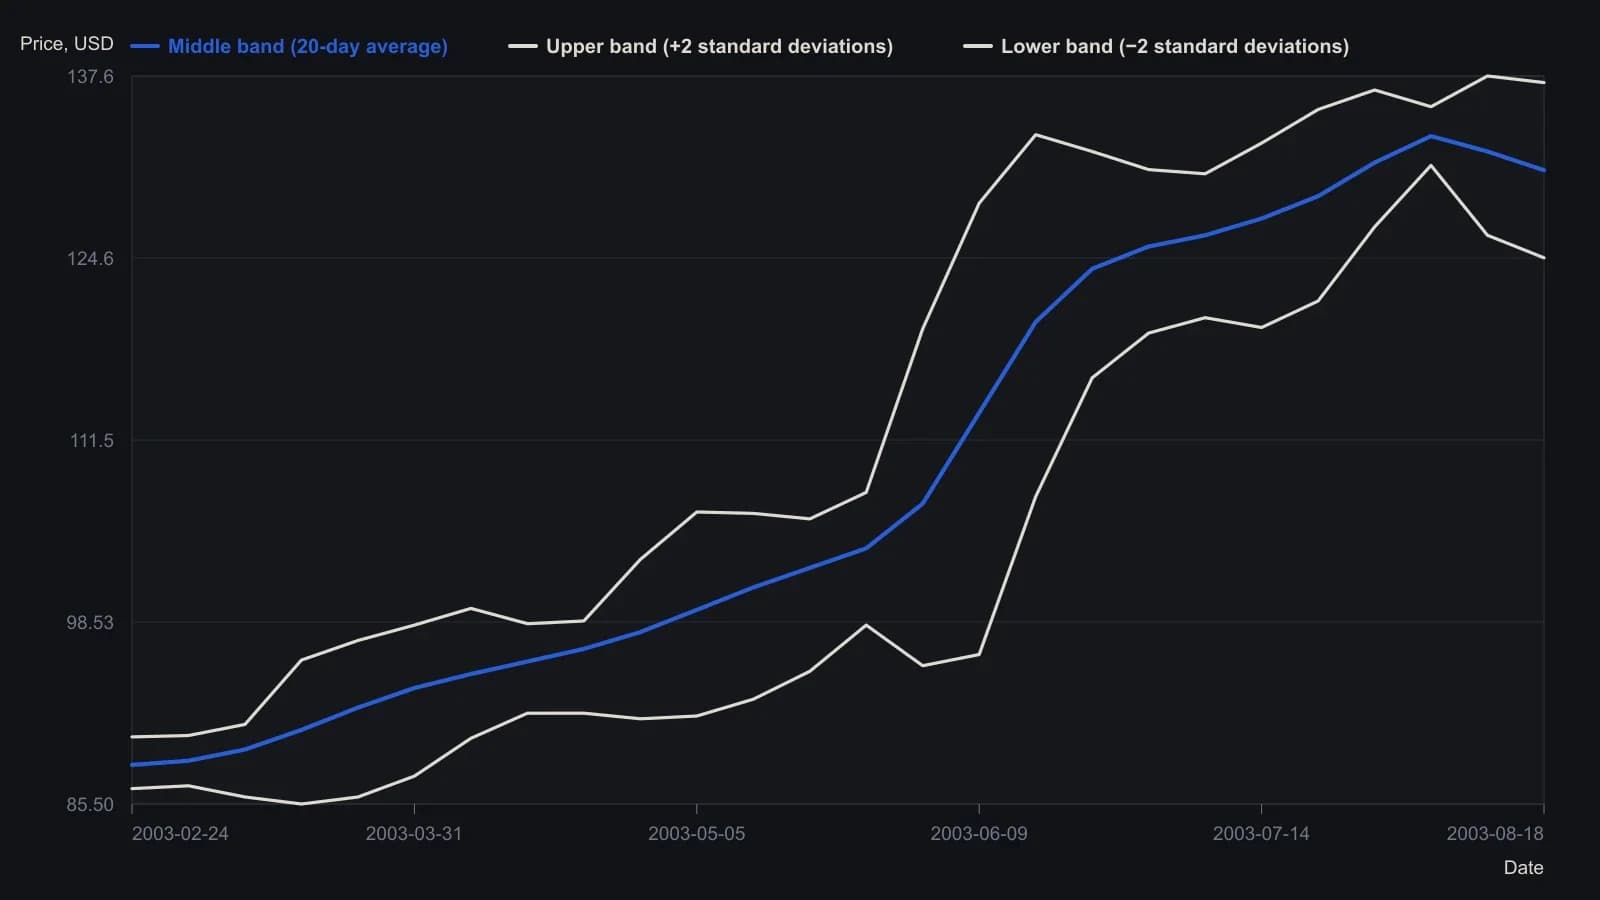
The source fixes the middle path at a 20-day moving average and the offsets at two standard deviations. Only month ticks are dated on the figure; weekly x values are interpolated from those labels. The year 2003 is taken from Stocks & Commodities V. 21:10 (October 2003), not printed on the plot. Intermediate levels are approximate; do not treat them as ticks.
How the middle path and offsets are built
The middle line is specified as a moving average with a customary 20-day lookback. That moving average is the central path of the envelope. The upper line is the middle moving average plus two standard deviations. The lower line is that same average minus two standard deviations.
Those outer placements are the standard-deviation offset: the volatility measure added to and subtracted from the central moving average to locate the upper and lower lines.
Why width is tied to volatility
The outer offsets use standard deviations rather than a fixed percentage so the width can change with market volatility. A fixed-percentage envelope, illustrated with a 3 percent offset, is described as adjusting poorly during extreme advances or declines. Tying band width to the standard deviation of the moving average is presented as making the envelope more adaptable and better at containing prices.
How the finished envelope is read
Price at or above the upper line is treated as a possible overbought condition. Price at or below the lower line is treated as a possible oversold condition. That overbought-oversold reading comes from the construction itself: price at or beyond the upper line may be treated as stretched upward, and price at or beyond the lower line as stretched downward.
Stated reading rules include sharp moves after the bands tighten, continuation when price leaves the bands, reversal after extremes print outside then inside, and a tendency for a move that starts at one band to reach the other.
A confirmation companion, not a band input
The envelope is intended to be used together with the relative strength index to confirm what the bands show. In that role the relative strength index is a companion oscillator used alongside the bands to check observations rather than to compute the bands themselves.
All readings on this track · 45 readings
- 1992Constructing volatility-scaled bands with relative strength index confirmation
- 1994Implied volatility as a band-defined regime filter for index options
- 1995Constructing projection bands from least-squares slopes
- 1995Constructing regression projection bands and range oscillators
- 1996Constructing Bollinger bands, percent-b, and stochastics
- 1996Constructing mechanical rules from Bollinger Bands and stochastics
- 1996Constructing a standard-error envelope around a linear regression
- 1996Dual-horizon ratio envelopes and regression error channels
- 1997Rational group structure with a trend screen, RSI, and bands
- 1997Asymmetric volatility band construction
- 1998Constructing three-state filters from Bollinger band envelopes
- 1999Combination filters with Bollinger Bands and the relative strength index
- 1999Constructing stochastic timed exits and band-RSI reversals
- 1999Evaluating Bollinger Bands against fixed-width and range-based envelopes
- 2000Constructing a Bollinger Band target as a forward price
- 2001Numeric candlestick encoding with local size bands
- 2001Ranked candlestick sentiment to band-cross entries
- 2002Combining Bollinger Bands, RSI, and a stop-loss
- 2002Bollinger Bands remain filters, not forecasts
- 2002Constructing a stochastic RSI with Bollinger bands
- 2002Constructing a StochRSI and Bollinger mechanical system
- 2003Constructing volatility-scaled Bollinger envelopes
- 2003Why tick breadth fails as a market personality
- 2005Constructing Bollinger bands versus fixed trading bands
- 2006Squared versus absolute deviation in envelope construction
- 2006Confirming yen crossovers with implied volatility and bands
- 2006A daily candle reversal is a hypothesis until shorter sessions fail at the same zone
- 2008Rebuild the Relative Strength Index as price-scale bands
- 2008Reading Relative Strength Index extremes on one price axis with Bollinger Bands and moving averages
- 2011Three-filter confirmation for short-swing futures
- 2011Constructing an inverse Fisher stochastic with bands and averages
- 2012Constructing a Bollinger Band indicator suite
- 2012Stacking price extremes, crossovers, bands, and MACD
- 2012Adaptive Bollinger band impulse, trend, and momentum filters
- 2013Rescaling stochastic, percent-B, and wave-count parameters
- 2014Industry-group quartile pivots as a Bollinger Bands case study
- 2014Bollinger Bands as adaptive price envelopes: a 2014 classroom case
- 2016Trend-channel entry rules from stacked moving averages
- 2016A permission stack for Bollinger, RSI, and the 50-period average
- 2017Constructing weighted Bollinger bands and volume averages
- 2017Four swing-entry rules that share a timed exit
- 2017Two-wave monthly cycles as a regime filter
- 2019Constructing exponential-deviation-bands from a midline-average
- 2020Critiquing exponential variants of Bollinger Bands
- 2020Constructing selectable volatility and moving-average bands