2001issue C101-6
A two-gate classroom test for a two-window momentum trend filter
First ask whether recent net displacement outruns a quieter unsigned-momentum window, then let a same-length direction sum choose the side. Editorial grading asks whether one locked next-open reversal recipe stays a single procedure when only lookback and market list change.
- The trend filter is a same-length comparison of recent net momentum with a longer unsigned-momentum window, read as trend when positive and consolidation when negative.
- The momentum strategy uses that filter as a permission gate and the same-length momentum sum as the side: it buys the next open when both are positive, and sells the next open when the filter is positive and the direction sum is negative.
- Once a side is on, the tested procedure holds until the opposite entry appears, so the pair is a reversal rule rather than a stand-aside cycle.
- Robustness testing repeats one locked reversal procedure across markets and lookback lengths instead of retuning each series.
What the two gates ask
The archive pairs a trend filter with a same-length direction sum. Editorial classroom reading treats that pair as two gates. The first gate asks whether recent net displacement outruns a quieter unsigned-momentum window. The second gate lets the direction sum choose the side.
How the filter marks trend versus consolidation
The trend filter is a same-length comparison of recent net momentum with a longer unsigned-momentum window. A positive filter reading is treated as trend and a negative reading as consolidation.
The filter is built for a quieter prior window of the same length followed by a more one-sided recent window, because signed momenta cancel in two-way ranges but stay signed in a one-way run. The shorter lookback needs a close history long enough to cover both the recent window and the quieter prior window. A continuous-contract worksheet can lay out momentum, absolute momentum, the direction sum, and the filter in that order.
How the next-open rule takes a side
The momentum strategy uses the trend filter as a permission gate and the same-length momentum sum as the side. After the close, the procedure buys the next open when both the filter and the direction sum are positive, and sells the next open when the filter is positive and the direction sum is negative.
Once a side is on, the tested procedure holds until the opposite entry appears, so it is a reversal rule rather than a stand-aside cycle.
How the pair is graded
The archive applied the same lookback to unrelated markets, one contract per signal, a cost per trade, continuous contracts, and a final close-out on the last session. Robustness was checked by leaving entry and exit rules unchanged and replacing the working length with other lengths on the same market book.
The archive write-up frames the filter as usable alone or with other rules, but still incomplete as a mechanical procedure without protective and trailing stop logic.
Yen daily close with TDI and direction indicator
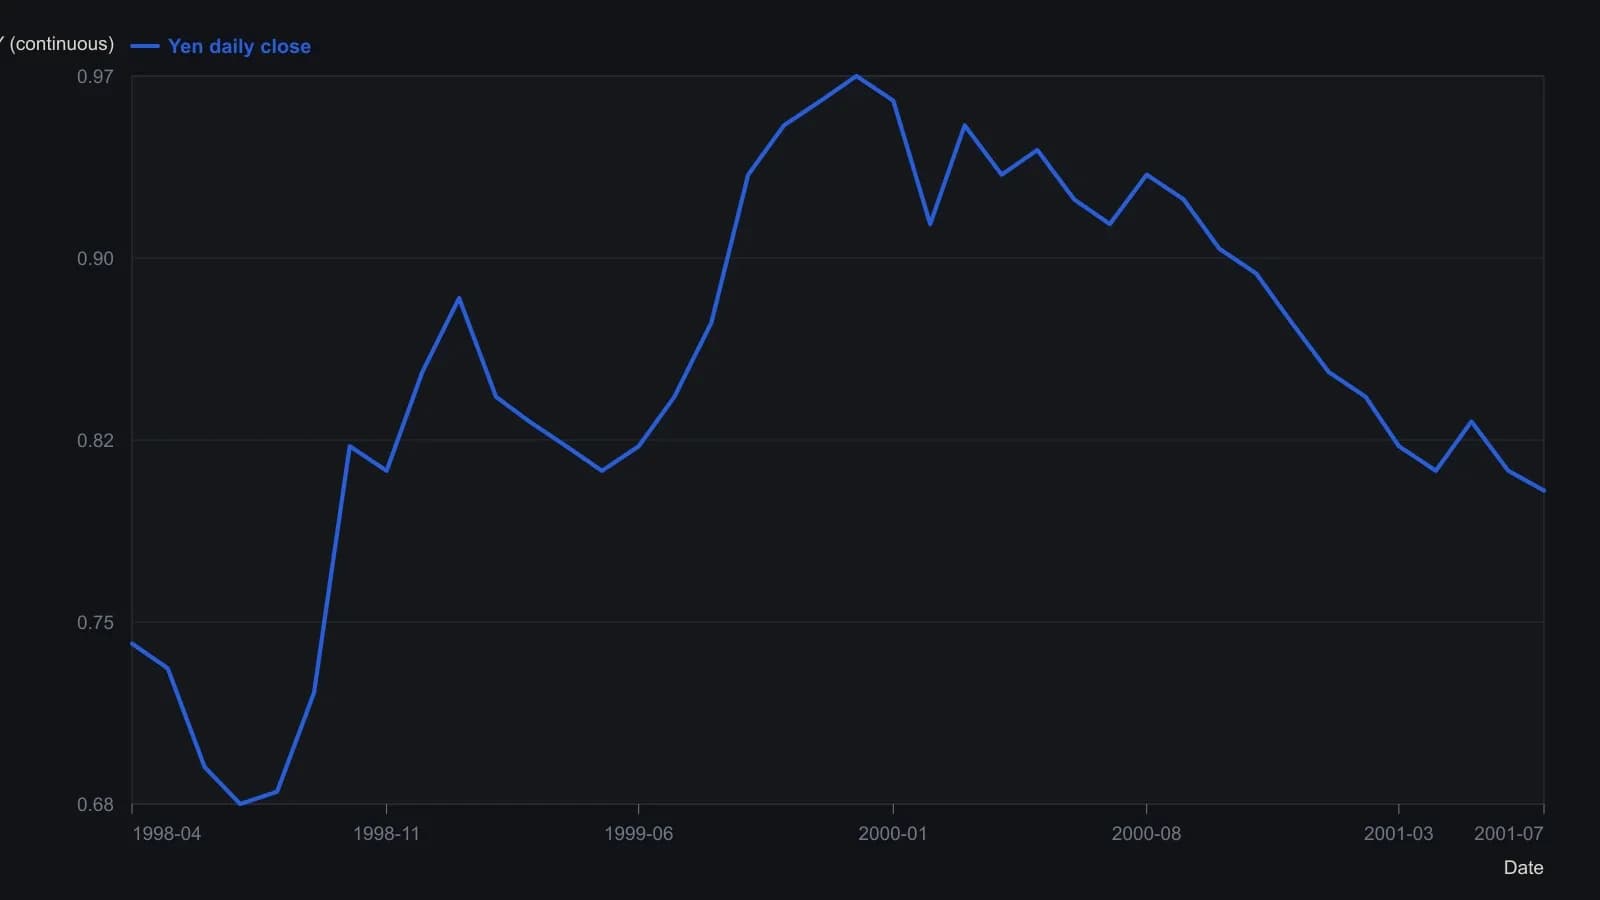
Raster digitization of the printed chart; values are approximate and limited to what the scan can resolve. Header quote is yen 1600 daily close 0.8023 on 16 Jul 2001.
All readings on this track · 51 readings
- 1986Degrees of freedom in trading system optimization
- 1988Walk-forward and neighborhood tests after optimization
- 1988Undisclosed rules block system robustness tests
- 1988Testing re-optimization calendars against random parameter controls
- 1989Binary search limits on multi-peak average grids
- 1989Parameter neighborhoods that survive a shift
- 1990Use profit mapping to keep a cycle and stop plateau
- 1990Why popular indicator optimization fails robustness
- 1991Retesting weighted indicator balances across horizons
- 1992Constructing forecast models with regression, walk-forward, and robustness
- 1992Diagnose regimes before you lock parameters
- 1992When stops change system timing
- 1993Walk-forward halt rules for forecast models
- 1994Walk-forward evaluation of genetic index rules
- 1995Input pruning as walk-forward system evaluation
- 1995Critiquing neural nets as incomplete trading systems
- 1996Rebuild the equity-path ratio before it ranks a designed system
- 1996Parameter grids can fit random walks
- 1996Walk-forward analysis belongs in the design of a mechanical trading system
- 1997When a holdout fails, discard the rule set
- 1997Test rewarded rule breaks before replacing the system
- 1997Walk-forward rules keep system research from rewriting live trades
- 1999Keep a channel-breakout to two lookbacks and test neighbor stability
- 1999Constant investment size in stock system evaluation
- 2000Forcing optimization maps mechanical system failure boundaries
- 2000Robust parameter selection with surface charts
- 2001A two-gate classroom test for a two-window momentum trend filter
- 2002How a two-sided continuation factor becomes a testable trend rule
- 2002Evaluating two-window trend intensity as a reversal rule
- 2003Discounting speculative bubbles in system robustness tests
- 2003Walk-forward evaluation of locked stochastic oscillator rules
- 2003Critiquing mechanical system design after extreme price regimes
- 2004Evaluating a two-window trend trigger
- 2005Grade backtested signals with holdouts and optimization plateaus
- 2006Reserved-sample evaluation of trading system design
- 2006Walk-forward critique of hindsight crossover systems
- 2008Condition-matched walk-forward evaluation for mechanical systems
- 2011Session-split evaluation of regular and overnight systems
- 2012Walk-forward evaluation as operator rehearsal
- 2013Two-window evaluation of mechanical trading systems
- 2013Walk-forward filter selection for repeated-median velocity
- 2014Walk-forward evaluation for fading-memory velocity systems
- 2015Test oscillator events before tuning rules
- 2016Walk-forward evaluation of a five-parameter parabolic stop-and-reversal
- 2016Walk-forward optimization without curve fitting
- 2017Optimization without overfitting in trend-system evaluation
- 2017Parameter stability is a better guide than a larger crossover grid
- 2018Point-in-time universes for system evaluation
- 2018Walk-forward robustness evaluation for optimized systems
- 2018Critiquing breakout systems through robustness tests
- 2018A critique of parameter fitting in system design