1992issue C021-5
Evaluating breakout and CCI rules as complete mechanical procedures
A historical study placed an original breakout procedure and an eleven-unit Commodity Channel Index oscillator on the same December 1991 S&P 500 series so both rule sets could be judged side by side as mechanical-trading-system procedures under shared fill timing and exit discipline.
- An original breakout procedure and an eleven-unit Commodity Channel Index oscillator were placed on the same December 1991 S&P 500 series, observed from March through September, so the rule sets could be evaluated side by side.
- Buy and sell entries and exits used next-open-fill, with execution on the open of the session after the signal rather than on the signal bar.
- Oscillator trades used signal-to-signal-hold so the two procedures were not compared under unequal exit freedom.
- The evaluation applied no stop orders. Omitted stops were a test-design choice, and a live implementation would typically add loss-limiting exits. Each trade was recorded as a point-result.
A shared series for two rule sets
The study placed an original breakout procedure and an oscillator procedure on the same market series so their rule sets could be evaluated side by side. The shared series was the December 1991 S&P 500 contract observed from March through September.
A breakout-system is a rules-based procedure that issues buy, sell, or stand-aside signals when price crosses a defined range or level. The oscillator specification used an 11-unit Commodity Channel Index. A commodity-channel-index is a lookback oscillator built from ordered price observations over a fixed sampling window and used here as an eleven-unit signal source.
A mechanical-trading-system is a complete, testable bundle of entry, exit, and abstention rules applied without discretionary overrides during the evaluation window.
Frozen fills and equal exit discipline
Buy and sell entries and exits were filled on the open of the session after the signal, not on the signal bar itself. That next-open-fill rule applied to both procedures, so fill timing was not a free variable in the comparison.
Oscillator trades were held until another signal appeared. That signal-to-signal-hold kept the oscillator from receiving independent exit freedom that the breakout procedure did not share.
Stops left out by design
The evaluation applied no stop orders. The write-up treats omitted stops as a test-design choice and notes that a live implementation would typically add loss-limiting exits.
Results recorded in points
Each trade result was recorded as a point-result, meaning points gained or lost rather than a dollar amount.
Points won or lost on each mechanical trade
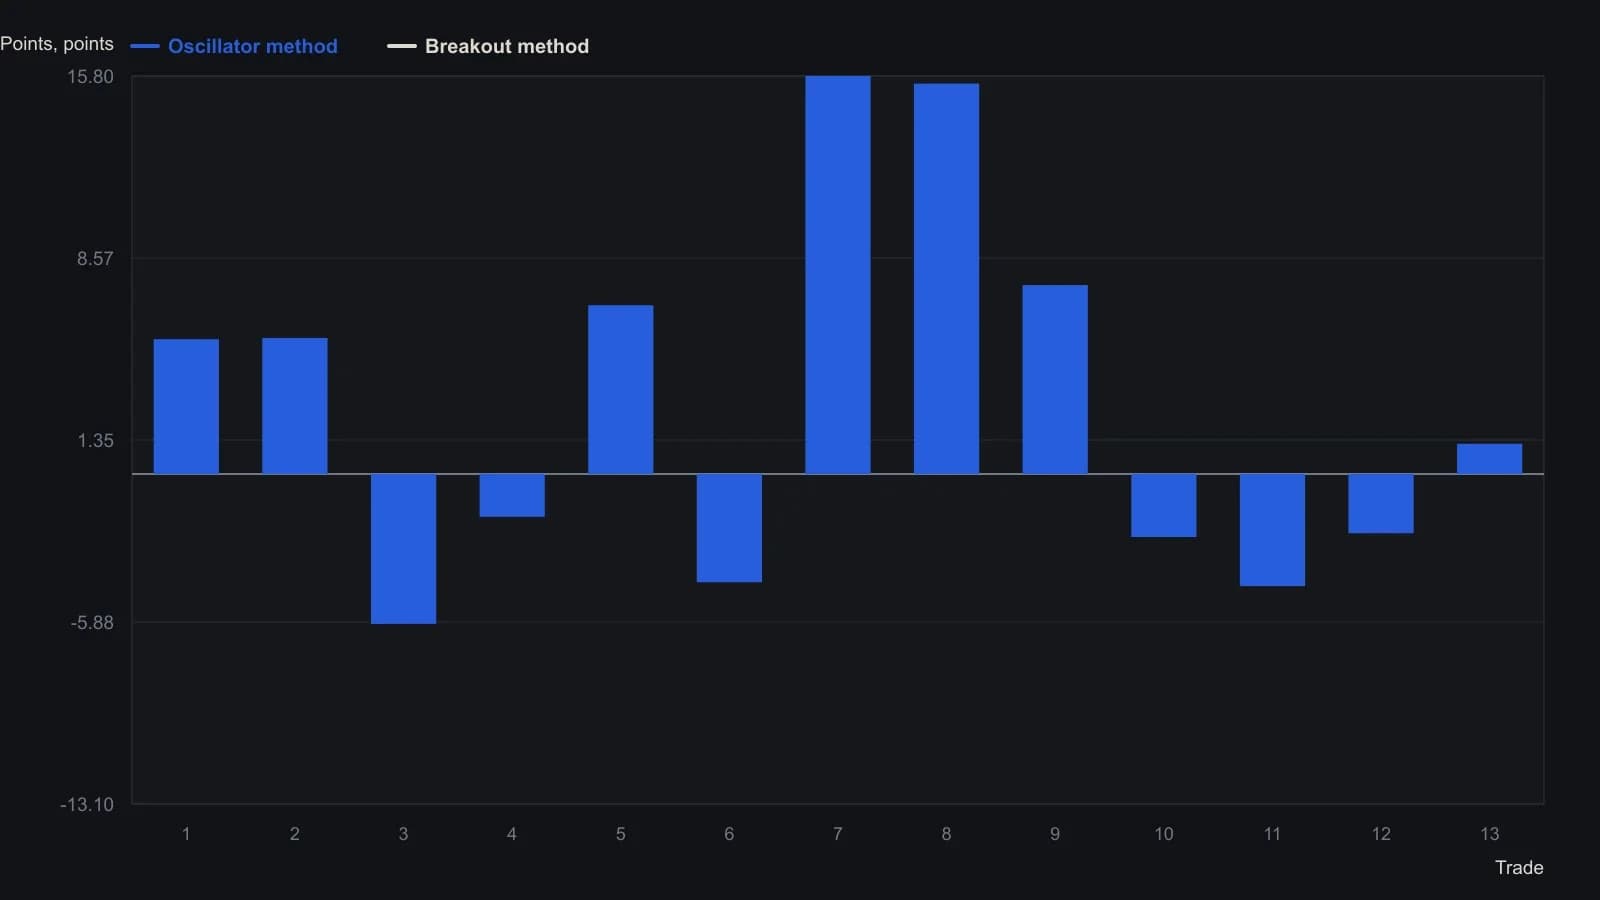
Oscillator positions stay open until the next signal so the two rule sets share the same exit discipline. Stops were omitted on purpose. Blank point cells were taken from the printed next-day opens (breakout trade 1: 374.90 to 376.65; oscillator trade 6: 383.00 to 378.70). Net dollars in the ledgers use $500 per S&P point.
All readings on this track · 39 readings
- 1982Three gates on a 1982 pork-belly short
- 1982Scale-free Commodity Channel Index construction
- 1986Constructing a commodity channel index and a regression price channel
- 1987Constructing scaled OHLC matrices for study overlays
- 1987Constructing the commodity channel, average directional, and relative strength indexes on a shared cycle scale
- 1992Eleven-bar commodity channel index from typical price and mean deviation
- 1992Evaluating Commodity Channel Index breakout versus range rules
- 1992Evaluating breakout and CCI rules as complete mechanical procedures
- 1993Constructing stochastic, RSI and CCI inputs for forecasts
- 1993Nested centered channels with a commodity channel index confirmation gate
- 1993Listed-option timing as three separable clocks
- 1994Constructing an eleven-period commodity channel index
- 1994Confirming Elliott wave turns with channels and the commodity channel index
- 1995Commodity Channel Index band rules lag zero-line timing
- 1995Building the commodity channel index from typical price
- 1995Staged reversal rules with commodity channel index and average channels
- 1995Commodity channel index construction from typical price to a smoothed zero line
- 2001Reader tests for unfinished lookback oscillators
- 2002Constructing the commodity channel index from typical price
- 2003Breadth-filtered commodity channel index entry and exit rules
- 2003Constructing the Commodity Channel Index from typical price and scaled deviation
- 2003A shallow, poorly participated advance is an unconfirmed trend
- 2003CCI and RSI parameter defaults as scaling conventions
- 2003A cost and capital audit of a Commodity Channel Index trade engine
- 2003Commodity channel index peak divergence as an exit after twin patterns
- 2004Constructing the Commodity Channel Index from typical price
- 2004Constructing the Commodity Channel Index from typical price and mean deviation
- 2006Building custom indicators from the Commodity Channel Index, a least squares moving average and a rule-based entry
- 2012Confirming breakouts and retracements with CCI, ADX, and averages
- 2012Stacking oscillator lookbacks into a heatmap mosaic
- 2013Constructing a consensus and volatility-normalized value oscillator
- 2013Walk-forward system evaluation with a commodity channel index and chandelier exits
- 2014Dual detrended oscillators and dual Bollinger Band channels
- 2014RSI, CCI, and moving-average trend-filter construction
- 2014Dual RSI, a moving average, and CCI as a confirmation stack
- 2017Constructing dual-average cross and channel-index filters
- 2018Treat CAM as a classification layer before confirmation becomes an entry
- 2018Four-state slope labels gated by a moving average and a commodity channel index
- 2018Deviation-Scaled Moving Average construction from a two-bar difference