2011issue C0270-73
Constructing a Spearman rank trend filter
A rank-correlation oscillator is assembled from a lookback window of prices, their time order, a short simple moving average, and fixed overbought and oversold bands. This archive note walks through that construction so the same steps can be rebuilt without treating platform code as a trading recipe.
- The constructed filter is Spearman rank correlation between a lookback window of prices and their time order, producing a bounded series used to read trend intensity.
- Fixed bands of 80 and -80 are specified as overbought and oversold thresholds on that rank-correlation series.
- A three-bar simple moving average of the series is the specified crossover reference, and zero crossings are specified as an additional construction event.
- Platform implementations apply the same ranked-price construction as a custom study or compiled indicator, not as a new taxonomy of methods.
A bounded reading from ranked prices
The constructed trend filter is defined as Spearman rank correlation between a lookback window of prices and their time order. That calculation produces a bounded series used to read trend intensity.
The same series is the core of a constructed reading of trend intensity and potential turning points. Recent prices are ranked against time order, and the resulting series is later compared with its own average and with fixed bands.
Bands, average, and zero crossings
Fixed construction bands of 80 and -80 are specified as overbought and oversold thresholds on the rank-correlation series.
A three-bar simple moving average of the rank-correlation series is specified as a crossover reference in the same construction. That short simple average is not a price average here. It is an average of the rank-correlation series and serves as the crossover reference for the constructed filter.
Zero crossings of the rank-correlation series are specified as an additional construction event alongside those average crossovers.
S&P 500 daily with Spearman oscillator
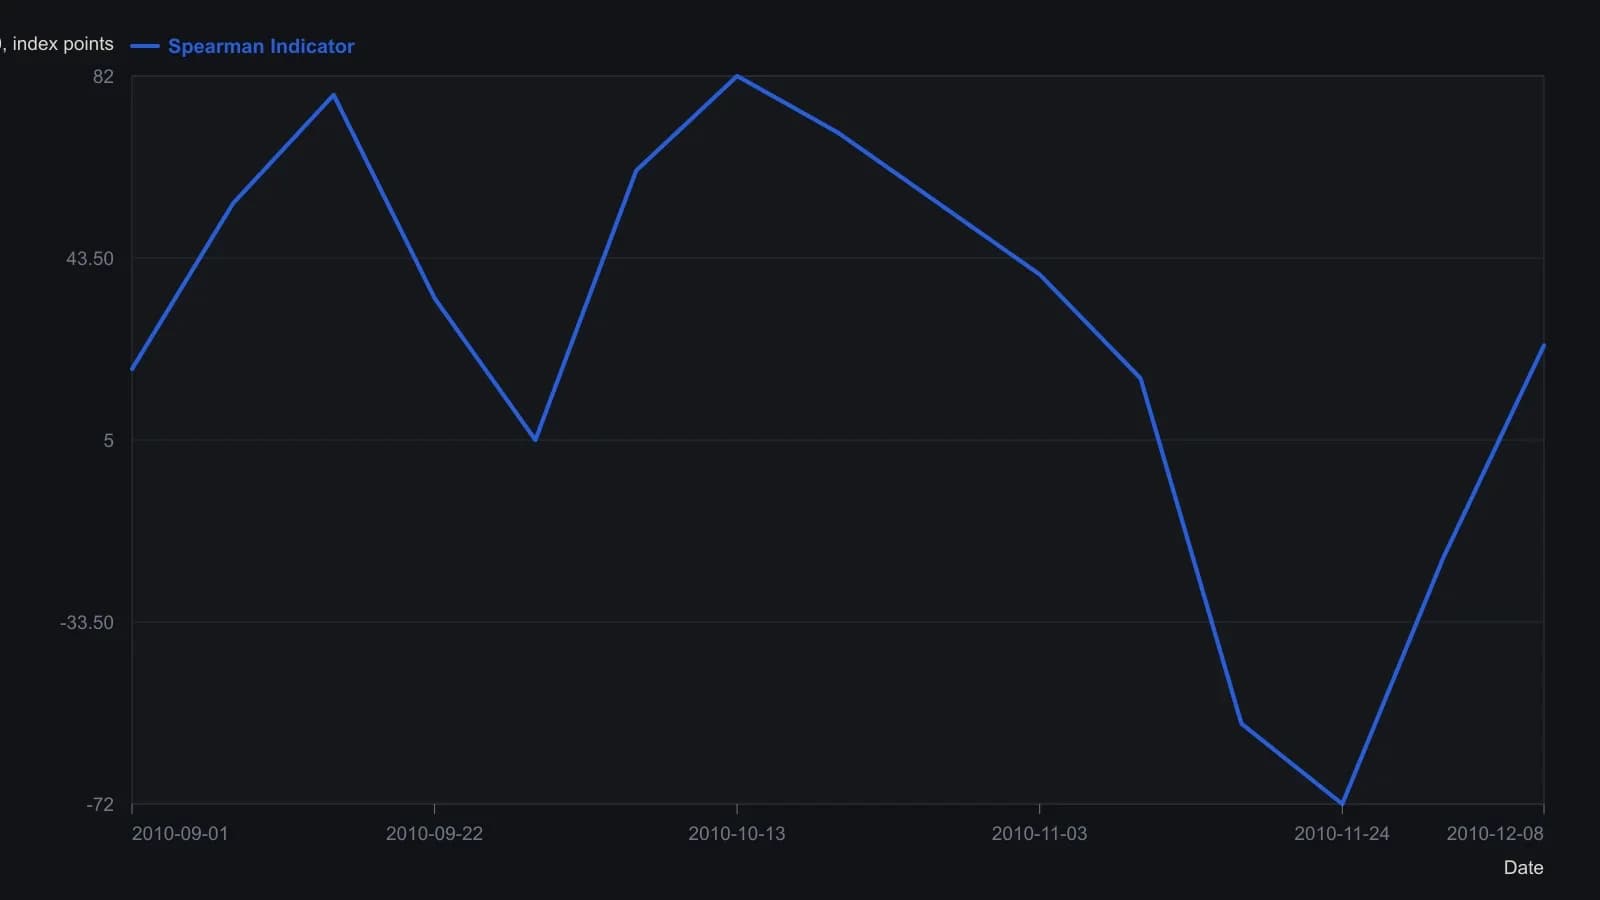
Coordinate readout from a dark-theme platform screenshot; oscillator readings are approximate to about ±5 units and the last few December bars sit near 1240.
A comparison baseline, not a new method class
A relative strength index is used here as the comparison baseline. It is a bounded oscillator against which the rank-based trend-strength reading can be placed.
Platform implementations apply the same ranked-price construction as a custom study or compiled indicator rather than as a new taxonomy of methods. The construction remains a trend filter assembled from ranked prices, a short average of that series, and fixed bands.
All readings on this track · 33 readings
- 1988Opening-range brackets, a two-bar trend filter, and bounded stops
- 1990Bezier-curve price trend filter
- 1992Constructing a damping-index trend filter
- 1992Building a random walk index trend filter
- 1992Phase diagrams for moving-average trend filters
- 1993Volume-weighted change smoothing and trend ranking
- 1993Concurrent highest-low filter with a largest-low-fall trigger
- 1994Unit-invariant trend filters and the c-test
- 1995Constructing cup and cap entries with a three-bar net line
- 1997Why a daily timing evaluation depends on interval, lookbacks, and the fitting objective
- 2001A volume budget clock for trend-segment construction
- 2001Keep three jobs separate when you test a composite score
- 2002Evaluating the weekly four-percent close filter as a market-state procedure
- 2003Constructing a confirmed zigzag trend filter
- 2004Decompose high, low, and close into separate forecast streams
- 2005Three-state moving-average breakout bar coloring
- 2005Constructing a volume and move-adjusted trend filter
- 2005A fifty-day average breakout as a trend permission filter
- 2005Current-bar inclusion can mute a stochastic channel break
- 2006A stochastic oscillator gated by a long-term exponential average
- 2010A construction test for a modified volume-price trend filter
- 2011Constructing a Spearman rank trend filter
- 2013Constructing a repeated-median slope as a resistant trend filter
- 2014Combining a relative-strength index and trend filters for oversold setups
- 2014Price-rooted lookbacks for a relative strength index, a moving average, and a trend filter
- 2015Evaluating next-session intermarket range forecasts
- 2018Read the intermarket weight matrix first, then the predicted moving-average filter
- 2018Constructing the stiffness trend filter from moving-average holds
- 2018The averaging kernel and the lagged trend gate are separate specifications
- 2019A trend filter is not ready to compare until portfolio constraints are written down
- 2019Lookback, threshold, and position-capacity for a stiffness trend-filter
- 2020Combining a trend filter with a moving average and a stochastic oscillator
- 2020Constructing a relative-strength oscillator with a rank-agreement trend filter