2018issue C1210-15
Evaluating rare consecutive-close mean-reversion entries
This archive note reconstructs a historical workflow that scored mean-reversion buys as one locked procedure: a path-average marked a stretch-sequence, a written rule fired, a calendar-exit closed the hold, and the same hold was kept only after a holding-period-benchmark test and a cross-instrument-screen.
- A twenty-session path-average of closes was used only to locate short-term stretch-sequences, not as a standalone trade.
- Thirteen candidate sequences were scored as buy rules on one broad U.S. equity fund; two stretch-sequences were retained.
- A qualifying stretch-sequence bought immediately and used a calendar-exit twenty-two business sessions later, with no price-based stop described.
- Each hold was compared with a holding-period-benchmark, then the same entry, hold, and significance test were repeated as a cross-instrument-screen.
What the evaluation locked in place
This archive article reconstructs a historical workflow for evaluating mean-reversion entries as one written procedure. A path-average marked where short-term price had stretched. A stretch-sequence supplied the buy rule. A calendar-exit closed the position after a set number of business sessions.
The first scoring used a broad U.S. equity fund. Only after that step were surviving rules sent through a cross-instrument-screen.
Using a path-average to mark a stretch-sequence
A twenty-session simple moving average of closes served as the path-average. It was a reference path for locating short-term price stretches, not a trade by itself.
A stretch-sequence was a counted run of closes that all sat below that path-average, or a counted run of closes that all fell from the prior close.
Scoring candidate buy rules on one fund
Thirteen candidate sequences were scored separately as buy rules on a broad U.S. equity fund before any wider check.
Two sequences were retained as stretch-sequences: nine consecutive closes below that path-average, and six consecutive declines in the close.
Firing the rule and using a calendar-exit
A qualifying stretch-sequence triggered an immediate purchase. The position was sold twenty-two business sessions later. That sale was a calendar-exit: it was scheduled from the entry date and did not depend on later price. No price-based stop was described.
Testing against a holding-period-benchmark
Each sequence's one-month change was compared with the same fund's unfiltered one-month average. That unfiltered average is the holding-period-benchmark: the average change over the same hold with no entry filter applied. The comparison used a Student's t-test.
On that first fund the nine-close rule appeared twenty-two times and the six-decline rule seventeen times, against 1,592 ordinary one-month windows.
Repeating the same hold as a cross-instrument-screen
The two surviving rules were reapplied, with the same hold, to nine further funds spanning equities, gold, a currency, energy, and Treasuries. That repetition is the cross-instrument-screen: the identical entry, hold, and significance test on additional funds.
Fund-by-fund tables used a ninety-five percent threshold as a stricter outperformance screen and a seventy-five percent threshold as a broader one.
Nine closes below the 20-day average: one-month trial returns versus each ETF's unfiltered average
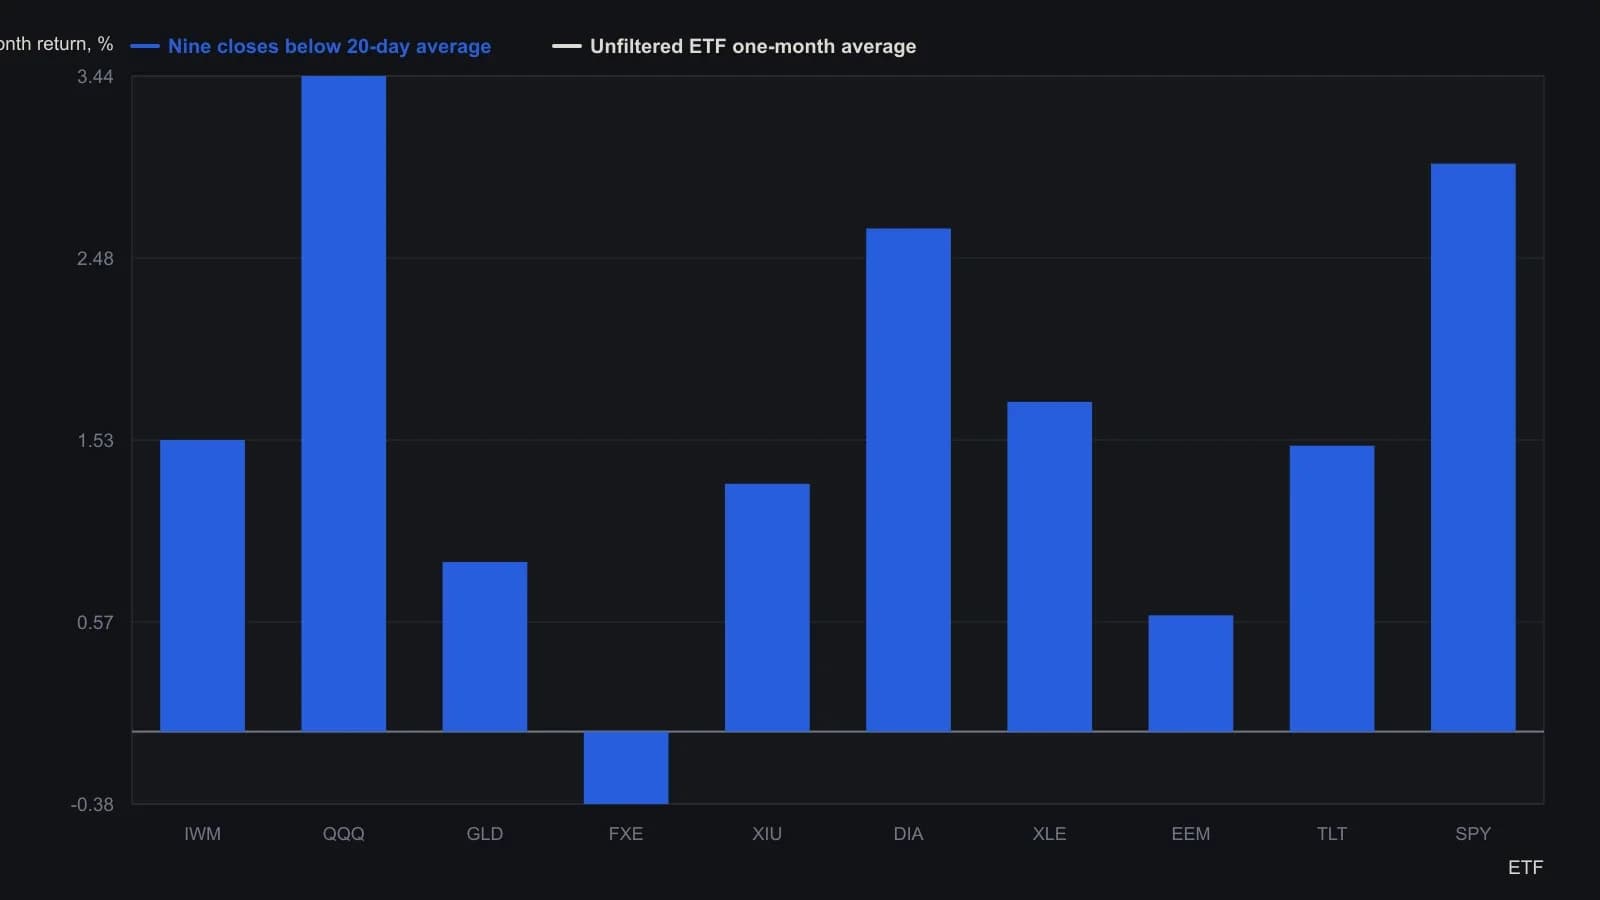
Each signal was held 22 business days and compared with a Student's t-test to that ETF's unfiltered one-month average. The authors' sample window is January 2010–June 2016. Asterisks in the source mark no statistical difference; those ETFs are still shown at the reported means.
How the write-up described the sample window
The recorded sample ran from January 2010 through June 2016. The write-up itself treated that window as generally rising.
All readings on this track · 36 readings
- 1986A futures fade as one range, order, and secrecy procedure
- 1992Constructing the mass-index range-reversal procedure
- 1993Switch trend following and mean reversion with an equity-curve filter
- 1994Evaluating weekly trend-following and mean-reversion timing rules
- 1996Dual-horizon bands for a precious-metals cash switch
- 1997Constructing a moving regression oscillator
- 1997Regime-dependent long and short rules in mechanical systems
- 2002A same-session pair book with a morning-fixed volatility envelope
- 2004Combining noncorrelated trend and reversion systems
- 2004Failed-breakout overlays on trending markets
- 2004Rank rotation after a path split, then Robustness testing
- 2004Range-bound tape as a filter for trend and oscillator rules
- 2005A moving-average short pullback that is only in scope in a decline
- 2006Constructing an adaptive price zone from a double-smoothed range
- 2007Two-period relative strength index versus a one-week universe baseline
- 2008Building ETF mean-reversion entries with a two-bar washout
- 2008Rebuild a short-period stochastic as a premier stochastic oscillator
- 2008A three-market regime map for equity bounces and dollar cycles
- 2009Option trade adjustment as one testable procedure
- 2010Implied volatility as a May 2010 market-regime lab for the S&P 500
- 2011Treat a large one-day move as a classified event
- 2011Long-call exits, volatility regimes, and spread assignment
- 2011Pairing same-horizon oscillators with a walk filter
- 2012Two-bar band extreme entries with trailing stops
- 2012An eight-month average as a monthly gate for high-yield bonds
- 2014Complete the checklist before the trade
- 2014Coded rules should face one test, not a kinder sample
- 2015Build a mean-reversion basket from one correlation path
- 2015Index dip reversion is horizon and regime dependent
- 2016Treat the end of a trend as a handoff, not a broken system
- 2017A testable half-swing pullback for trend continuation
- 2017Evaluating four swing detection rules for mean reversion
- 2018Intraday breakout and mean reversion as one rule set
- 2018Evaluating rare consecutive-close mean-reversion entries
- 2020Moving-average baselines, price vetoes, and mean reversion
- 2020Two-dimensional FX scaling for trend and reversal systems