2015issue C0749-55
Slow relative-strength index from an exponentially smoothed price
The slow relative-strength index replaces raw price with an exponential moving average, then applies an RSI-style net-change and total-change calculation to that series. Two independent lookbacks set the smoother and the oscillator, and side-by-side charts show a visibly smoother 0-100 line than a same-length relative-strength index.
- The slow relative-strength index is built by replacing raw price with an exponential moving average, then running an RSI-style net-change and total-change calculation on that smoothed series.
- A typical implementation keeps two independent lookbacks: a smoothing length for the exponential average of price, and an RSI length used as a constant of at least 1 for the oscillator averages.
- Each new one-bar change and each new absolute change is blended with a smoothing factor equal to the reciprocal of the RSI length; the change ratio is net-change average over total-change average when the latter is nonzero, otherwise zero, then rescaled to a 0-100 index.
- Side-by-side charts of the slow oscillator and a standard relative-strength index on the same daily index series show that the slow version is visibly smoother.
How the slow oscillator is built
The slow relative-strength index is constructed by first replacing raw price with an exponential moving average, then applying an RSI-style net-change and total-change calculation to that smoothed series. The oscillator therefore reads an exponentially smoothed price series rather than raw closes.
Two independent lookbacks
A typical implementation exposes two independent lookbacks. The smoothing length is the lookback of the exponential average applied to price before RSI-style change ratios are computed. The RSI length is the lookback that updates the net-change and total-change averages inside the oscillator, and it is used as a constant of at least 1.
Seeding and the recursive update
The oscillator update uses a smoothing factor equal to the reciprocal of the RSI length, recursively blending each new one-bar change and each new absolute change into running net-change and total-change averages.
On the first bar the net-change average is seeded as the price difference over the RSI length divided by that length. The total-change average is seeded as a simple average of absolute one-bar changes over the same length. That seed is a moving average of those absolute one-bar changes.
From the change ratio to the index
When the total-change average is nonzero, the change ratio equals the net-change average divided by the total-change average. Otherwise the ratio is set to zero. The indicator is then 50 times that ratio plus one, which rescales the change ratio to the 0-100 oscillator range.
A spreadsheet reconstruction
A spreadsheet reconstruction instead feeds the oscillator with the difference between the close and a moving average. It averages positive and negative differences over a 14-bar window and converts the resulting slow relative strength into a 0-100 index.
When the averages become available
Workbook variants such as SRSI (6,14), SRSI (8,14), and SRSI (8,17) change when the exponential average and the oscillator averages become available. An eight-period smoother starts after eight closes. The 14-bar and 17-bar oscillators start after 14 and 17 recorded differences respectively.
A calmer line than a same-length RSI
Side-by-side charts of the slow oscillator and a standard relative-strength index on the same daily index series are presented to show that the slow version is visibly smoother.
Slow RSI versus 14-day RSI on daily Magellan Health
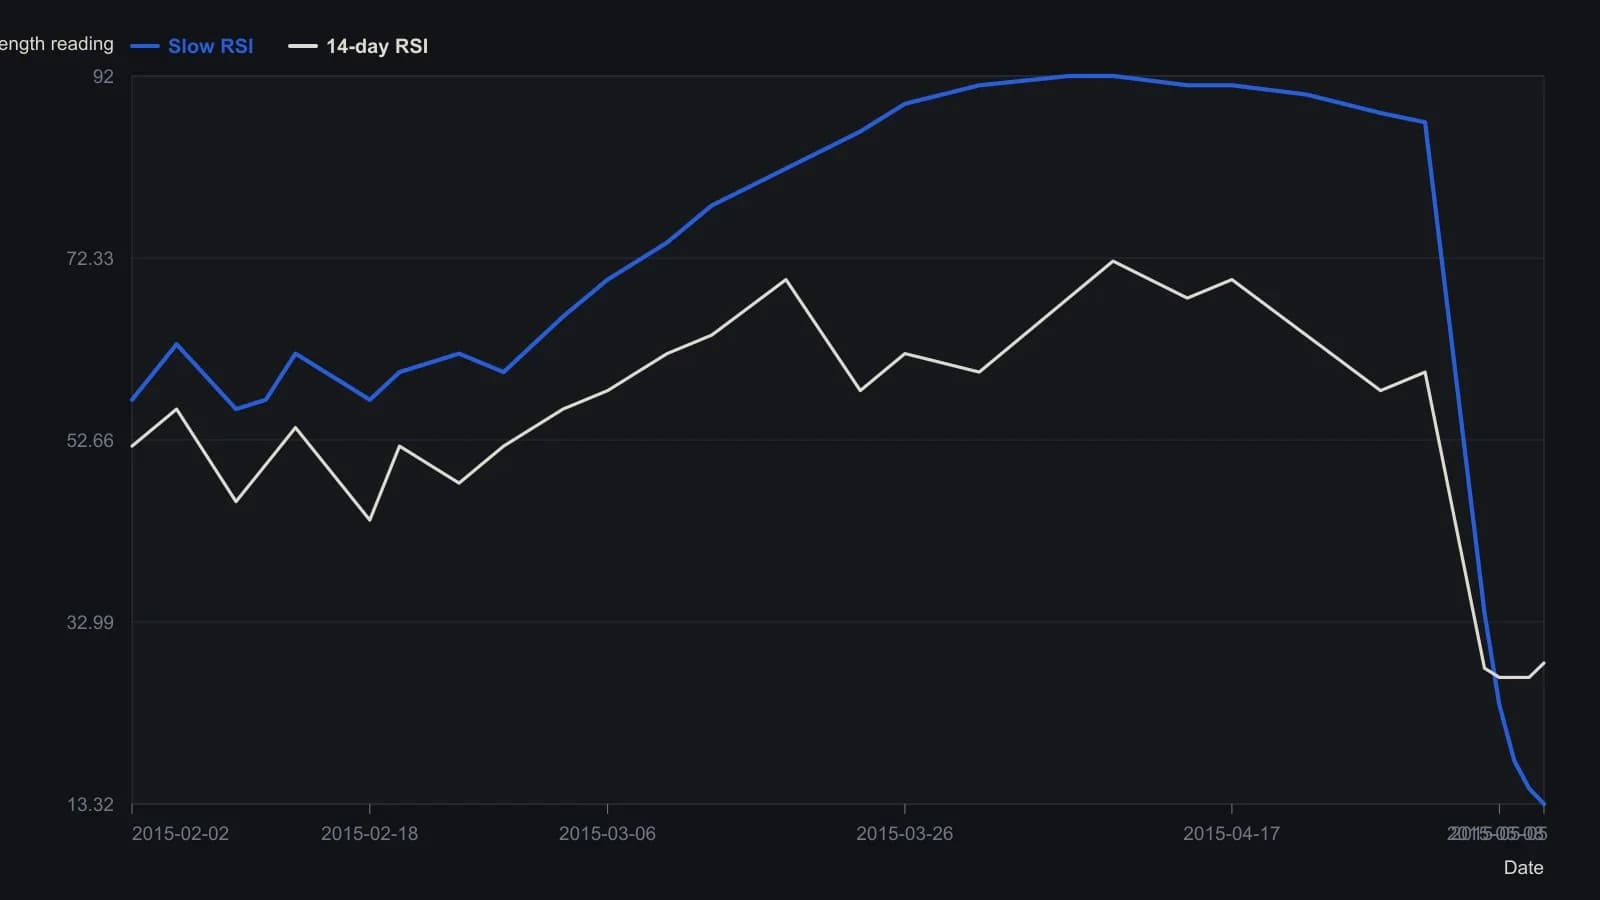
Except for those two closing prints, every interior point is read from the Slow RSI grid at 96/80/64/32/16 and the RSI14 grid at 80/48/32, so values are only good to a few index units. The raster does not resolve each daily tick of the 14-day RSI.
All readings on this track · 41 readings
- 1984Matching average age across price filters
- 1984Residual-impact construction of exponential smoothers
- 1988Constructing simple and exponential moving averages as specified filters
- 1989Evaluating smoothed free reserves and funds-discount spreads
- 1990Integer construction of moving averages and exponential smoothing
- 1990Constructing incremental moving average filters
- 1991Constructing a double-smoothed stochastic oscillator
- 1991Constructing an exponential average from a smoothing weight
- 1991Constructing a double-smoothed momentum oscillator family
- 1991Competing certainty rules from exponential-average conditions
- 1991Hybrid construction of a mechanical timing system from smoothed signals
- 1991Constructing an exponential smoother from a moving-average length
- 1991Equivalent relative-strength-index constructions from a ratio and from smoothed momentum
- 1991Constructing the true strength index from double-smoothed momentum
- 1991True strength index from signed, double-smoothed momentum
- 1992Constructing exponential averages from simple lookbacks
- 1992Constructing exponential averages by the smoothing constant, startup length and lag
- 1992Nested range smoothing and windowed high-low damping
- 1992A weekly equity stance from the discount-bill spread
- 1993Double-smoothed stochastics momentum index construction
- 1993Constructing the true strength index with double exponential smoothing
- 1994Polarized fractal efficiency with a shared exponential smoother
- 1994Five-interval exponential smoothing of ten-interval signed path-efficiency
- 1994Hand-ranked price-volume series with stacked smoothing and stochastic
- 1995Range expansion filter on multi-horizon averages
- 1995The exponential smoothing constant from averaging lag
- 1997Construct a nested-average rainbow band and oscillator
- 1998Filter stacks that combine a moving average with exponential smoothing
- 2002Smoothed relative-strength construction from wilder-averaging and a price prefilter
- 2003Reverse-engineered RSI price targets
- 2004Piecewise trend quality from moving-average reversals
- 2004Nested smoothing recipes versus unaudited oscillator experiments
- 2008Weight construction beyond the N-day label
- 2010A consensus filter for objective RSI and smoothing construction
- 2012Sentiment-zone oscillator from signed closes
- 2012Classic RSI one-over-N smoothing versus the standard exponential average
- 2013Why exponential smoothing uses two over n plus one
- 2015Constructing ratio indicators with moving-average and exponential-smoothing weights
- 2015Slow relative-strength index from an exponentially smoothed price
- 2017Rebuilding the relative strength index as open-scale buy-sell pressure
- 2017Comparing Wilder and exponential smoothing inside a relative-strength index