2015issue C1256
Screen listed futures for executable liquidity first
A listed-futures roster is an execution menu only after an open-interest and volume-scaled liquidity filter has kept markets that can absorb the order. Equal-dollar contract count and effective percent margin belong on that shorter list, not on every listed name.
- A liquidity filter keeps only contracts with enough activity, open interest, and comparable size to enter and exit at an acceptable implementation cost.
- Relative contract liquidity ranks ease of trade from the equal-dollar contract count, total open interest, and a volume scaling factor.
- Equal-dollar contract count and effective percent margin are compared only after a market can absorb the planned order over its life cycle.
- Each comparison column is a proportional measure that is meaningful only against other markets in the same column.
Filter the roster first
The liquidity filter is a pre-trade screen that keeps only contracts with enough activity, open interest, and comparable size to be entered and exited at an acceptable implementation cost. Open interest analysis uses outstanding contract inventory, together with volume and an equal-dollar size factor, to judge whether a market can absorb a planned order.
Editorial: treat a listed-futures roster as an execution menu. Apply the open-interest and volume-scaled liquidity filter first. Use the equal-dollar contract count and effective percent margin only on markets that can absorb the order over its life cycle.
How relative contract liquidity is built
Relative futures liquidity can be ranked by multiplying contract point value, a three-year maximum price move, open interest, and a volume factor usually set from 1 to 4.
Relative contract liquidity is a descending ease-of-trade rank built from the equal-dollar contract count, total open interest, and a volume scaling factor. It equals that equal-dollar contract count times total open interest times a volume factor defined as the greater of 1 or exp(ln(volume) / ln(5000) - 2).
The volume scaling factor is a multiplier, described as usually between 1 and 4, and alternatively as the greater of 1 or an exponential function of volume relative to 5000, that adjusts thin or extreme activity.
Equal-dollar size and effective percent margin
The equal-dollar contract count is how many contracts of one future must be traded so its three-year maximum dollar excursion matches other listed markets. It equals tick dollar value times the three-year maximum price excursion, so one market's size can be compared with another on a common dollar-move basis.
Effective percent margin is margin dollars divided by the three-year dollar range of the contract, expressed as a percentage, for comparing capital locked per unit of historical range. It equals margin dollars divided by the three-year contract dollar range, then multiplied by 100.
Equal-dollar contract count on the most liquid futures
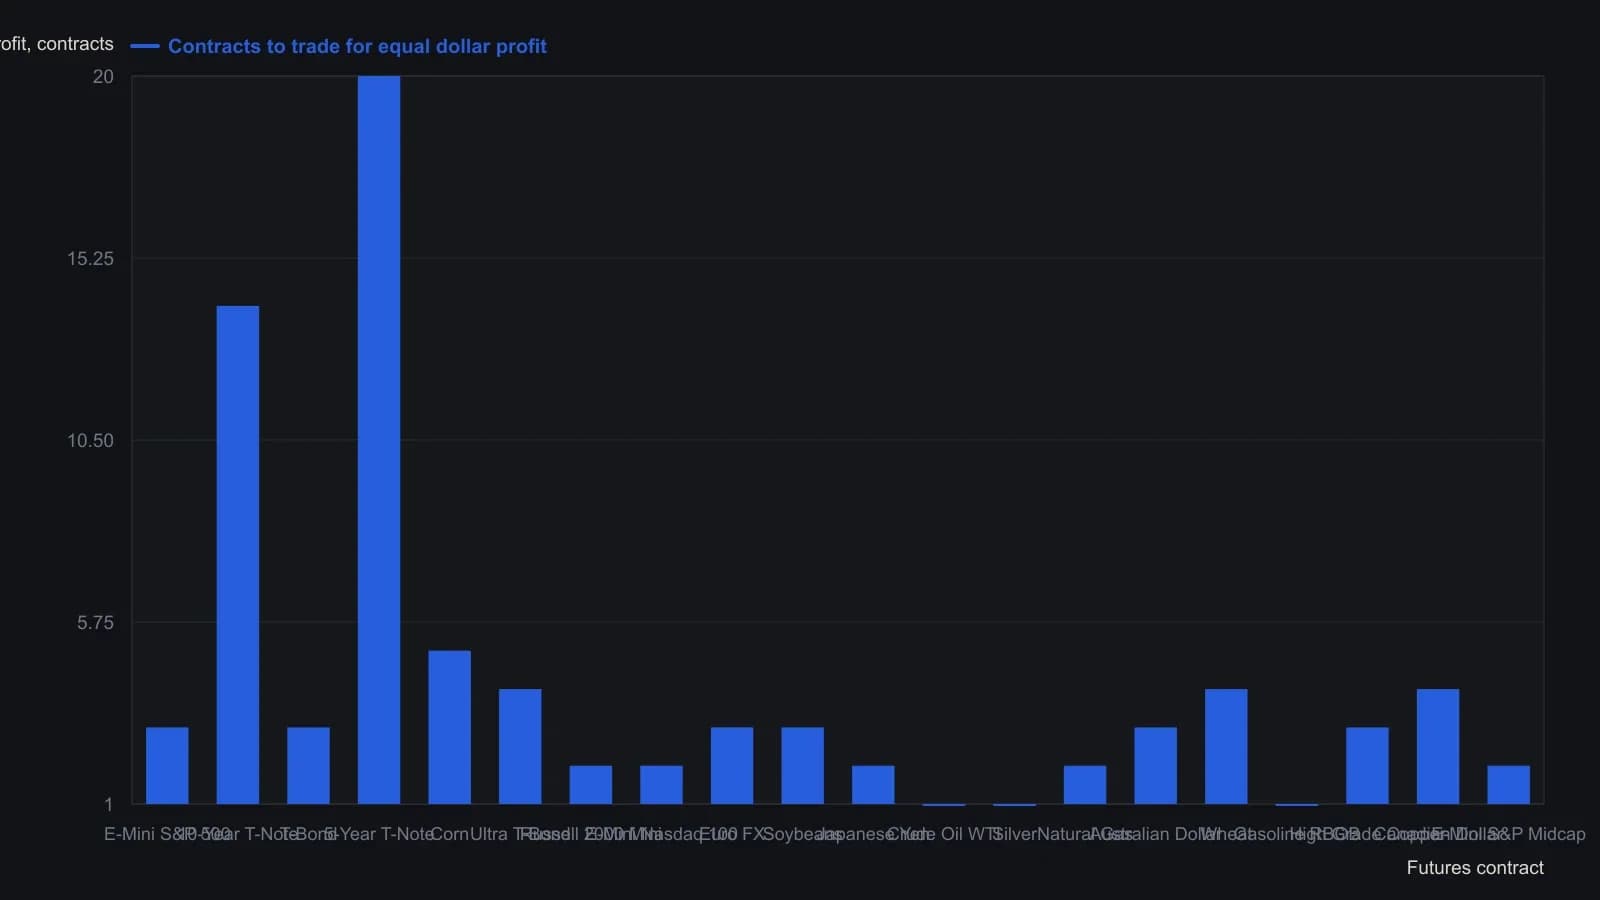
The source sets Contracts to Trade as tick dollar value times the three-year maximum price excursion, so each bar has the same notional profit potential. Relative-liquidity dots were not turned into numbers; names with one or no dots are omitted.
How to read the ranking
Each column in the comparison is a proportional measure that is meaningful only against other markets in the same column.
Contracts at the top of the relative-liquidity ranking are characterized as easier to buy and sell. Contracts at the bottom are characterized as the hardest to transact. Contracts marked with one liquidity dot or none are characterized as lightly transacted and less suitable when ready entry and exit are required.
In the supplied ranking snapshot, the E-mini S&P 500 required 3 equal-dollar contracts and led the relative-liquidity column, while 30-day fed funds required 341 contracts and displayed no liquidity dots.
Share trading liquidity
Share trading liquidity is presented as period volume expressed as a percentage of shares outstanding, that is, the turnover rate of the firm's equity. For shares, that turnover rate is offered as an equity analogue of trading liquidity.
All readings on this track · 20 readings
- 1988Wave-count consensus and open-interest confirmation
- 1990Calibrating volume and open interest at support and resistance
- 1997Grading volume and open interest after moving-average crosses
- 2003Constructing an expiration settlement map from listed open interest
- 2010Futures liquidity filter for equal-dollar size and open interest
- 2010Screen futures for tradeable liquidity before sizing
- 2011Screen futures liquidity with open interest and equal dollar size
- 2011Construct a daily initiator filter from lead-contract price, open interest, and volume
- 2012Ranking futures markets by executable liquidity
- 2013Equal-dollar open interest as a futures liquidity filter
- 2013Filter futures by open interest and relative liquidity
- 2015Filter futures contracts by open interest and volume
- 2015Screen listed futures for executable liquidity first
- 2015Money-flow lookback versus aggregated open interest
- 2016Ranking futures by executable liquidity and open interest
- 2018Futures liquidity and open interest as an execution filter
- 2019Evaluate futures liquidity with open interest and equal-dollar filters
- 2019Screen futures contracts by open interest and liquidity
- 2020Filter futures orders by liquidity and open interest
- 2020Ranking futures liquidity before you place the order