2019issue C0158
Evaluate futures liquidity with open interest and equal-dollar filters
A liquidity-filter rejects a futures contract when open-interest-weighted size cannot absorb the intended order. Survivors are then ranked on an equal-dollar scale so a wide, thin market is not treated as an easier fill than a deeper, quieter one.
- Treat contract choice as a liquidity-filter: reject a market if open-interest-weighted size cannot absorb the intended order over its life.
- Rank the contracts that pass with relative-contract-liquidity, which combines an equal-dollar-contract-count, total open interest, and a volume-factor.
- Read each ranking column only against other values in that same column. Activity marks, effective-percent-margin, and liquidity scores are separate comparisons.
- TradersWeek editorial view: this workflow is an execution screen, not a forecast of direction.
Contract selection as an execution screen
A liquidity-filter is a pre-trade accept-or-reject screen. It uses volume, spread-related cost columns, and a ranked activity scale to decide whether a contract is executable over the life of an order.
Open-interest-analysis weights a market by outstanding contracts so the liquidity rank reflects how much size is already on, not only recent prints. TradersWeek editorial reading: a name that cannot absorb intended size on that measure is discarded before any equal-dollar comparison.
Compare survivors on an equal-dollar scale
An equal-dollar-contract-count states how many contracts of one market are needed to match the same three-year dollar excursion as another market. The equal-dollar column builds that figure from tick dollar value times the three-year maximum price excursion.
Relative-contract-liquidity is the cross-market rank formed by combining that equal-dollar-contract-count, total open interest, and a volume adjustment.
How the rank is assembled
A futures liquidity rank can be built by multiplying contract point value, a three-year maximum price excursion, open interest, and a volume-factor that usually falls between 1 and 4.
A relative-liquidity score is the equal-dollar-contract-count times total open interest times a volume-factor. That volume-factor equals the greater of 1 or an exponential of log volume over log 5000, reduced by 2. In both constructions, the volume-factor is a multiplier, typically in a one-to-four range, that boosts or damps the rank for unusually thin or heavy volume.
How to read each column
Relative activity is shown as a descending mark count. The densest row is the most active, and a row with one mark or none is the least active.
Effective-percent-margin equals dollar margin divided by the three-year range of the contract’s dollar value, then multiplied by 100, so capital lock-up can be compared across markets.
For listed stocks, period volume as a percentage of shares outstanding is treated as a turnover-rate stand-in for trading liquidity.
Each ranking column is a proportional comparison and is meant to be read only against other values in that same column.
A late-2018 snapshot
In the late-2018 snapshot, the S&P 500 e-mini sat at the top of the liquidity scale, while two bitcoin futures sat at the bottom with effective-percent-margin figures of 51 and 55.6.
Contracts needed for equal dollar profit, late-2018 futures list
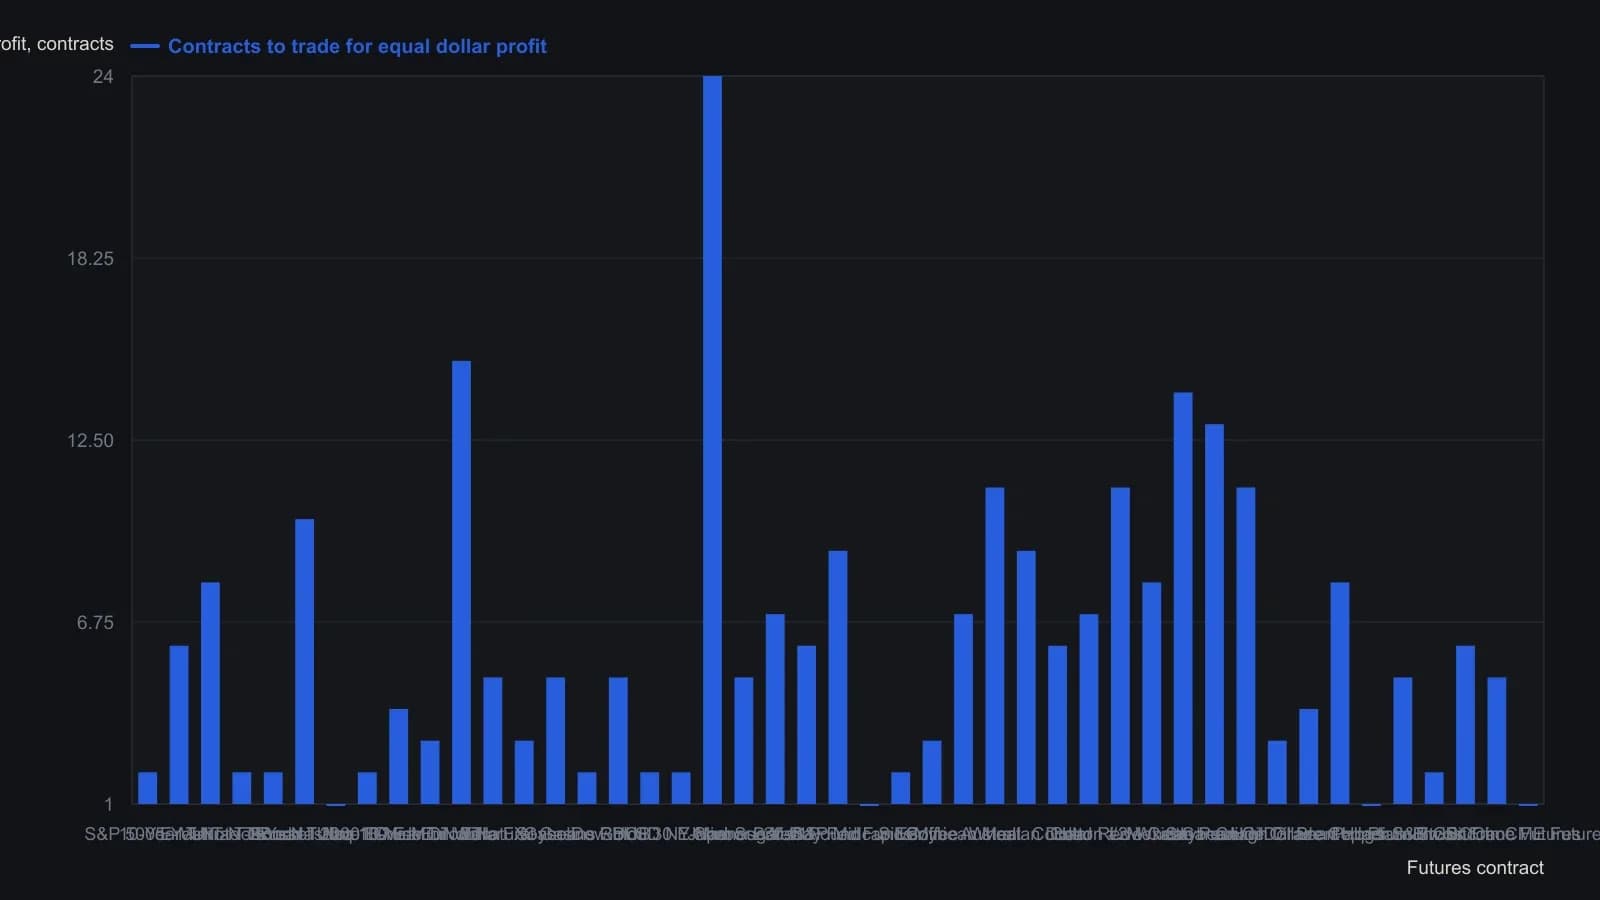
The source scaled every listed future so that contract value times the three-year maximum price excursion produces the same dollar profit; the plotted figure is how many lots that takes. Rows stay in the published relative-liquidity order. Bitcoin Cboe carried no liquidity dots in that ranking.
All readings on this track · 20 readings
- 1988Wave-count consensus and open-interest confirmation
- 1990Calibrating volume and open interest at support and resistance
- 1997Grading volume and open interest after moving-average crosses
- 2003Constructing an expiration settlement map from listed open interest
- 2010Futures liquidity filter for equal-dollar size and open interest
- 2010Screen futures for tradeable liquidity before sizing
- 2011Screen futures liquidity with open interest and equal dollar size
- 2011Construct a daily initiator filter from lead-contract price, open interest, and volume
- 2012Ranking futures markets by executable liquidity
- 2013Equal-dollar open interest as a futures liquidity filter
- 2013Filter futures by open interest and relative liquidity
- 2015Filter futures contracts by open interest and volume
- 2015Screen listed futures for executable liquidity first
- 2015Money-flow lookback versus aggregated open interest
- 2016Ranking futures by executable liquidity and open interest
- 2018Futures liquidity and open interest as an execution filter
- 2019Evaluate futures liquidity with open interest and equal-dollar filters
- 2019Screen futures contracts by open interest and liquidity
- 2020Filter futures orders by liquidity and open interest
- 2020Ranking futures liquidity before you place the order