2018issue C0358
Screen listed futures by liquidity, open interest, and margin
A listed-futures liquidity rank dollar-normalizes each contract, multiplies by standing open interest and a volume-scaled activity factor, then reads posted margin against a three-year dollar range. The screen ranks how executable a listing is before an order is chosen.
- A listed-futures liquidity rank multiplies a dollarized three-year price range, open interest, and a volume factor so thin markets can be dropped before an order is chosen.
- Open interest is used as a multiplier, so markets with more standing positions rank as easier to enter and exit.
- Effective percent margin divides posted margin dollars by the three-year dollar range of the contract, then expresses the result as a percent, to compare capital locked across listings.
- Each column is a proportional comparison and is meaningful only against other rows in the same column.
Rank listed futures before the ticket
The archive describes a historical workflow that ranks listed futures by how readily size can be transacted. The construction combines a dollarized historical range, a volume-scaled activity factor, and open interest so thin markets can be dropped before an order is chosen.
Editorial interpretation: treat the rank as a pre-ticket execution screen. Implementation cost, not the signal, is what the screen is built to judge when deciding whether an order should be sent.
Dollar-normalize the contract
A listed-futures liquidity rank can be formed by multiplying contract point value, a three-year maximum price motion, open interest, and a volume factor.
Relative contract liquidity can also be stated as the equal-dollar contract count times total open interest times a volume factor. The equal-dollar contract count equals tick dollar value times the three-year maximum price excursion, so every entry in that column shares the same dollar scale.
That shared scale is what contracts-to-trade records: the number of contracts of one listing needed to match the same three-year dollar excursion as another, so different tick values become comparable.
Multiply by open interest and a volume factor
Open interest analysis uses outstanding contract interest as a multiplier in the liquidity score, so markets with more standing positions rank as easier to enter and exit.
The volume factor is a scalar applied when activity is unusually low or unusually high. It is typically an integer from 1 to 4. It can also be the greater of 1 and an exponential transform of volume versus a five-thousand-contract baseline.
Listings marked with one activity unit or none are treated as thinly transacted and therefore weaker candidates when the screen is for ready execution.
Read margin against the three-year range
Commission analysis is a side-by-side reading of posted percent margin and effective percent margin. Effective percent margin equals posted margin dollars divided by the three-year dollar range of the contract, then multiplied by 100.
Used this way, effective percent margin compares how much capital a trade locks up relative to historical excursion, listing against listing.
Effective margin versus the three-year dollar range
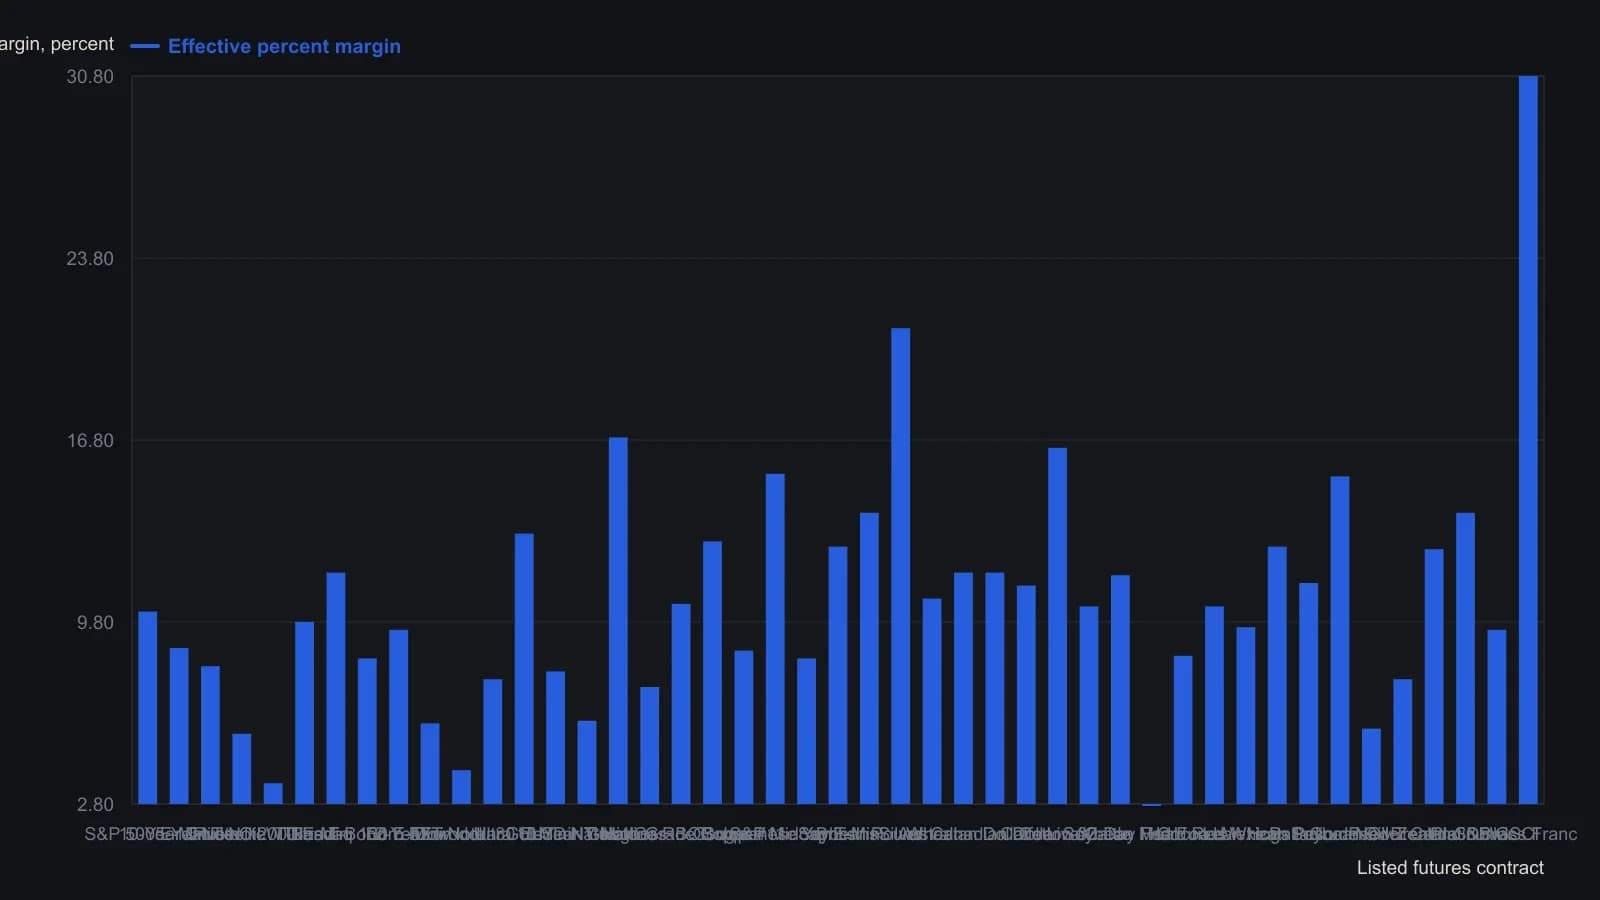
Effective percent margin is posted margin dollars divided by the three-year dollar range of the contract, times 100. Categories follow the source ranking (most executable first). The Relative Contract Liquidity dots are a glyph scale, not a numeric series, and are not plotted. Compare figures only down this column.
Compare only inside the same column
Each column is a proportional comparison and is meaningful only against other rows in the same column. Relative contract liquidity is the product of the equal-dollar contract count, total open interest, and a volume factor, and it is used only as a ranking against other listings in the same table.
On cash equities, period volume divided by shares outstanding is used as a turnover-style proxy for trading liquidity. That proxy belongs to a different market and is not mixed into the listed-futures rank.
All readings on this track · 32 readings
- 1985Matching ticket size to negotiable commission schedules
- 1985Minimum tickets can price a small book out of its own exit
- 1992Stop-order slippage as an execution cost filter
- 1993Cost-aware walk-forward evaluation of pattern-detector signals
- 2001Audit high-turnover operating conditions as one procedure
- 2002Front-load futures commission and slippage
- 2005Inactive account fees as hidden implementation cost
- 2010A pre-trade liquidity screen for futures contracts
- 2011Currency option venues, spreads, clearing, and premium cost
- 2012Filter futures contracts by liquidity and implementation cost
- 2012Futures commission versus one tick of cost
- 2012Ranking futures liquidity for executable orders
- 2013Filter option day trades by spread, volume, and fees
- 2013Filter futures by liquidity, open interest, and effective margin
- 2014Book futures data fees as implementation cost
- 2015Use a futures liquidity rank as a pre-trade checklist
- 2015Filter unexecutable futures by liquidity, open interest, and margin
- 2015Futures liquidity ranking as an execution filter
- 2015Filtering option trades by bid-ask width
- 2016Exchange quote fees as execution costs and liquidity filters
- 2016Filter futures by liquidity, open interest, and margin cost
- 2016Comparing dollar-index futures execution costs and liquidity
- 2016A futures liquidity ranking as a screen for executable orders
- 2017Filter a futures board by liquidity, open interest, and implementation cost
- 2017Filter futures contracts by liquidity and margin cost
- 2017How residency rules raise futures implementation costs
- 2018Screen listed futures by liquidity, open interest, and margin
- 2018Contract selection is the first filter on competing bitcoin futures
- 2018Filter futures execution by liquidity and margin
- 2018Commission analysis for brokerage execution costs
- 2019Ranking futures liquidity before you size the order
- 2020Brokerage selection as an implementation-cost problem