2018issue C0858
Filter futures execution by liquidity and margin
Relative futures liquidity can be scored from contract point value, a three-year maximum price move, open interest, and a volume adjustment, then ranked by how readily that interest can be transacted. TradersWeek editorial reading: treat that ranking, with equal-dollar contract counts and effective percent margin, as a pre-trade filter before any directional idea is sized.
- Relative futures liquidity is scored from contract point value, a three-year maximum price move, open interest, and a volume adjustment, then ranked by how readily that interest can be transacted.
- An equal-dollar contract count states how many contracts of each market match the same three-year dollar price excursion, so open interest can be compared on a common dollar scale.
- Effective percent margin puts posted margin against the contract’s three-year dollar range, so committed capital is visible before an executable size is chosen.
- TradersWeek editorial reading: use the descending ranking as a liquidity filter, and do not size a directional idea until open interest, equal-dollar contract counts, and effective margin make the order look implementable.
Read the ranking before the idea is sized
The archive describes a relative-liquidity score for futures. Contract point value, a three-year maximum price move, open interest, and a volume adjustment are combined, and markets are then ranked by how readily that interest can be transacted.
TradersWeek editorial reading: convert that ranked table into a liquidity filter. Let open interest analysis, equal-dollar contract counts, and effective percent margin decide whether an order is implementable before any directional idea is sized.
Score how readily interest can be transacted
A liquidity filter is a pre-trade screen that ranks contracts by how readily size can be bought or sold, using volume, open interest, dollar range, and related implementation costs.
The same relative-liquidity score is also specified as the equal-dollar contract count times total open interest times a volume factor. Markets are then placed in rank order by how readily that interest can be transacted.
Put open interest on an equal-dollar scale
An equal-dollar column reports how many contracts of each market must be traded to match the same three-year dollar price excursion. That equal-dollar contract count is computed as tick dollar value times that three-year maximum excursion.
Open interest analysis weights a contract by outstanding open interest so a deep book scores as easier to implement than a thin book with the same point value. Multiplying the equal-dollar contract count by total open interest places that outstanding interest on a shared dollar scale.
Scale the score when volume is unusual
The volume adjustment is described as a multiplier usually between 1 and 4 that scales the score for unusually low or high traded volume.
The same volume factor is also specified as the greater of 1 or the exponential of log volume over log 5000 minus 2.
Compare posted capital with the contract range
Commission analysis compares posted margin and effective margin with the contract’s multi-year dollar range so committed capital is visible before an order is chosen.
Effective percent margin is posted margin dollars divided by the three-year dollar range of the contract, then multiplied by 100. Committed capital can then be compared with historical contract-value range rather than with notional alone.
Percent margin and effective percent margin are presented together so posted capital can be compared across contracts before an executable size is chosen.
Posted versus effective percent margin for ranked futures
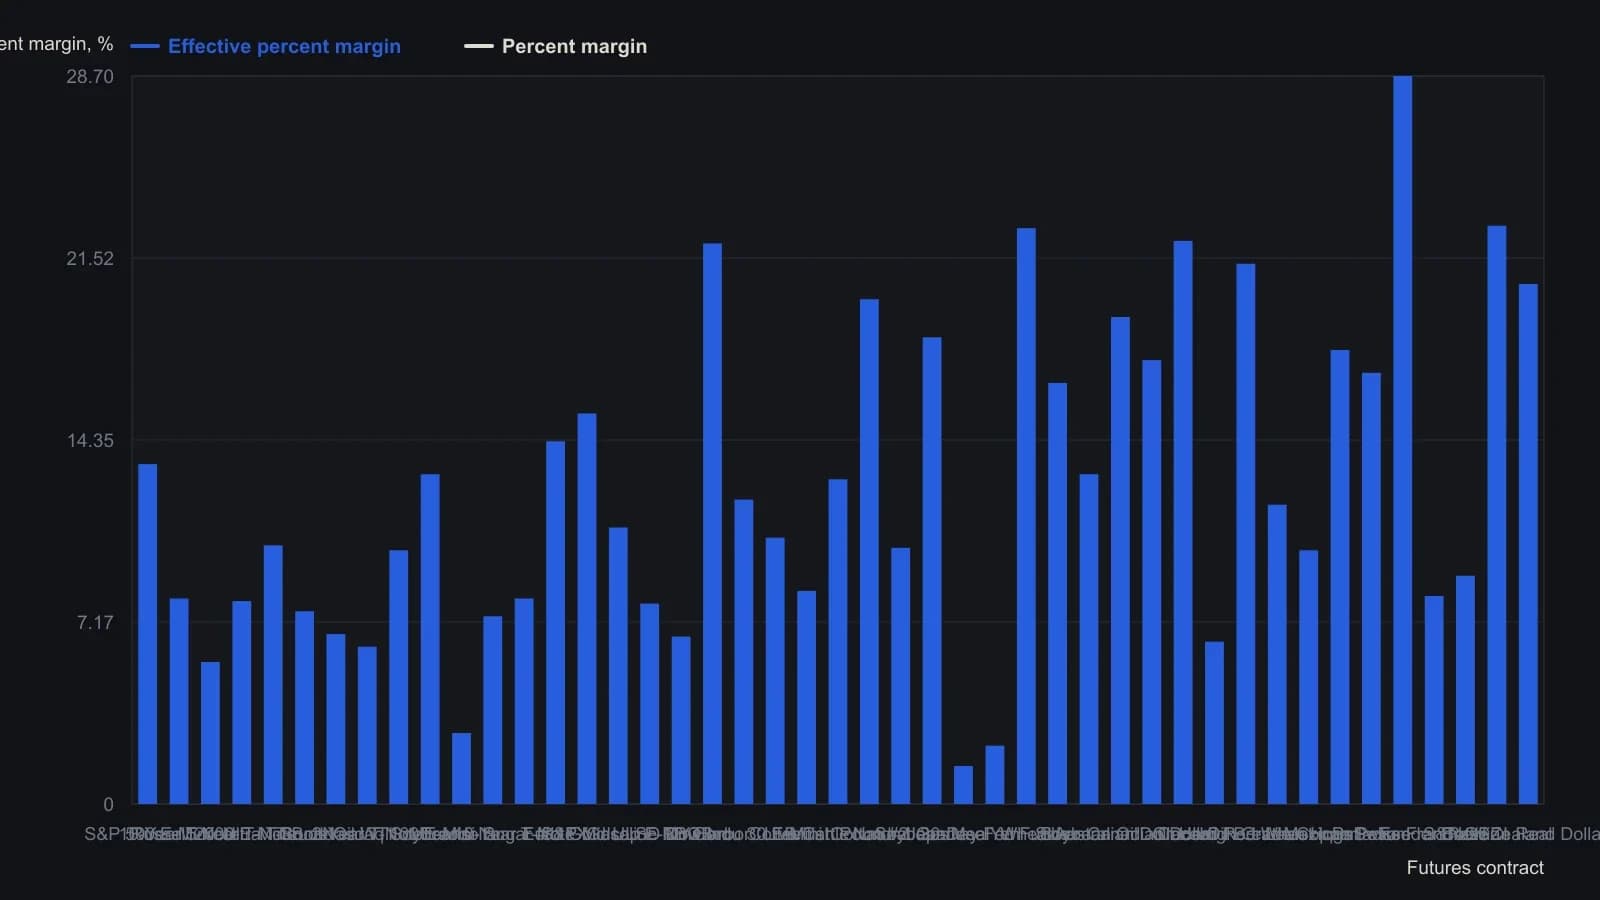
Effective percent margin equals margin value ($) divided by the three-year price range of contract dollar value, times 100, as the source defines it. Row order is the magazine’s relative-liquidity ranking, not a sort on margin. Expiries are those printed in the August 2018 listing (mostly September 2018).
Compare each column only with itself
A descending relative-liquidity ranking places the easiest-to-transact contracts at the top and the hardest at the bottom. Each column is only meaningful when compared with other markets in that same column.
A share-market liquidity proxy
For listed shares, period volume expressed as a percentage of shares outstanding is offered as a turnover-rate proxy for trading liquidity. That share turnover figure is the stock-market analogue described in the archive, not a futures ranking column.
All readings on this track · 32 readings
- 1985Matching ticket size to negotiable commission schedules
- 1985Minimum tickets can price a small book out of its own exit
- 1992Stop-order slippage as an execution cost filter
- 1993Cost-aware walk-forward evaluation of pattern-detector signals
- 2001Audit high-turnover operating conditions as one procedure
- 2002Front-load futures commission and slippage
- 2005Inactive account fees as hidden implementation cost
- 2010A pre-trade liquidity screen for futures contracts
- 2011Currency option venues, spreads, clearing, and premium cost
- 2012Filter futures contracts by liquidity and implementation cost
- 2012Futures commission versus one tick of cost
- 2012Ranking futures liquidity for executable orders
- 2013Filter option day trades by spread, volume, and fees
- 2013Filter futures by liquidity, open interest, and effective margin
- 2014Book futures data fees as implementation cost
- 2015Use a futures liquidity rank as a pre-trade checklist
- 2015Filter unexecutable futures by liquidity, open interest, and margin
- 2015Futures liquidity ranking as an execution filter
- 2015Filtering option trades by bid-ask width
- 2016Exchange quote fees as execution costs and liquidity filters
- 2016Filter futures by liquidity, open interest, and margin cost
- 2016Comparing dollar-index futures execution costs and liquidity
- 2016A futures liquidity ranking as a screen for executable orders
- 2017Filter a futures board by liquidity, open interest, and implementation cost
- 2017Filter futures contracts by liquidity and margin cost
- 2017How residency rules raise futures implementation costs
- 2018Screen listed futures by liquidity, open interest, and margin
- 2018Contract selection is the first filter on competing bitcoin futures
- 2018Filter futures execution by liquidity and margin
- 2018Commission analysis for brokerage execution costs
- 2019Ranking futures liquidity before you size the order
- 2020Brokerage selection as an implementation-cost problem