2015issue C1042-43
Overbought technology index: a long put via an inverse proxy
After the July 2015 highs, a technology-heavy index proxy was read as a support-and-volume pullback. The same thesis was then expressed with a long October call on an inverse index proxy rather than an unbounded short of the cash proxy.
- After the July 2015 highs, the technology-heavy index proxy was described as tracing lower highs and lower lows, with volume fading into those highs.
- A support-break map withheld the nearby swing-low objective, near 105 and about a 6 percent decline from the 112 area, until marked support gave way, and treated the setup as a profit-taking correction.
- An unbounded short of the cash index proxy was set aside for a premium-capped overlay: a long October 32 call on the inverse index proxy, shown near 1.85, so loss equaled the premium paid.
- Editorial reading: the same support-and-volume thesis becomes one testable procedure for entry, stand-aside, and exit, instead of an unbounded short or a commentary-led opinion.
The cash-index thesis
After the July 2015 highs, the technology-heavy index proxy was described as tracing lower highs and lower lows, with volume fading into those highs.
Index proxy comparison expressed that sector view through the liquid stand-in and then judged it against support, volume, and capital at risk.
A support-break map withheld the downside objective until the cash index proxy lost a marked support line, then aimed toward a nearby swing low near 105, framed as about a 6 percent decline from the contemporaneous 112 area.
The setup was treated as a profit-taking correction rather than a crash, with a quieter policy-news window offered as the backdrop.
The unbounded short and the inverse substitute
Selling the cash index proxy short was presented as a borrow-and-sell structure whose loss is theoretically unbounded if that proxy rallies.
That unbounded short left no fixed ceiling on the loss if the cash index proxy rallied.
An inverse index proxy was introduced as a short-horizon substitute that tends to rise when the cash index proxy falls. The vehicle in the archive was an inverse leveraged index proxy, and that inverse link was described as imperfect.
A premium-capped overlay as a long put
At an illustrated price of 32, one hundred shares of the inverse proxy required 3200 of capital. A leveraged response to a 6 percent cash-index decline was sketched toward 36.
A long October call struck at 32 on the inverse proxy, shown near 1.85, was used as the long-put-style overlay.
A long put is a defined-risk long-premium procedure whose loss is capped at the amount paid and whose payoff improves if the referenced market falls, or if an inverse proxy of that market rises.
The premium-capped overlay bought that call so the maximum loss equaled the premium outlay, while upside on the call remained theoretically open-ended if the inverse proxy rose.
The long-only contrast
A long-only hold was contrasted with using inverse proxies, or long calls on those proxies, so a falling cash-index tape still had a defined procedure.
QQQ daily price against the $105 breakdown target
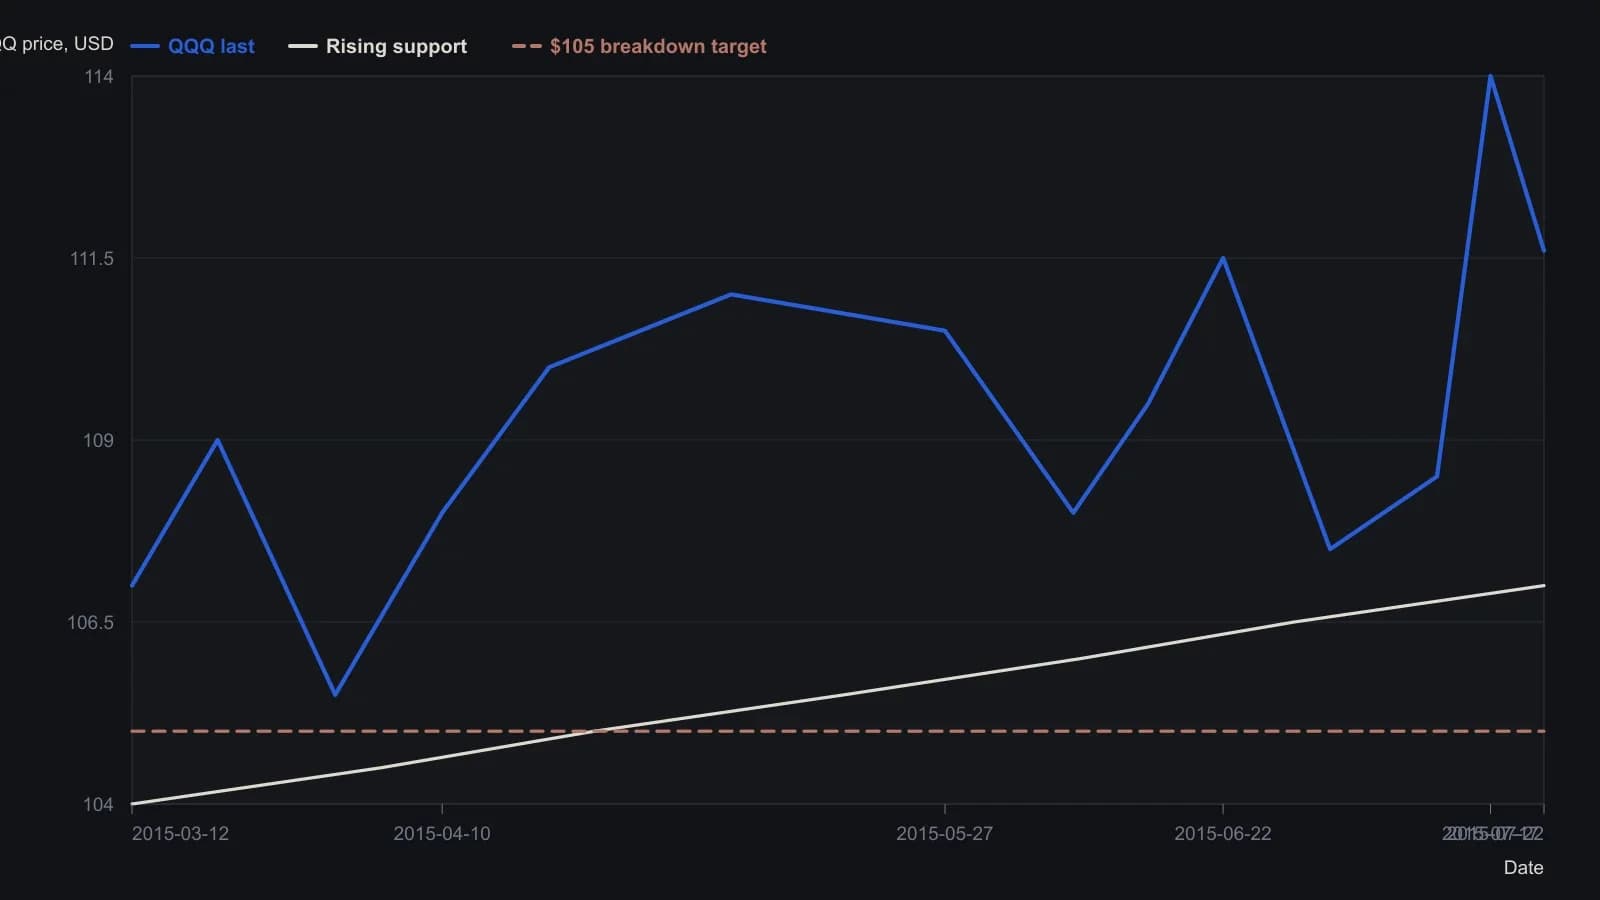
Daily candles were sampled at the printed date ticks and at the visible swing highs and lows, rounded to the nearest half dollar except the printed close. Intra-day wicks between those marks are not restated. The rising support series is the red channel line on the same figure, read to about 0.5 dollars.
All readings on this track · 22 readings
- 1984A long silver put as a prepaid loss cap
- 1984Spectral window gates for index long puts
- 1990Breadth nonconfirmation as the gate for a volume fade and long-put case
- 2002Volatility-first construction for a bearish put or debit
- 2002Name the regime and the season before choosing a long put
- 2005Critique of put spreads versus outright long puts
- 2007Sector put hedges, automatic exercise, and pin risk
- 2008Margin shock, defined-debit options, and selective premium
- 2008Ranking in-the-money puts by breakeven rather than cheapest premium
- 2012Evaluating long-put moneyness when implied volatility shifts
- 2012Sizing a long butterfly for early assignment and a long option for gamma
- 2013Gold after the April break: option-spread vehicles and a long-put hedge
- 2014A defined-risk option case for the mid-February to mid-July energy window
- 2014Long put versus vertical debit spread on a Treasury ETF
- 2015Defined debit call spread on a health-insurer worksheet
- 2015Overbought technology index: a long put via an inverse proxy
- 2018Replace futures stops with short-dated long puts
- 2018Constructing short-dated long puts around weekly expiration
- 2018Four decisions before a portfolio protective put
- 2018Incremental producer hedging with puts and risk reversals
- 2019Put butterfly versus long put in a volatility spike
- 2020Scenario-first SPY put hedge: butterfly versus long put