2010issue C0828-31
Normalized volatility as a testable regime switch
A volatility confirmation is framed as one procedure that stays long, flips short, or keeps adding. The editorial question is whether that whole procedure can be specified, optimized, and stress-checked without treating a single test figure as a plan.
- Trend identification is treated as incomplete when it rests on a single long moving-average rule, so a second volatility confirmation is added.
- A single regime-threshold assigns a bull or bear book, then runs exit, abstention, and a daily pyramiding-rule as one procedure.
- The cutoff comes from a grid search with several optima, not from a unique solution.
- Editorial reading: robustness figures such as recovery-factor check whether the rule can endure long drawdowns. They are not a trading plan.
Why a second confirmation is added
The archive frames trend identification as incomplete if it rests on a single long moving-average rule. It proposes a second, volatility-based confirmation step because any one indicator can fail.
The confirmation measure is a normalized-volatility-indicator, a scale-free volatility ratio formed from a multi-week average true range divided by the latest close. The construction is chosen so a quarter-length window can be compared across decades after seasonal level effects are reduced.
One cutoff for stay, flip, or add
The decision process is a two-sided regime switch at a single regime-threshold. Above the cutoff, the procedure closes longs and adds shorts daily. Below it, the procedure closes shorts and adds longs daily.
That daily add is a pyramiding-rule: one unit in the same direction while the regime signal remains in force. Abstention sits in the same procedure. Once the threshold is crossed, the prior side is not held.
The accompanying code makes entry, exit, and continued adding one executable sequence. Compare the ratio with the chosen threshold, flatten the opposite book, then trade one unit in the new direction each day while the regime persists.
Daily S&P 500 backtest at NVI cutoff 1.343
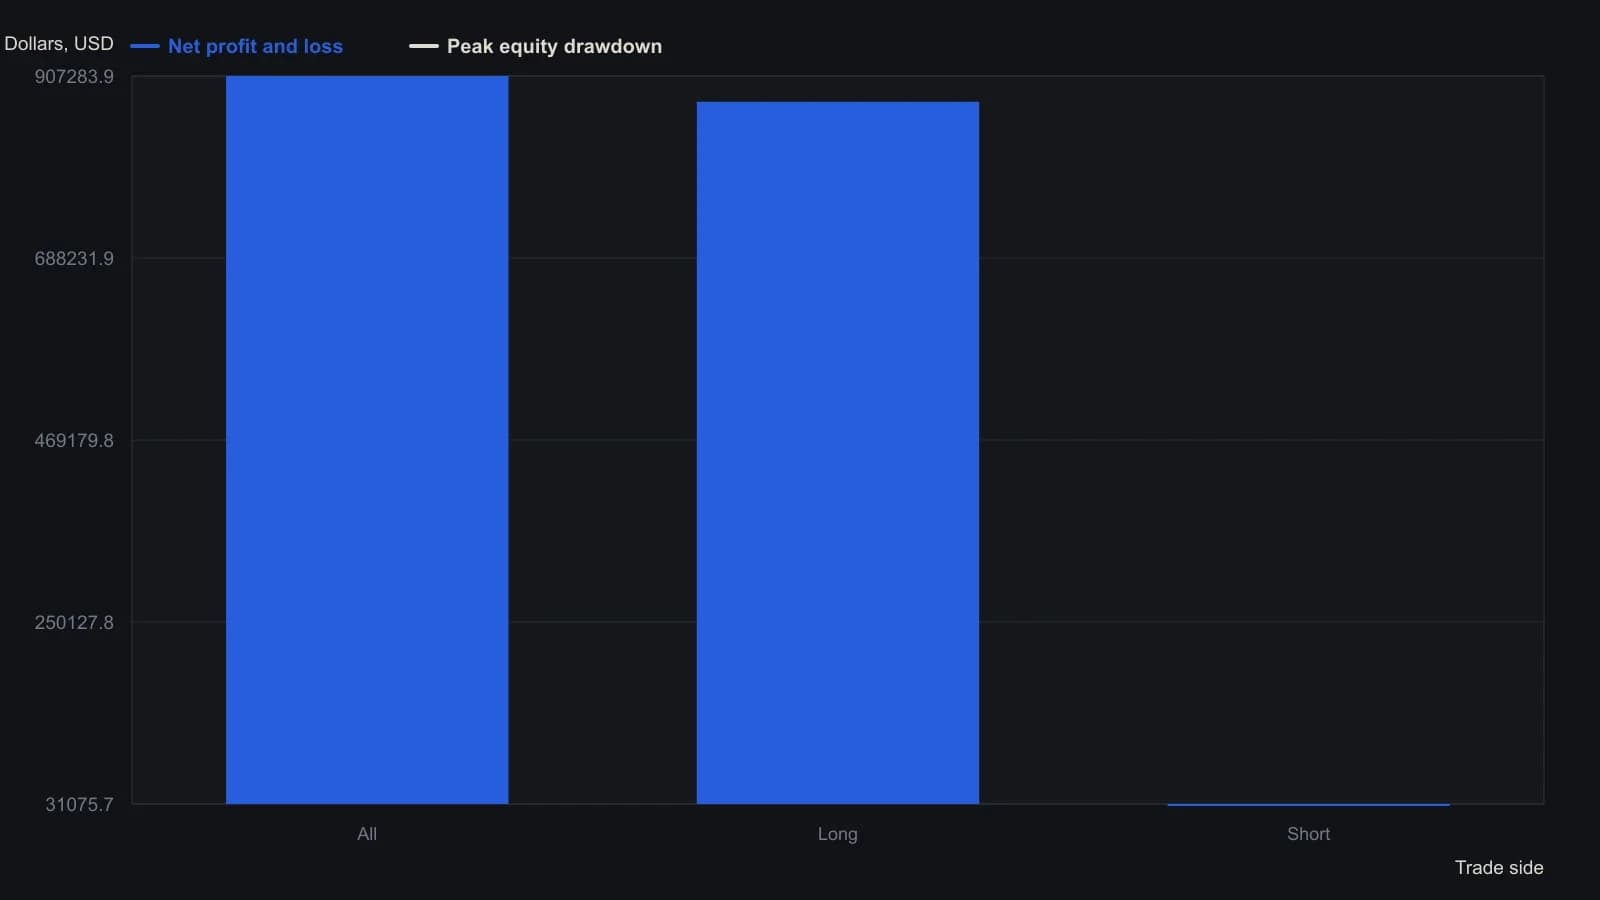
The 1.343 cutoff is one of several optima from a 1.000–1.500 search in 0.001 steps. The run omits commissions and uses a large initial account relative to the one-share-per-day add-on rule.
A searched cutoff, not a unique key
The cutoff itself was selected after a grid search over a narrow band of candidate values on a long index sample. The archive reports one reading as one of several optima rather than a unique solution.
The same procedure is presented as having given earlier warning before a cyclical decline, a closer alignment with a later advance, and a timely mark of a later downturn on a long-span index chart.
Chart annotations at the start of that downturn show the index beside a volatility ratio that sat above both a shorter average and a longer average, illustrating a bear-regime reading as that cycle began.
What the robustness check is for
Published test statistics at the chosen cutoff include recovery-factor, win rate, profit factor, and payoff ratio. The text treats those figures as evidence the rule can endure long drawdowns rather than as a high hit rate.
Recovery-factor is used here as a robustness check rather than a forecast of future returns.
Editorial: those checks describe the historical workflow. They do not establish present-day performance, and they do not convert the procedure into standing advice.
All readings on this track · 89 readings
- 1988Habitual decision style can override a trading system's rules under stress
- 1988Abstention and self-checks complete the procedure
- 1988When packaged systems replace a testable decision process
- 1991Fighting market direction as a process failure
- 1993Replacing beliefs that override a testable trading procedure
- 1993Fear as a named constraint in entry and exit rules
- 1993Body state on the trading checklist
- 1994When fear vetoes a tested trading system
- 1994Slump recovery as a testable decision procedure
- 1994Hesitation as an incomplete decision process
- 1994Trading weaknesses as testable process inputs
- 1994Mental imagery as an unlogged execution filter
- 1994Comfort-zone overrides of testable trade rules
- 1995Emotion rebound as a system rule failure
- 1995Evaluating emotional overrides in a rule-based decision procedure
- 1995Construct centering into entry, exit, and abstention
- 1995Resistance-audit for trading rule construction
- 1995Single-mode thinking leaves gaps in trading decisions
- 1995Psychology is the trading system's execution layer
- 1995Operator burnout as decision-process failure
- 1995When success breaks the trading procedure
- 1996Between-trade recovery as one decision procedure
- 1996Isolation in a losing stretch belongs in the written procedure
- 1996When goal proximity overrides one trading procedure
- 1996When emotional overload breaks testable rules
- 1996Trader-created losses as decision procedure failures
- 1996Inner commentary as an unlogged system override
- 1997Inner forecasts that override system hold rules
- 1997A conscious rebuild of trading rules after change
- 1997Streamline trading rules until the signals agree
- 1998Happiness as a tradable decision process
- 1998Warfare metaphors as untested trading rules
- 1998Constructing a generosity gate for trade decisions
- 1998Why trading systems need a sensory decision base
- 1999Shock, abstention, and the decision handoff
- 1999Rewrite trading nightmares before they become rules
- 1999Anxiety as a trading-system construction checkpoint
- 1999When revenge replaces the abstention rule
- 2001Money beliefs that veto trading rules
- 2001Ignored sells need an execution filter
- 2001Courage fails unless trading rules are written and tested
- 2003When compulsion rewrites the trading procedure
- 2004When tested rules fail to fire
- 2004Precommit exits when regret outweighs pride
- 2005Audit personal stories before blaming the trading rules
- 2005Why tested systems still fail at execution
- 2007Losing streaks test the whole procedure
- 2007Pre-trade protection rules for surprise declines
- 2007Defensiveness rewrites testable trading rules
- 2008Observer-self as a filter for entry, exit, and abstention
- 2008The holding-period rule for post-fill arousal
- 2010Treat psychology as part of the trading procedure
- 2010Normalized volatility as a testable regime switch
- 2012Post-loss self-talk as an intraday rule-input
- 2012Write uncertainty into one trading procedure
- 2012Milestone rallies need entry, exit and abstention rules
- 2012Mental fitness as the missing decision rule
- 2012Session close is a flatten rule, not overnight hope
- 2012A signal without a sit-out is not a system
- 2012Beliefs that rewrite system entry and exit signals
- 2012Live loss rewrites the rule-based decision process
- 2013Market access as a missing system rule
- 2013Skipped exits and the unplanned hold
- 2013Test entry, exit, and abstention as one procedure
- 2013Crowd sentiment as one testable decision loop
- 2013Keep social noise outside the rule set
- 2014Community feeds versus testable decision rules
- 2014Outcome control versus testable execution rules
- 2014Liquidity eligibility as a testable system rule
- 2015When the fill replaces the hold rule
- 2015When loss aversion overrides testable hold and exit rules
- 2015Pause and objectify before trade decisions
- 2015Clutch delivery as the unfinished trading rule
- 2016The failure protocol inside a trading decision process
- 2016When trading psychology becomes a testable process
- 2016Psychology belongs inside the trading rule set, not beside it
- 2016Trader maturity stages as a critique of an unfinished decision process
- 2017Quiet volatility is not a complete trading process
- 2017The plan-trust gap after live-testing
- 2017When a winning hold is not system adaptation
- 2017Risk-first rules instead of year-ahead forecasts
- 2018Why-first stories leak the tape test for entry, exit and abstention
- 2018Replace intuition with a testable decision procedure
- 2018Make regret a testable stand-aside input
- 2018Exit rules over fear when volatility returns
- 2018When inherited instincts override trading-system rules
- 2018Averaging down as hope substitution after a seed loss
- 2018Click rankings cannot replace a testable decision procedure
- 2020Living-cost pressure as an untested trading constraint