2020issue C0630-39
One checklist for breakout entry, stops, and sitting out
This case study turns an early stretch of unwritten losses into one pre-trade checklist. The same tests that authorize a strength breakout also force a predefined stop and, when no names qualify, force cash.
- Write one pre-trade checklist that covers setup quality, timing, size, stop, and the option to stay flat.
- Use rule-based entry: buy qualifying breakouts in the order they trigger, then let a predefined stop decide if the idea is wrong.
- Treat repeated stop-outs and a lack of qualifying setups as the abstention signal, not as a separate forecast.
- The trading psychology process is what decides whether those written rules are followed when the trade is uncomfortable.
From unwritten losses to one procedure
The interview presents an early stretch of losses lasting six years. That stretch was attributed mainly to missing experience, knowledge, and written rules. Concrete rules and strict discipline formed only later.
The later process reversed the first habits. Instead of buying cheapness near new lows, the written work bought strength near new highs. Losers were cut quickly. Winners were held longer.
TradersWeek editorial reading: the value of the case is not a personality story. It is that reversed beginner habits can be restated as one testable loop for entry, exit, and abstention.
Four checks used together
The large-result procedure was stated as four checks used together: timing, concentrating capital, turning a defined edge over frequently, and managing risk versus reward. That last check included a stated minimum two-to-one reward-to-risk and a shorter horizon for losses than for gains.
Concentration meant most capital sat in a handful of names during the periods described as strongest, often four to eight, sometimes with extra smaller or half-sized lines around that core. Turnover meant repeating a defined edge as often as conditions allowed, rather than holding for its own sake.
Preferred market-state inputs were price, volume, and a few moving averages. Calculated oscillators were rejected as unable to lead the price they are derived from.
Entry, stop, and cash as one test
Rule-based entry was specified as buying breakouts in the order they meet criteria, without favorites. A specific entry point is a precise buy level where stated conditions converge, so a wrong idea is visible quickly. A predefined stop then decides whether the idea is right or wrong.
Directional bias belongs in the same sequence. Trades were taken only after price was moving with the intended side, including the later habit of buying strength rather than weakness.
Sitting out was treated as part of the same procedure. Repeated stop-outs and a lack of qualifying setups were the signal to stay in cash, not a separate market forecast. That is abstention: staying in cash when the tape is not offering merchandise.
Drawdown control and size
Drawdown control was given as a four-step checklist: sell into strength, raise size only when results confirm, trade with the prevailing direction, and protect breakeven without immediately choking the remaining position.
Those last two steps map onto directional bias and de-risking. Progressive exposure is the size rule that sits beside them: increase size and activity only after results confirm the process, and cut both when stops fire repeatedly.
Why the written rules get used
The psychology layer was described as taking on the beliefs of high performers, named as discipline, vision, persistence, and self-belief. That trading psychology process was presented as the factor that decides whether known skills are actually applied.
TradersWeek editorial reading: the uncomfortable part of the loop is the part the psychology process has to carry. If the written tests are dropped when a breakout feels late, a loser feels personal, or cash feels idle, the procedure is no longer one procedure.
Citigroup monthly share price, 2001–2020
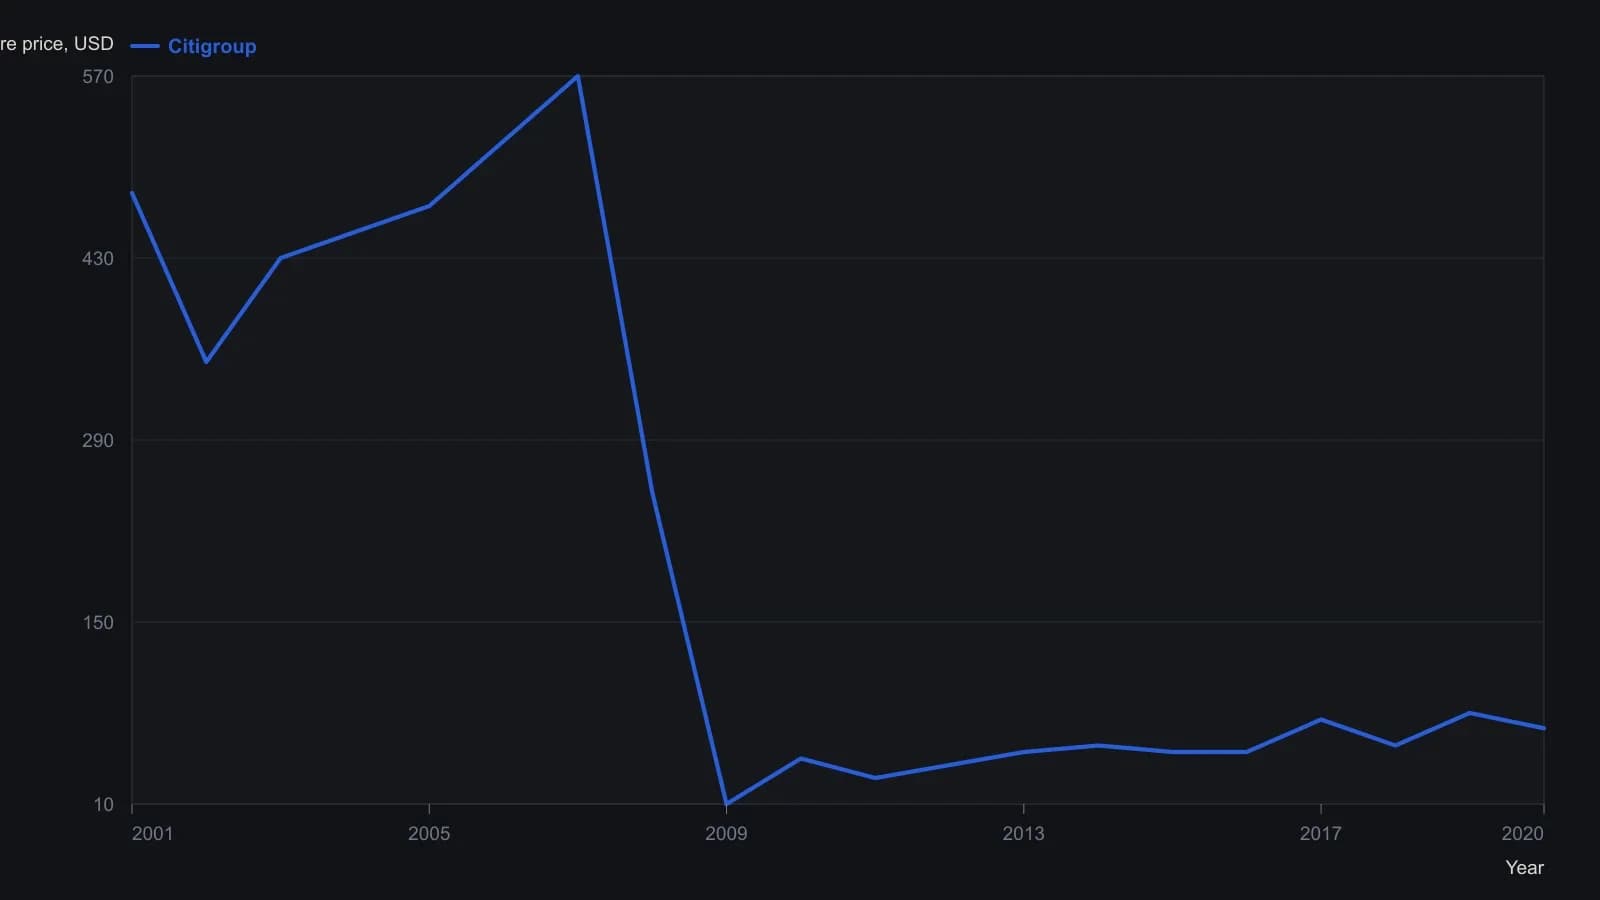
Monthly candlesticks with a 20-month average, snapshot dated 27 Feb 2020. Pre-crash yearly points are approximate to the nearest few tens of dollars because the upper grid is tight on the raster; post-crash points sit on the visible 25/50/100 dollar labels. Volume in the lower pane is not plotted here.
All readings on this track · 135 readings
- 1987Pair each checklist step with its decision state
- 1987Position secrecy as decision-process control
- 1987When profits break the trading process
- 1988Treat action-seeking as a veto before any signal
- 1988Entry, exit, and abstention as one practiced procedure
- 1988Making inner conflict a testable trading rule
- 1988The chart is only half the trading procedure
- 1988Negotiate conflicting parts before the signal
- 1989Commitment turns trading rules into one procedure
- 1989Confidence, discipline and the fit of a trading procedure
- 1990Encoding expert hunches into a mechanical trading loop
- 1991The consecutive-loss halt as the trading system
- 1991A fuzzy membership checklist for trade signals
- 1991Overconfidence as a skipped pre-trade checklist
- 1991A source-reliability audit for trade signals
- 1991Shared rules fail without an execution checklist
- 1991The daily study block as a low-risk checklist
- 1992A bear-market loss review that rewrites the pre-trade checklist
- 1993Unspoken beliefs that veto system rules
- 1993Why a mechanical system beats betting harder when the story looks cheaper
- 1993A usable process over a perfect trader standard
- 1993Remold the decision-map after a traumatic trade
- 1994Keep entry, exit and sit-out as one procedure
- 1994Pre-trade gates for belief and state
- 1994Known failure points inside the yen triangle phase checklist
- 1994When a comfort ceiling, not market state, is the failure mode
- 1994Trading commitment as a balanced decision process
- 1994Constructing a pre-trade discipline checklist
- 1995Futures systems start with whether to trade
- 1995Stopping points as checklist and stop failures
- 1995When analysis and execution must become one procedure
- 1995A decision-process database from analyst to trader
- 1995Decisive execution as one tested procedure
- 1996The unfinished-system trap in simple decision rules
- 1996When risk breaks practiced system execution
- 1996Treat the mechanical signal as a draft, not a decision
- 1996Critique of decision states that break system rules
- 1996State-gate checklist for trading decisions
- 1996Personality-fit rules before earned intuition
- 1996The commitment gap as a testable decision process
- 1996Test decision style as one trading procedure
- 1997Mechanical trading before subjective judgment
- 1997Belief checklists that invalidate mechanical systems
- 1998Mechanical rules against mindtraps
- 1999The profit target as a trading discipline lens
- 1999When mechanical rules replace judgment in the trade process
- 1999Trading discipline as one testable procedure
- 1999Daily pre-open map as one procedure
- 2000Session veto from daily readiness
- 2000Anger buildup as an untested system input
- 2000Construct separate research and live-trade question checklists
- 2000Operator-state as a first-class trading rule
- 2001Day-trading rules need a pre-trade decision process
- 2001Review the operator before you rewrite the plan
- 2001Critique of the informal trading pause
- 2001Specificity turns wishes into checkable trading rules
- 2002The pre-entry plan that locks exits and size
- 2002Risk identity as a pre-trade system gate
- 2002When elapsed time rewrites trade rules
- 2002One written system, faster exits, and the belief gate
- 2003Countable decision trees for entry and abstention
- 2003Constructing a pre-trade stop and review procedure
- 2004Psychological wounds that override a tested system
- 2004A hot streak does not retire the trading checklist
- 2005Why mechanical trade plans fail without execution discipline
- 2005Resentment as a construction input for trade decisions
- 2005A daytrade as one written procedure
- 2006Write the pre-trade plan as one procedure before entry
- 2006When a winning streak makes the trade checklist optional
- 2007An entry needs a pre-trade risk bound and a post-trade debrief
- 2007A pre-session futures plan that locks entries, exits, and stops
- 2007Maxims fail without one testable procedure
- 2007Personality-fit and holding horizon before the pre-trade checklist
- 2008Push-button systems versus a testable decision process
- 2008Written rules omit the operator and the implicit filters
- 2008A Pre-trade checklist before emotion takes over
- 2008System design between the mechanical black box and checklist judgment
- 2008Trade history as a checklist for entry, exit, and abstention
- 2008Mechanical rules without a decision process
- 2008Parable checklists for entry, exit and abstention
- 2010Keep rule-based entries clear of news bias
- 2010Self-control zones before the pre-trade checklist
- 2010Treat the pair-desk day as one testable procedure
- 2010Use a five-factor checklist instead of pattern labels
- 2010Listed currency futures versus spot forex as a pre-trade venue checklist
- 2010Rule overload, unfinishable checklists, and tight stops
- 2010Pre-trade checklist versus automatic stops
- 2010Skipping signals after a losing streak is a new system
- 2010Stand aside until the relationship breaks
- 2010A software catalog fails the checklist without one testable procedure
- 2011Checklist rules versus unwritten indicator judgment
- 2011The handoff test for self-coached trading plans
- 2011Unify locate status, written rules, and self-talk on one checklist
- 2012A pocket card and a setup-chart as the session-plan
- 2012Close system construction with a review checklist
- 2012A pre-trade checklist versus in-trade emotion
- 2013The ten-question alignment gate when traders lose the path
- 2013A stuck-point audit for stalled trading decisions
- 2013Why rule-based entries need false-trigger checks
- 2013One procedure for liquidity rules and abstention
- 2013The month-open window is unfinished without cash default and a substitution checklist
- 2014Waiting fails when the pre-trade checklist is too wide
- 2014A swing procedure with a checklist, layered stops, and an emotion handoff
- 2014System design as a critique of forecast-worship
- 2014Consultant hiring as an accept-or-abstain checklist
- 2014One procedure for entry, exit and abstention
- 2014A trading system that cannot decide before the chart opens
- 2014The checklist veto when tools override the plan
- 2014Write the holding-period style before any daytrading rules
- 2015A pre-trade checklist when volatility turns rules into panic
- 2015A checklist, psychology gate, and moving-average procedure
- 2015Write forex entry and sit-out rules before you score the links
- 2015Daily if-then checklists versus year-ahead market forecasts
- 2015Workstation readiness in the pre-trade execution checklist
- 2015An unprepared trade fails the pre-trade checklist
- 2015Evaluate a system with one pre-trade checklist
- 2015The pre-trade checklist as one testable procedure
- 2015News-aware forex process with defined stops
- 2016Slow thinking over gut feel in complex markets
- 2016When a market-structure story rewrites a checklist yes
- 2017Constructing an options trading-plan from a self-inventory
- 2017A price-first checklist for noncooperative market games
- 2017A pre-trade risk checklist versus profit-first thinking
- 2018A forex onboarding ladder is not a decision process
- 2018Pre-trade regret scripts for entry and abstention
- 2018Audit the plan while the tape stays forgiving
- 2018Constructing a sortable pre-trade checklist
- 2018Forex myths that break a testable decision process
- 2018Why trading checklists must beat inherited confidence
- 2019Leverage as a pre-trade gate in mechanical systems
- 2019Critique of impulse trading as a testable system
- 2020One checklist for breakout entry, stops, and sitting out
- 2020A continuity checklist for a blank Sunday-night system desk
- 2020After an extended bar, the checklist must still be able to refuse
- 2020Write one procedure before outsourcing system decisions